September 29, 2026
Bonus Content: Hapag-Lloyd More Than Doubled Its Profit Forecast. Container Shipping Is Where the Money Is.
Editor’s Note: Jeff Brown is a former tech executive who picked Nvidia in early 2016, before shares jumped as high as 36,000%. Marc Chaikin is a 60-year Wall Street titan who’s worked with billionaires and hedge fund legends like Paul Tudor Jones, George Soros, and Steve Cohen. Together, they just issued a rare buy alert on a little-known Elon Musk supplier. Click here to see the details or read more below.
Dear Reader,
Could this revolutionary new invention from Elon Musk pop the AI bubble…
Or is it just going to trigger the next wave of massive AI gains?
For the first time ever…
The two investment legends who picked Nvidia 10 years ago…
Are coming together to answer that question.
If you’re wondering how much longer can this AI boom last…
And what you should do with your money now…
Click here to watch this controversial interview with these two legends.
Jeff Brown is a former tech executive who picked Nvidia in early 2016…
Before shares jumped as high as 36,000%.
Marc Chaikin is a 60-year Wall Street titan who’s worked with billionaires and hedge fund legends like Paul Tudor Jones, George Soros, and Steve Cohen.
And they recently came to a shocking conclusion.
They both believe you need to make this move before September 30. (Click here to see the details.)
Regards,
Lindsey Hough
Managing Director, Brownstone Research
P.S. By the way, when you click here…
They’ll also give you the name and ticker symbol of a company that has been called “the next Nvidia…”
Completely free of charge.
Hapag-Lloyd More Than Doubled Its Profit Forecast. Container Shipping Is Where the Money Is.
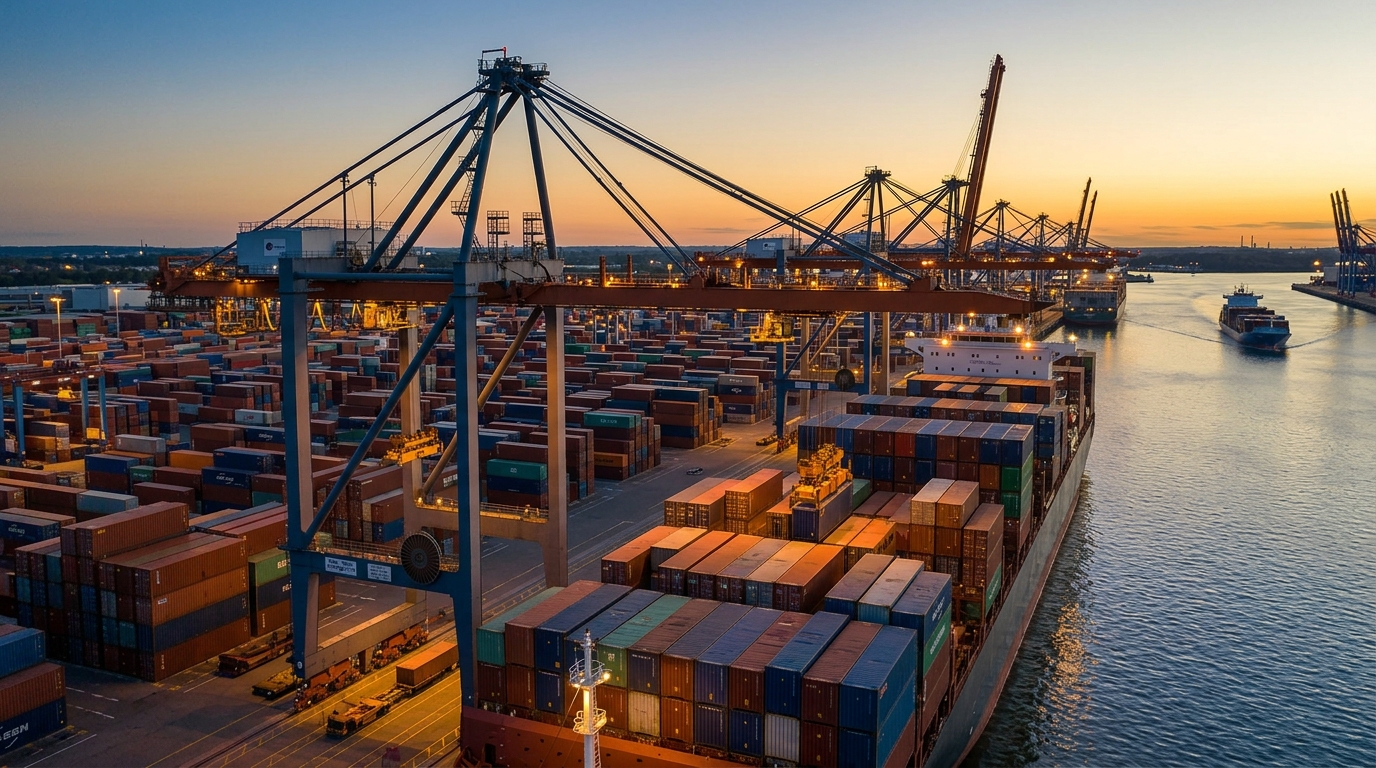
Most of the shipping conversation this year has lived in tanker land: crude routes, sanctions plays, Red Sea detours. Meanwhile, container carriers quietly rebuilt a profit cycle, and this week Hapag-Lloyd made the size of that move impossible to miss.
Hapag-Lloyd raised its group EBIT forecast for 2026 to $1.25 billion to $1.75 billion, up from a prior range of $0.1 billion to $1.1 billion, citing strong market demand and the ongoing positive development of freight rates. Group EBITDA guidance was lifted simultaneously to $3.9 billion to $4.4 billion from $2.7 billion to $3.7 billion. That is a midpoint EBIT jump of roughly $900 million. For a company that posted a first-half net loss, that revision is a significant change in trajectory.
The stock move in Europe has been noticeable, but not frenzied. That is worth noting. When a guidance raise of this magnitude produces a calm gain rather than a gap, it tells you one of two things: the market already suspected better numbers were coming, or traders still do not fully trust the durability of spot rates. Probably some of both.
Hapag-Lloyd is not alone in revising upward. Maersk grew more optimistic about the remainder of 2026 and raised its full-year underlying EBITDA outlook to between $8 billion and $10 billion, up from its previous forecast of $4.5 billion to $7 billion. Maersk attributed the improvement to continued market strength, particularly in Asia, and a sustained rise in spot freight rates that supported carrier profitability despite ongoing geopolitical uncertainty. On the transpacific side, Matson’s second-quarter consolidated operating income rose to $158.9 million versus $113.0 million a year earlier, with its China service as a clear engine of growth, benefiting from tight transpacific capacity and robust demand.
The rate environment behind these revisions is real. From early to mid-September, container shipping markets saw sustained transpacific demand, with rates between Shanghai and Los Angeles rising roughly 5 percent week on week to around $7,185 per 40-foot container. That is a freight market running well above where carriers were budgeting at the start of the year.
The noise around Hapag-Lloyd right now is mostly the ZIM deal, and understandably so. Opposition to Hapag-Lloyd’s roughly $4.2 billion takeover of ZIM has been reported in Israel, with labor representatives raising national-security and operational-control concerns tied to Hapag-Lloyd’s shareholder base and the proposed structure for ZIM’s Israel operations. Foreign shareholders’ control of Hapag-Lloyd has been a particular concern in Israel, given the large stakes held by the sovereign wealth funds of Qatar and Saudi Arabia.
The ZIM situation is legitimate deal risk. But experienced traders know the lesson here. Deal noise is a distraction from the operating business. The guidance raise says the core freight business is outperforming, and that matters regardless of whether the acquisition closes on schedule.
The broader point for traders is about where to direct attention. Container shipping consensus was bearish coming into 2026: too many new vessels, too much capacity, rates heading lower. That consensus was wrong. The carriers benefiting most from that error are names like Hapag-Lloyd, Maersk, and Matson, all of them reporting freight demand that exceeded expectations on both volume and rate.
The Trader’s Lesson
Sector consensus is most dangerous when it is most uniform. Early 2026 brought near-universal agreement that container shipping was entering a down cycle. When every analyst on a sector says the same thing, the asymmetry of being wrong grows quietly. The carriers that held pricing power proved the bears wrong before most investors repositioned. The move worth studying is not whether to buy shipping stocks today. It is how to identify the next sector where a uniform consensus is masking a different reality underneath.