Two numbers arrive at 8:30 AM ET today, and they do not carry equal weight. The Q2 GDP third estimate will get a headline or two. The August PCE report is the one that moves markets.
Here is why this particular reading matters more than most. The Federal Reserve’s September 16, 2026, decision to raise the federal funds target range by 25 basis points to 3.75%-4.00% was its first hike since July 2023. In the Fed’s September projections, a majority of FOMC participants still penciled in at least one additional move by year-end. And today’s number is the last inflation data they will see before the October 27-28 meeting.
What Happened Overnight in the Bond Market
The yield on the US 10-year Treasury resumed its climb to about 5.28%, a level last seen in the mid-2000s. The 30-year rate pushed above 5.6%, the highest level since the early 2000s. Yields eased slightly Wednesday morning as some of that selling pressure abated, with the 30-year last seen around 5.55%. The benchmark 10-year yield is up roughly 46 basis points in September alone. That is a violent shift in four weeks, and it has not finished adjusting.
Recent pressure on yields reflects a mix of inflation anxiety and shifting expectations for future Federal Reserve decisions. Energy has been part of that story, but it has not been the only driver.
The Two Scenarios Traders Are Pricing
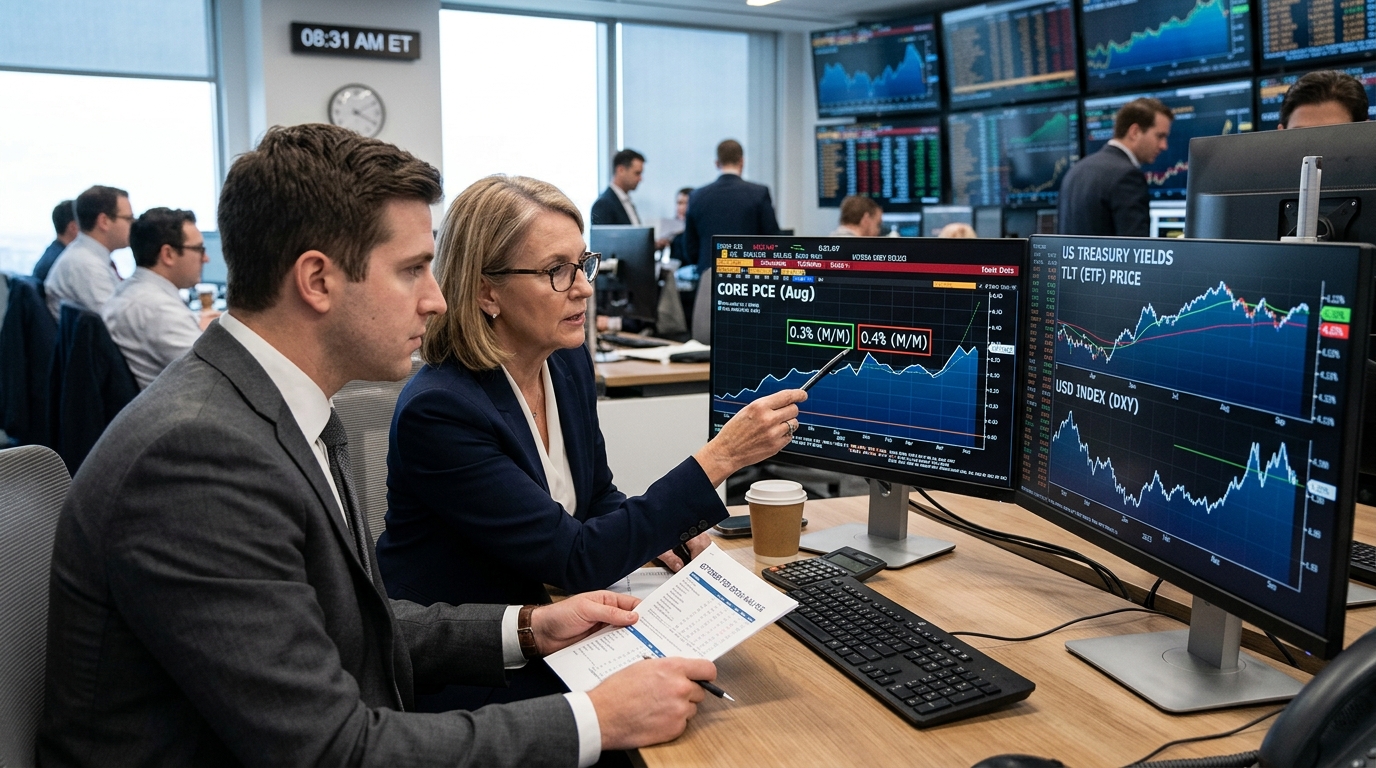
If anyone at the Federal Reserve is looking for evidence against another rate hike, they are unlikely to find it today. Forecasters broadly expect a 0.3% increase in core PCE for August. A 0.3% print likely leaves current October odds roughly where they are. A 0.4% reading could push hike probability higher, drive the dollar higher on DXY, and put fresh pressure on TLT and IEF, which have already been dismantled this month.
Softer, at 0.2%, is the scenario that offers bonds even a brief reprieve. Yields would pull back, SPY futures would catch a bid, and hike odds would compress, though probably not enough to flip the October base case to a hold.
What Warsh Has Already Told Us
The policy context matters here. Warsh acknowledged that “this summer’s inflation readings were better than expected,” but stressed they “do not tell me that underlying trends have meaningfully improved.” He reaffirmed that 2% PCE inflation remains the Fed’s firm objective and made it clear that with labor markets stable, growth resilient, and financial conditions not particularly restrictive, the burden remains on the inflation data.
There is also an important technical wrinkle in today’s release. BEA annual updates can revise the recent history of PCE inflation, sometimes materially. That can muddy the signal in the short run, especially if revisions pull prior core readings down or up in a way the market was not positioned for.
How Disciplined Traders Are Approaching This
The mistake most traders make on data days like today is reacting to the number rather than the market’s reaction to the number. Yields moving lower on an in-line 0.3% core reading would be a more bullish signal for TLT than the absolute level of the number itself. If bonds rally on confirmation-of-consensus data despite a 30-year around 5.55%, that tells you the market was short going into the release and is covering. That is a different trade entirely than a fundamental long.
Watch the first 15 minutes in IEF and TLT. A knee-jerk drop that reverses quickly is a very different story from a sustained move lower. The dollar’s reaction on DXY will confirm whether the bond move has institutional conviction behind it.
The Trader’s Lesson
Today is a reminder that the most important data releases are not the ones where the outcome is clear, but the ones where a single decimal point separates two completely different policy outcomes. Markets have been leaning toward additional tightening risk into late 2026 as yields have surged. Position size accordingly, and never let a pre-release opinion commit you to a trade you cannot exit.