Credit desks do not hedge. When they decline to warehouse risk, they are making a judgment. This week, that judgment landed squarely on the question equity markets have spent two years avoiding: what is a Nvidia GPU actually worth as loan collateral when the borrower has no operating history and no credit rating?
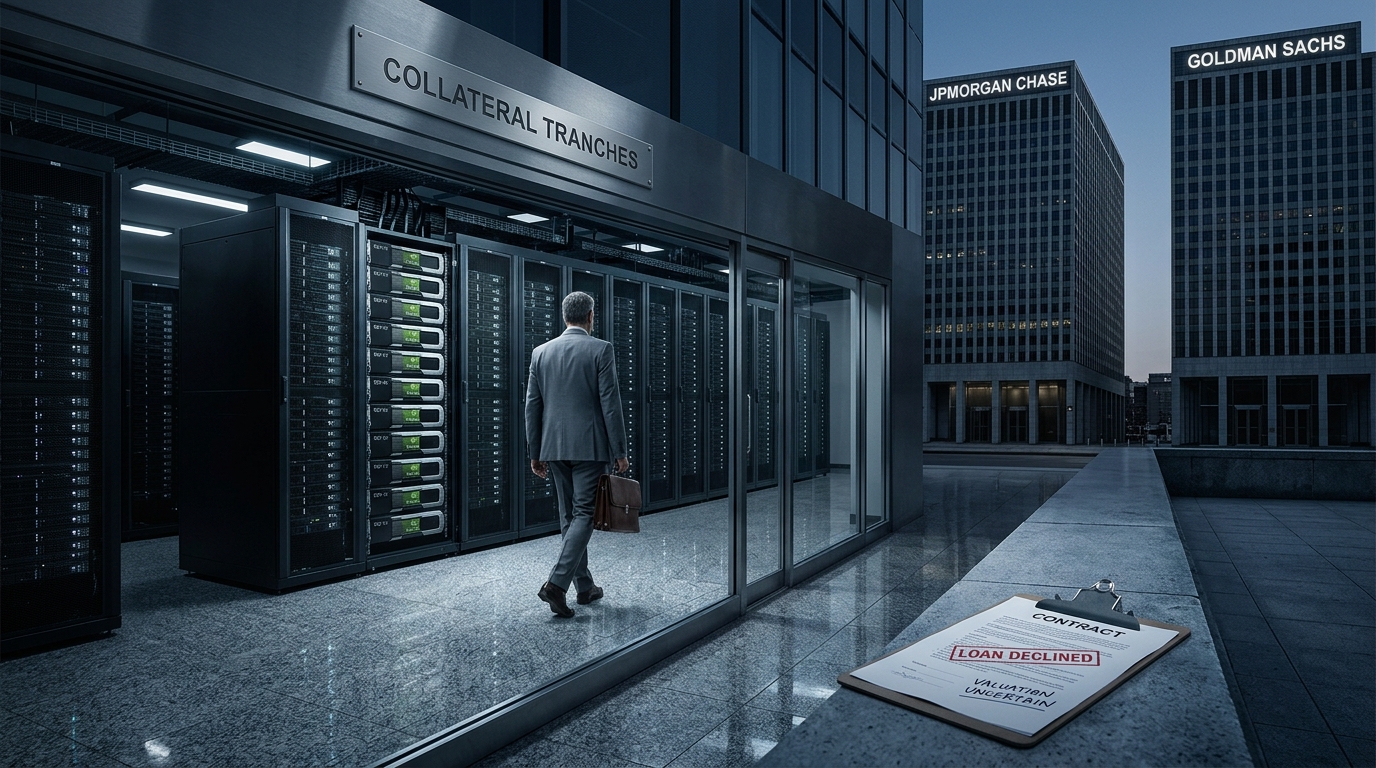
JPMorgan Chase and Goldman Sachs are underwriting only $1.3 billion of Volta Infrastructure Holdings’ roughly $5.0 billion leveraged loan, leaving the $3.7 billion slice earmarked for about 36,000 Nvidia GPUs to clear with investors on a best-efforts basis. Best-efforts means the banks pocket the arrangement fee and walk away from whatever does not sell. That is the structuring equivalent of refusing to shake hands on a deal.
The $1.3 billion the banks did underwrite is a first-lien term loan that cash-collateralizes a letter of credit backing a data-center lease with Bitdeer Technologies at a site in Norway, where Anthropic has been reported as the customer behind a six-year compute-capacity agreement with Volta. The lease, in other words, has a paying tenant and a hard asset underneath it. The GPU tranche has chips, a secondary market, and faith in AI demand. The banks chose the lease.
The relaunched deal prices at SOFR plus 625 to 650 basis points and an original issue discount of 97 to 98, after an initial pass at SOFR plus 500 failed to clear. That is the price of lending to a company founded in 2026 with no credit rating, even one with Anthropic reported as the customer. For context, CoreWeave completed its $8.5 billion DDTL 4.0 financing in March 2026 at SOFR plus 225 basis points, the first GPU-collateralized deal to receive an investment-grade rating from Moody’s. Volta’s spread is nearly three times wider.
Volta has a limited operating history and no corporate guarantees behind the debt, and it carries high leverage compared with peers such as CoreWeave. The company raised $300 million in equity earlier in 2026 at a $2.4 billion valuation, but next to a $5 billion loan, that equity cushion is thin. Because the deal carries no credit rating, collateralized loan obligations, a major source of demand in the leveraged loan market, would ordinarily be barred from participating. That means the GPU tranche depends entirely on private credit funds, hedge funds, and mutual funds willing to absorb chip-backed paper at yields around 11%.
GPUs can serve as loan collateral, but their value still depends on market demand, technological iteration, and secondary market liquidity. That depreciation risk is not theoretical. Nvidia’s chip roadmap moves fast enough that a three-year-old GPU is already a generation behind. Lenders holding a defaulted GPU loan do not get Nvidia’s current price. They get whatever the secondary market will bear on hardware that has been superseded.
The equity crowd, by contrast, has spent this year treating AI infrastructure spending as an unqualified positive for names like Nvidia and CoreWeave. What the Volta structure reveals is that the banks closest to the actual financing terms see a meaningful difference between a lease backed by a known tenant and a pile of depreciating silicon. That distinction has not shown up yet in how infrastructure stocks are priced.
Whether the $3.712 billion best-efforts portion fully sells at the revised terms will be the clearest read on how much appetite credit investors really have for financing the AI chip boom. If it clears oversubscribed, the bull case holds and the banks were simply being cautious. If it struggles, the credit market will have given a more honest answer than any earnings call has.
Stocks to Watch
- Nvidia (NVDA): The GPU collateral question is ultimately a question about Nvidia hardware’s residual value. If the Volta GPU tranche prices poorly, it signals that lenders are building in steeper depreciation assumptions for Nvidia chips, which has direct implications for how much new GPU-backed debt the market can absorb going forward.
- CoreWeave (CRWV): The comparison is explicit in the deal terms. CoreWeave borrowed at investment-grade spreads because it has operating history, rated debt, and long-term customer contracts. Volta’s blowout yield relative to CoreWeave’s is the market quantifying what it costs to lack those advantages. CoreWeave’s premium valuation rests partly on this creditworthiness gap remaining wide.
- Bitdeer (BTDR): Bitdeer signed a 16-year lease and services agreement with Volta expected to generate roughly $4.7 billion in contracted base-term revenue over the initial term. The $1.3 billion that JPMorgan and Goldman did underwrite is directly backstopping that lease. Bitdeer’s contracted revenue stream survives even if the GPU tranche has problems, making it arguably the cleanest beneficiary in this structure regardless of how the chip loan clears.