September 23, 2026
Bonus Content: Cisco Lost 4.5% on a Target Trim. That’s the Real Warning.
Hey,
I’m going to do something that may seem a little out of the “norm” these days…
I’m going to give you my #1 trade setup. For free.
It’s the same one I used to find winners like:
- 113% on GOOGL in under 2 hours.
- 240% on META in a single session.
I call it the “Opening Bell Breakout.”
It’s one simple setup I look for every morning. When it shows up…
I simply take the trade. And by 10 AM, I’m done.
I’ve put all the details on how it works in a simple, no-fluff guide.
No credit card required. No strings attached.
>> Get Your FREE “Opening Bell Breakouts” Trade Guide Here
This guide shows you the exact 15-minute window I trade, and how to spot the same setups the big funds are watching.
It’s yours for free.
Thomas Wood
P.S. This isn’t a 100-page novel. It’s a short, actionable guide you can read in about 10 minutes and put into action by tomorrow morning. Get it here.
Cisco Lost 4.5% on a Target Trim. That’s the Real Warning.
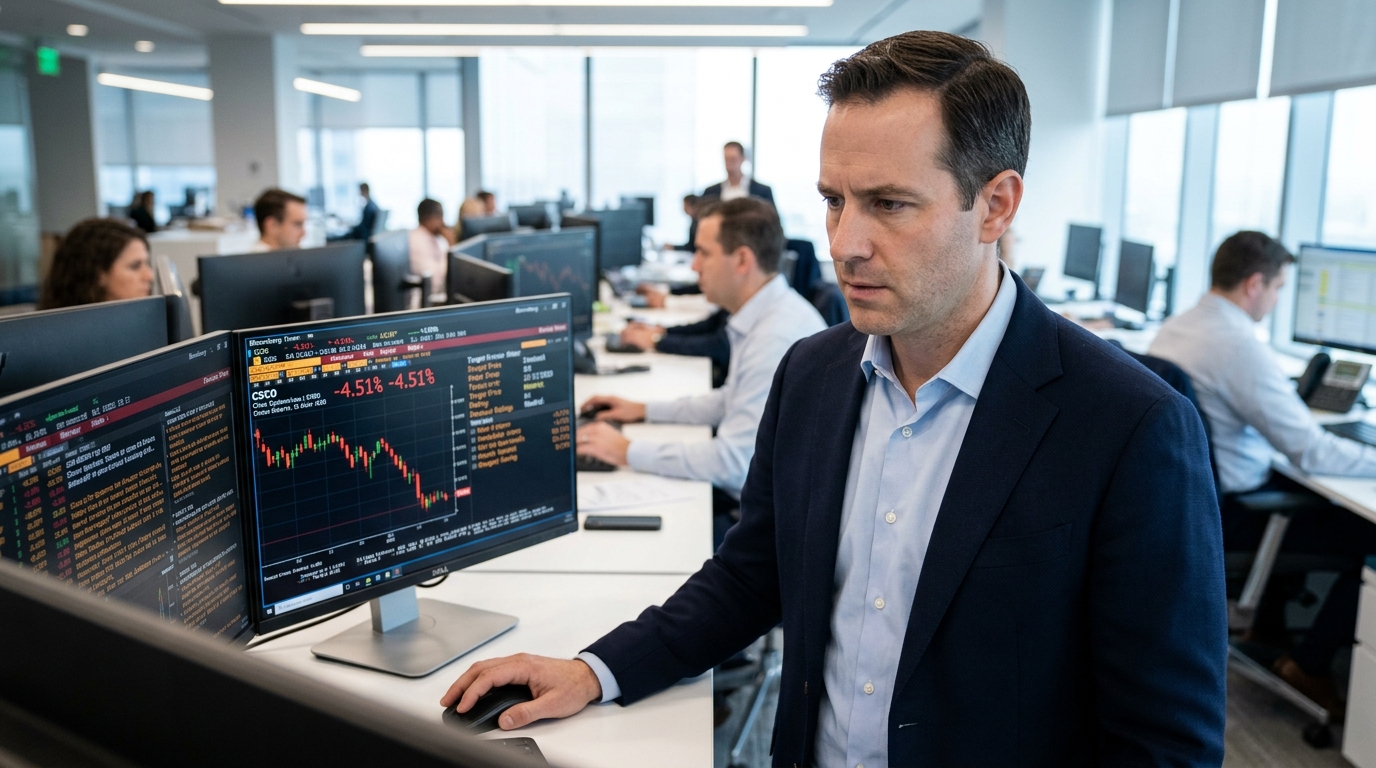
Tuesday’s session handed active traders one of those clarifying moments that only look obvious in hindsight. Cisco dropped about 4.5% after Piper Sandler cut its price target to $125 from $132, citing concerns that the stock’s valuation had run ahead of its growth prospects. The analyst, James Fish, kept a Neutral rating in place the entire time. No downgrade. No catastrophic earnings revision. Just a $7 trim on a target that still sat well above where the stock was trading.
That detail matters more than the price move itself.
Cisco shares came under pressure after Piper Sandler flagged concerns that the stock’s valuation had run ahead of its growth prospects, warning that investors may be underestimating the risk of Cisco’s growth slowing even as demand for its hardware remains strong. The business is not broken. Cisco’s Q4 fiscal 2026 results beat estimates, with revenue up 18% year over year. Cisco highlighted hyperscalers as a swing factor, saying it delivered about $4 billion of revenue from those customers in fiscal 2026 and expects about $7.5 billion in fiscal 2027. Those are not the numbers of a company in distress.
What Tuesday actually revealed is something disciplined traders understand well: the price of a stock that has run far and fast is held up partly by momentum and partly by the assumption that every future analyst note will confirm the bullish case. The stock hit a record high on June 4, 2026 and is up about 57% over the past 12 months. At that kind of altitude, the margin for doubt is razor thin.
Cisco closed Tuesday at $106.44, down 4.5%, while the Nasdaq Composite gained 0.45% on the same session. The divergence is worth sitting with. The broader market was not selling technology. It was selling Cisco specifically, because one firm voiced a worry about where multiples should sit when sector growth starts to level off.
The bigger picture still favors the bulls, with shares holding roughly 9% above the 200-day moving average. But the nearer-term situation has gotten shakier, with the stock now sitting beneath its 20-day, 50-day, and 100-day averages. That stack of moving averages now acts as overhead resistance. A stock has to reclaim those levels, not just recover to them, before the technical picture improves.
Cisco carries an overall Buy rating on Wall Street. That consensus is not disappearing. Deutsche Bank initiated coverage with a Buy rating and a $135 target on September 1, 2026, and HSBC downgraded the stock to Hold with a $120 target on August 14, 2026. The analyst community is split, which itself signals that the easy part of this trade, the period when every voice was pointing the same direction, is probably behind us.
For traders watching AI-adjacent hardware names broadly, Cisco’s Tuesday session is a stress test worth studying. Stocks in Arista Networks, Broadcom, and Juniper Networks all carry similar logic: years of underperformance, followed by explosive AI-era rerating, followed by valuations that depend heavily on growth continuing at an elevated pace. When one analyst at one firm suggests that growth ceiling may be appearing on the horizon, the stocks that have moved the most have the most to give back.
The lesson is not to avoid strong stocks. It is to know what is propping them up. The firm warned that investors may be underestimating the risk of Cisco’s growth slowing, and the market responded by wiping nearly five points off the stock in a single session. That is not a sign of strength in the thesis. That is a sign of how much of the current price requires the best-case outcome to stay intact. When that assumption wobbles even slightly, crowded positions exit fast, and liquidity does not wait for you to think it over.