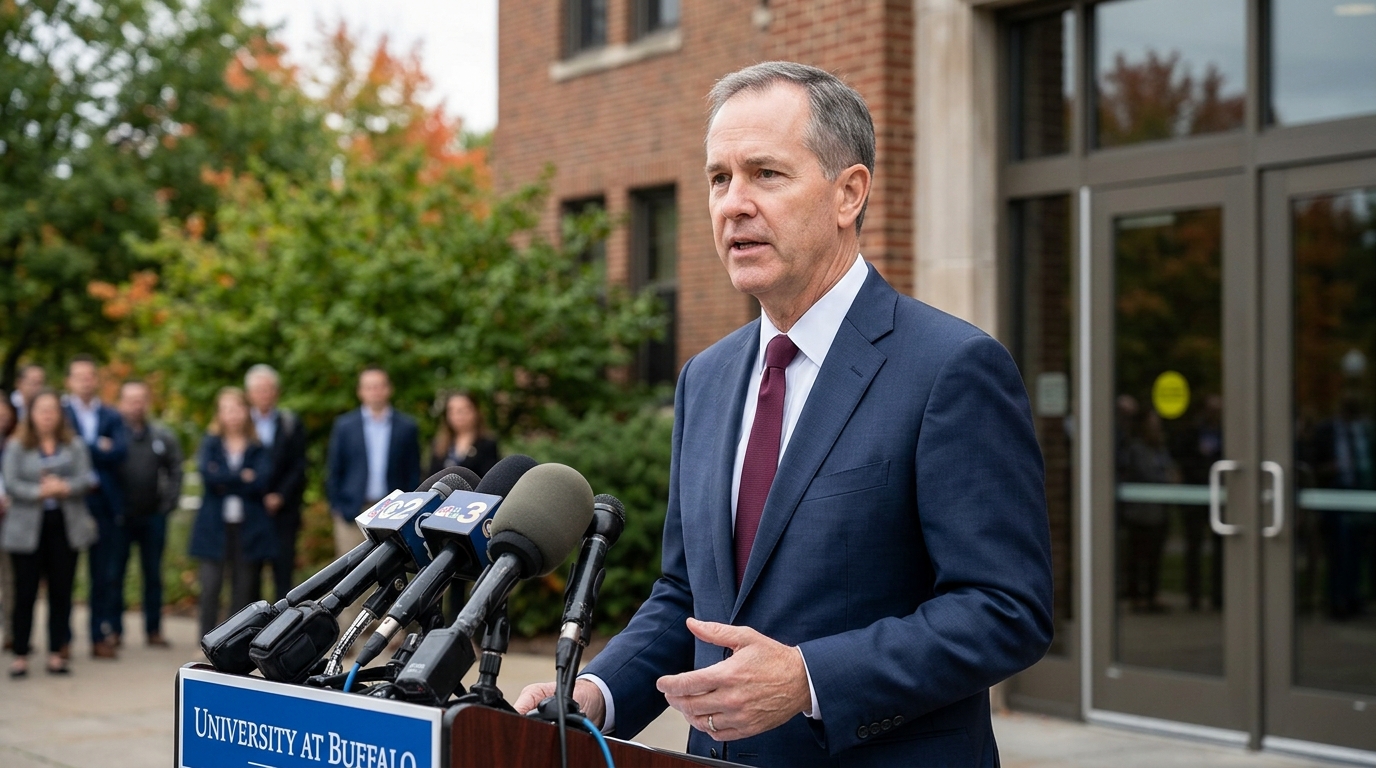
Two things happened in roughly 24 hours that changed the calculus for every rate-sensitive position on your screen. First, New York Fed President John Williams spoke at the University at Buffalo on September 29 and delivered what traders needed to hear: “no need for urgency.” Then on Wednesday, August core PCE printed at 3.0% year-over-year against a consensus of 3.3%. Together, the two data points cut October hike odds to roughly one-third by the close of Wednesday’s session.
The sequence matters more than either event alone.
What Happened
Speaking in Buffalo, Williams said that after raising rates in September, the Fed sees “no need for urgency” and that it has time to weigh the data before deciding when to hike again. He signaled one more rate hike is likely before the year ends, and to many in the market, that language leans more toward December than October.
The Fed lifted rates by a quarter point on September 16, its first hike since 2023, leaving the target range at 3.75% to 4.00%. Williams did not close the door on further tightening. He simply told traders they would have to wait for more data before the door opens again.
The August PCE report confirmed the signal. Core PCE rose 0.2% month-over-month, below the 0.3% forecast, with the annual rate at 3.0% versus a 3.3% forecast. Oxford Economics chief U.S. economist Michael Pearce said the downward revision mostly reflects improvements in how some categories are measured, and that Fed officials will have accounted for much of it already in their outlooks. The market moved anyway.
Why It Happened
Markets had been sitting at an uncomfortable 65% probability of an October hike just days before this data landed. That level of conviction is fragile. A market that moved this far on a speech that still backed another hike was never confident to begin with.
Williams holds a permanent vote on the FOMC and is part of what is considered the troika alongside the Fed chair and vice chair, so his words carry more weight than those of a rotating regional president. A single sentence from him delivered more clarity than a month of Fed minutes could. That is the lesson on positioning into major Fed communication events.
On an annual basis, core PCE held at 3.0% in August and came in below the 3.3% forecast, and the data briefly pushed Treasury yields lower before the broader rate back-up reasserted itself later in the session. The S&P 500 fell 0.3% and the Dow shed about 443 points while the Nasdaq gained 0.2%, with financials weighing on broader indices as yields remained elevated amid higher oil prices. The bond market exhaled; equities got no clean read.
What Comes Next
This morning’s data is the next pivot. Initial jobless claims are expected at 201,000, up from a prior 197,000. ISM Manufacturing PMI carries a 54.8 forecast, versus a prior reading of 54.6. A manufacturing number that firms above 55 with a strong prices paid component would remind traders that the inflation story is not finished, and that December is still live.
Friday is the bigger test. Economists have generally been looking for something around 90,000 to 95,000 new September payrolls, down from 162,000 in August, with unemployment holding at 4.1%. ADP’s Wednesday report, which came in at 90,000 private-sector jobs, showed base pay rising 3.2% year-over-year, with gross pay up 4.7%. Wage growth at that pace keeps the December hike on the table regardless of what October odds say today.
Kalshi traders currently put October hike odds in the low-to-mid 30% range. If Friday’s payroll number lands well above expectations, it will quickly test whether traders who priced in a hold this week were simply responding to Williams or actually rethinking the Fed’s path.
The Trader’s Lesson
When a central bank official near the top of the policy hierarchy speaks, the market does not wait to decide whether the message is fundamentally meaningful. It moves first. Wednesday was a case study in how expectations, not data alone, drive rate-sensitive instruments. Core PCE at 3.0% still sits a full percentage point above the Fed’s target. The October hold is a probability, not a verdict. Traders who anchor to yesterday’s moves and ignore today’s claims and Friday’s payrolls are treating a probability as a certainty. That is where mistakes get made.