October 10, 2026
Bonus Content: Slingshot and LeoLabs Are Cornering the LEO Safety Market
Hey,
I’m going to do something that may seem a little out of the “norm” these days…
I’m going to give you my #1 trade setup. For free.
It’s the same one I used to find winners like:
- 113% on GOOGL in under 2 hours.
- 240% on META in a single session.
I call it the “Opening Bell Breakout.”
It’s one simple setup I look for every morning. When it shows up…
I simply take the trade. And by 10 AM, I’m done.
I’ve put all the details on how it works in a simple, no-fluff guide.
No credit card required. No strings attached.
>> Get Your FREE “Opening Bell Breakouts” Trade Guide Here
This guide shows you the exact 15-minute window I trade, and how to spot the same setups the big funds are watching.
It’s yours for free.
Thomas Wood
P.S. This isn’t a 100-page novel. It’s a short, actionable guide you can read in about 10 minutes and put into action by tomorrow morning. Get it here.
Slingshot and LeoLabs Are Cornering the LEO Safety Market
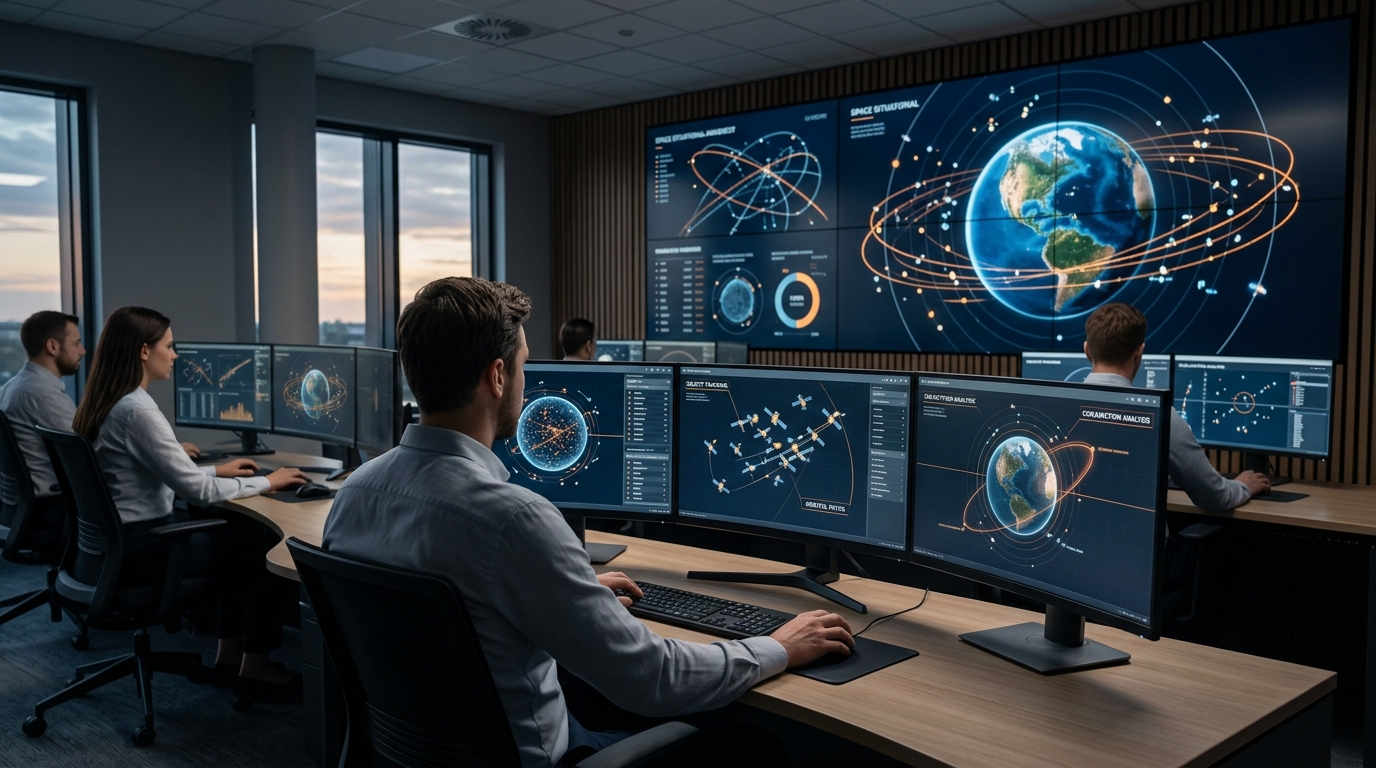
The most consequential contracts in the space industry right now are not going to rocket builders. They are going to the firms writing the software that keeps thousands of satellites from destroying each other.
Low Earth orbit has a congestion problem that is accelerating. With well over 10,000 active satellites now in orbit, the race for radio frequency spectrum is intensifying. Megaconstellations led by Starlink dominate the active satellite population, and the density in popular low-altitude shells is rising. That congestion increases close-approach and collision probabilities, yet no single binding global regime assigns right-of-way or mandates collision-avoidance coordination. That governance vacuum is exactly where the money is now flowing.
The contract flow into space traffic management firms has become impossible to ignore. LeoLabs closed 2025 with more than $60 million in total contract awards across U.S. and allied civil, defense, and commercial customers, and it said it achieved 186% year-over-year growth in U.S. government contracts. The company’s radar network is not a peripheral service. LeoLabs says its commercial catalog covers more than 25,000 objects in low Earth orbit.
Slingshot Aerospace is building an equally dominant position from a different angle. Slingshot won a Space Force contract worth almost $70 million in July 2026, which the company described as the largest single award in its history, to expand AI-driven mission rehearsal capabilities. That contract follows a string of smaller but strategically critical awards. Slingshot has said its Beacon platform includes about 90% of all satellites in low Earth orbit, giving it something closer to critical infrastructure than a vendor.
On September 29, NASA added another data point. NASA awarded Omitron a contract valued at approximately $23.5 million to provide orbital safety analysis services, structured as an indefinite-delivery contract with a five-year period of performance. Under the contract, Omitron will provide conjunction assessment screening services covering all NASA uncrewed spacecraft, and will also support human spaceflight activities to help operators identify and evaluate potential collision risks.
The frequency side of this problem is just as acute as the debris side. Demand for bandwidth is climbing, LEO networks can reconfigure quickly, and interference disputes between constellations are becoming a bigger operational risk. The ITU has also highlighted rising pressure on its space filing processes as operators push more satellite networks through the regulatory pipeline.
For traders, the practical read on all of this is straightforward: the infrastructure layer of LEO, the tracking, the avoidance software, the spectrum coordination platforms, is collecting government contract revenue while the constellation operators themselves face rising operating costs. Cost pressure on operators is revenue opportunity for the firms solving the underlying problem.
The Trader’s Lesson: When a sector generates a structural bottleneck that every operator must solve, the companies solving that bottleneck often compound revenue faster than the operators themselves. Space traffic management is today’s toll road. Identify who collects the toll before you bid up the satellites.