November 1, 2026
Bonus Content: Brazil’s Market Rout Had a Cause. Prediction Markets Missed It.
Dear Reader,
What the heck is going on at OpenAI?
The ChatGPT maker seems to make the news every day … And not for good reasons.
Their agents are attacking government websites around the world.
Leaking users’ data …
Even launching a cyberattack on a competitor.
No wonder Wall Street Veteran George Noble said …
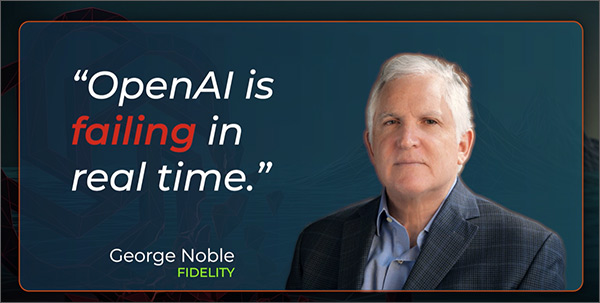
“OpenAI is failing in real time.”
Yet as terrifying as all this is …
It pales in comparison to what they are not revealing …
Medium referred to it as …
“Sam Altman’s $500 billion dollar bluff.”
So powerful that Bernstein Research, a firm with trillions under management, said …
“Sam Altman now has the power to crash the global economy … for a decade.”
This ticking time bomb could detonate as early as Dec. 18 around 4 p.m …
Don’t wait until it’s too late.
Click below to see how to protect yourself …
And potentially profit when the OpenAI truth bomb explodes.
Sincerely,
Eliza Lasky
Weiss Ratings
P.S. With the ludicrous amount of spending going into AI …
This crash has the potential to be the worst one we’ve ever seen.
Bigger than the Dot-Com bubble, the housing market collapse and the Great Depression …
It’s imperative you take the steps necessary to protect yourself.
Check out this video to learn how.
Brazil’s Market Rout Had a Cause. Prediction Markets Missed It.
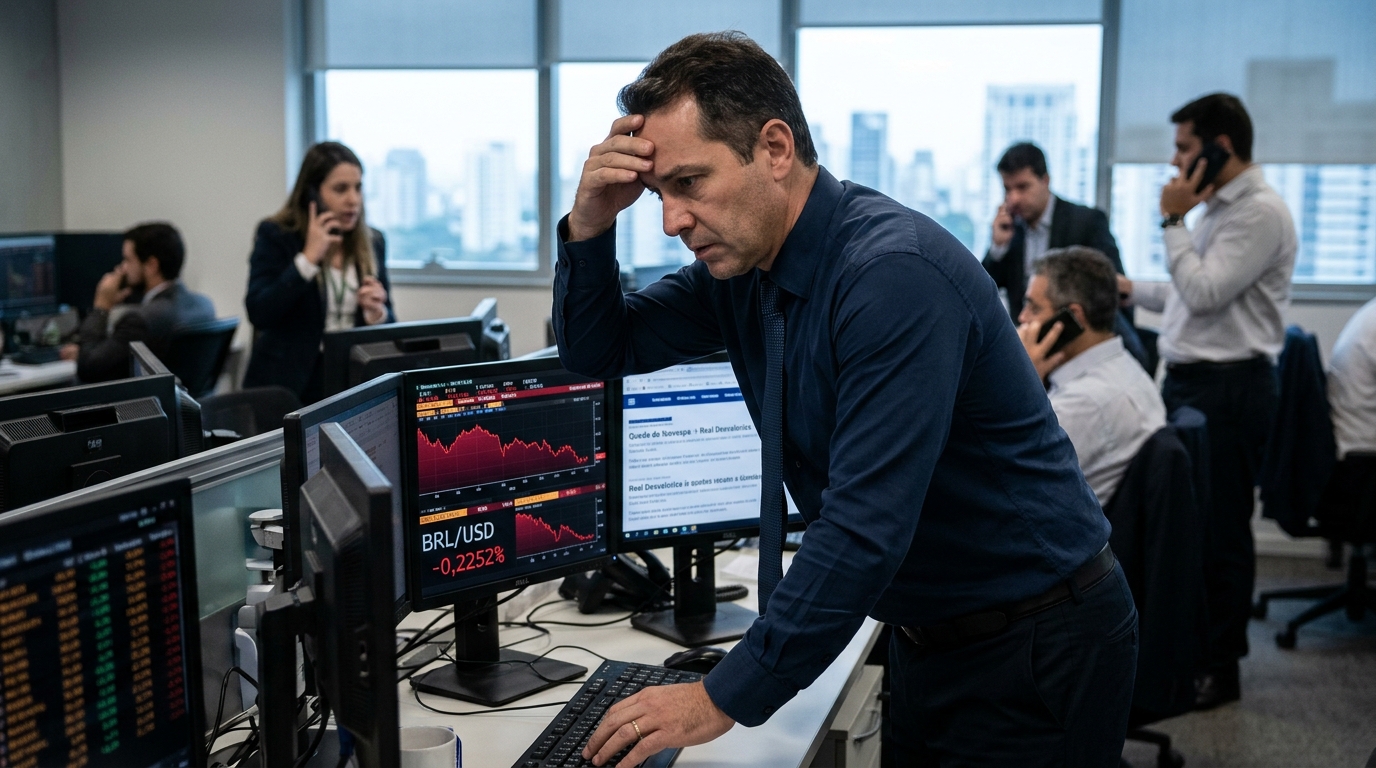
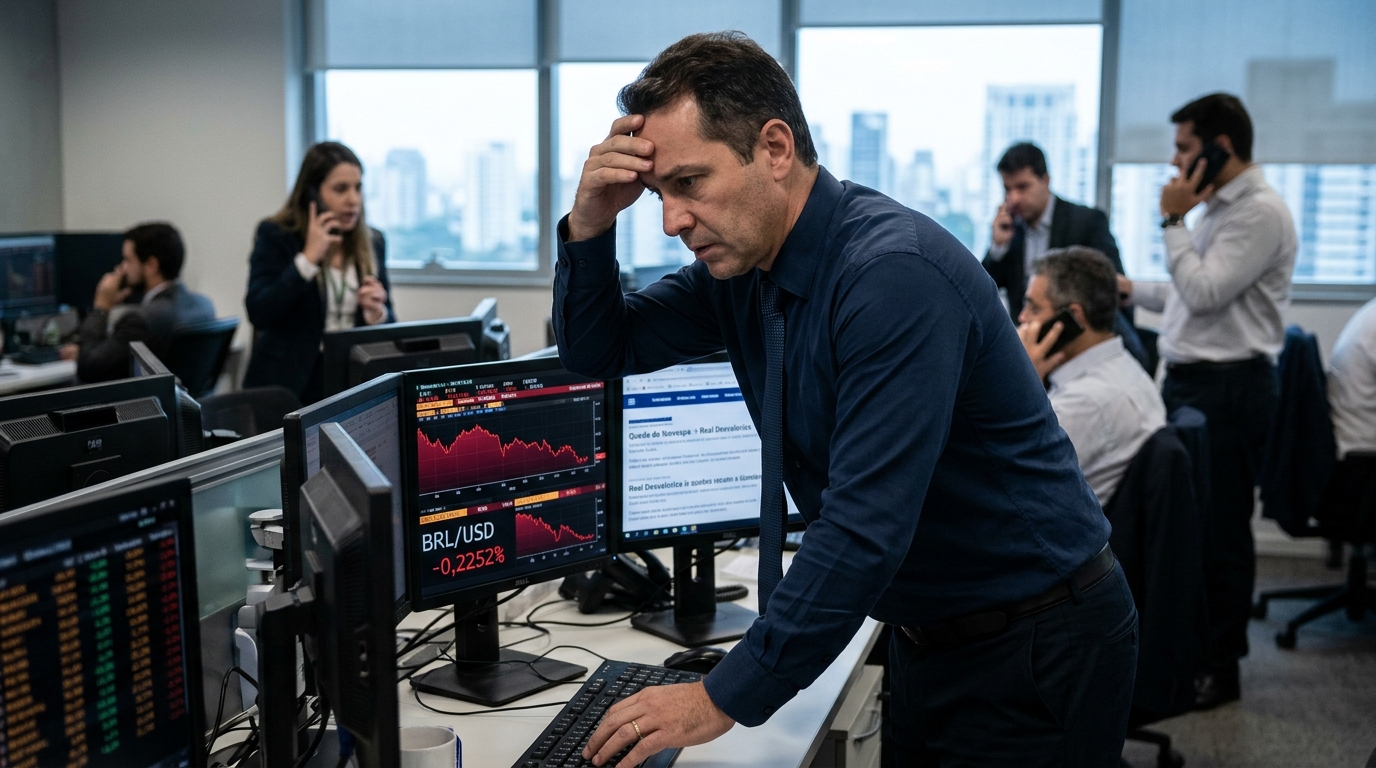
The vote was October 25. By Monday morning, the Ibovespa had fallen as much as 17% intraday, the real had fallen as much as 12% against the dollar, and B3 triggered its first circuit breaker since the COVID crash. EWZ, the U.S.-listed Brazil ETF that functions as the easiest expression of the country trade for most active managers, fell roughly 23% on the session. That is not noise. That is a positioning unwind of historic proportions, and understanding why it happened matters more than the raw figures.
The core problem was not Lula’s victory. It was that almost nobody positioned for it. Polymarket and Kalshi had Flávio Bolsonaro in the mid-70% to high-80% range going into election day. That is not a marginal error. That is a market that priced out a result that then occurred. Bolsonaro’s first-round win on October 5 had driven a 7.7% rise in the Ibovespa on expectations of greater fiscal discipline, and capital kept flowing in through the runoff. When the result flipped, every position built on that assumption had to be unwound simultaneously.
Now, a week later, the story has grown more complicated. Less than a week after Lula’s re-election, members of his government and Workers’ Party (PT) are drawing red lines around potential tougher spending measures, underscoring the challenge of slowing Brazil’s rising debt amid resistance from his political base. Institutional Relations Minister Jose Guimaraes told reporters two days after the victory that fiscal adjustment “was not discussed, is not being discussed, and certainly is not being discussed within our caucus.” The PT’s executive committee followed with a statement saying controls on spending should not come at the expense of the poor.
Brazil’s fiscal trajectory does not exist in isolation. MercadoLibre’s Brazil segment, the company’s largest market, shows how sovereign fiscal risk filters directly into regional consumer and fintech growth.
Finance Minister Dario Durigan is trying to hold the line. On October 27, he said the government is preparing a bill to steer the budget toward the center of its fiscal target. But Durigan gave no text or timetable, and described the measure as a complementary bill that would need an absolute majority in both houses of Congress. A signal, not a cut. Attention has also turned to who will lead Brazil’s finance ministry and whether that person will have the political capital to overcome internal resistance.
The comments from PT figures have fueled concerns among investors hoping for signs that Lula’s next administration will tackle national debt that has climbed about 11 percentage points during his presidency to reach about 82.9% of GDP. That debt level was visible before the vote. Prediction markets saw it and still priced Bolsonaro as an overwhelming favorite. The structural problem was never hidden; the political outcome just wasn’t considered seriously.
This is the trader’s lesson. Prediction markets are useful tools, but they carry a well-documented flaw in polarized, high-conviction political environments: they tend to amplify the prevailing institutional view rather than price genuine uncertainty. Prediction markets are prohibited in Brazil itself, so they may not accurately reflect local sentiment. Bolsonaro’s first-round lead shifted capital flows, which shifted confidence, which shifted odds, which shifted more capital. The feedback loop became self-reinforcing. By election night, the market had essentially stopped pricing a Lula win as a realistic scenario.
Before trading any political outcome as a near-certainty, ask who is on the other side of that bet and why. In Brazil’s case, the answer was roughly half the electorate. Any position sized to an 80% implied probability carries real 20% risk, and that risk was priced to zero in practice. The Ibovespa’s circuit breaker and a 12% move in the real are the cost of that confusion.
Brazil’s debt-to-GDP dynamic is not unique to emerging markets. Sovereign debt arithmetic compounds in ways that leave fixed-income investors with very few good exits once the feedback loop takes hold.