Let’s be real for a second.
While most traders are still squinting at lagging indicators and trying to “guess” where the next move is coming from…
My top AI trading engine is already light years ahead.
I’ve spent months and a small fortune making sure this engine outclasses any other trading tool you’ll find out there.
And right now, it’s flagging the kind of setups that typically stay hidden behind the velvet ropes of hedge funds and institutional banks.
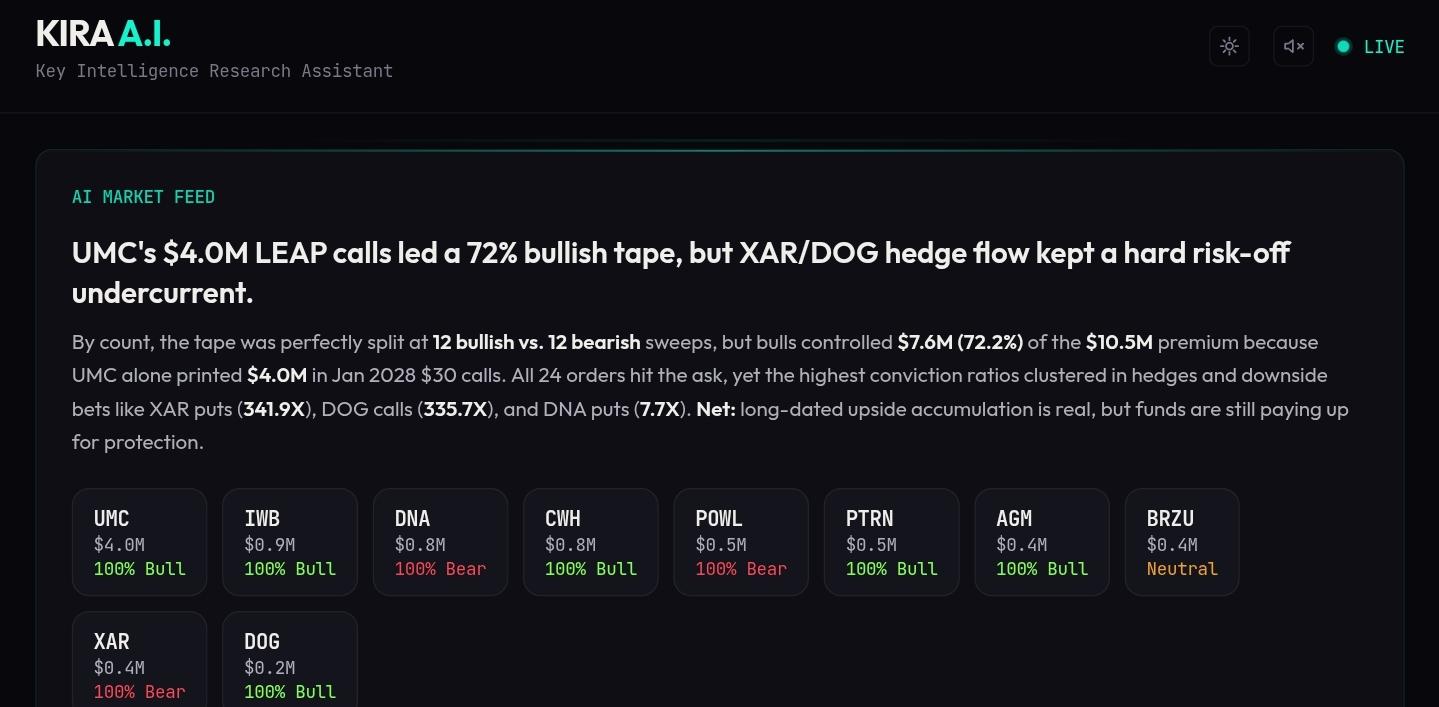
I’m talking about the ability to:
- Identify moves before they even register on a standard chart.
- Target “time-warp” returns that can compress years of gains into days.
- Choose your own risk so you never have to “bet the farm” to see results.
If you still haven’t grabbed your free access, I have to ask… What are you waiting for?
The market isn’t going to slow down for you. The robots running the show today certainly won’t wait for you to catch up.
You can keep doing things the hard way… dealing with the stress, the overthinking, and the emotional roller coaster…
Or you can let AI do the heavy lifting for you.
Claim your FREE access to the AI engine right here (No credit card required)
The proof is waiting inside.
Till the next trade,
Lance Ippolito
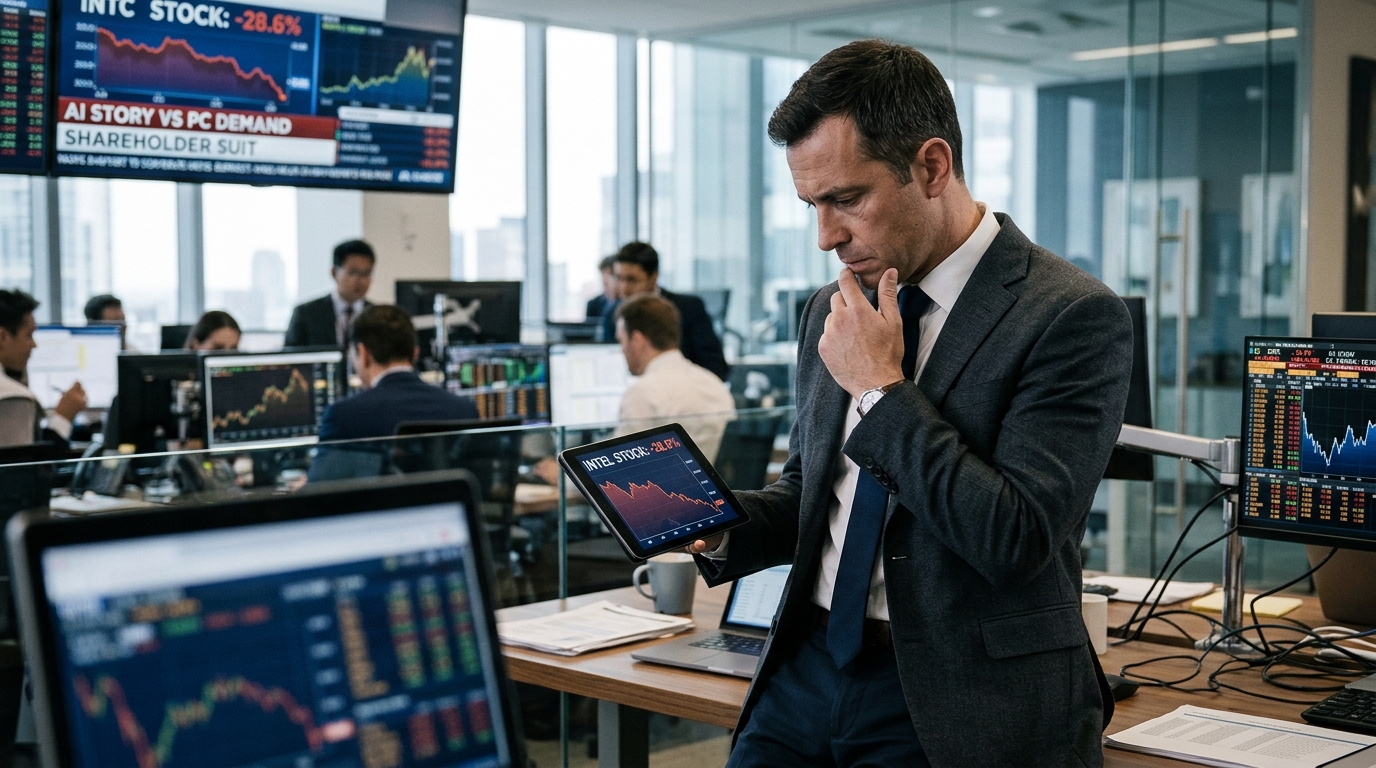
Intel’s PC Problem Was Bigger Than the AI Story
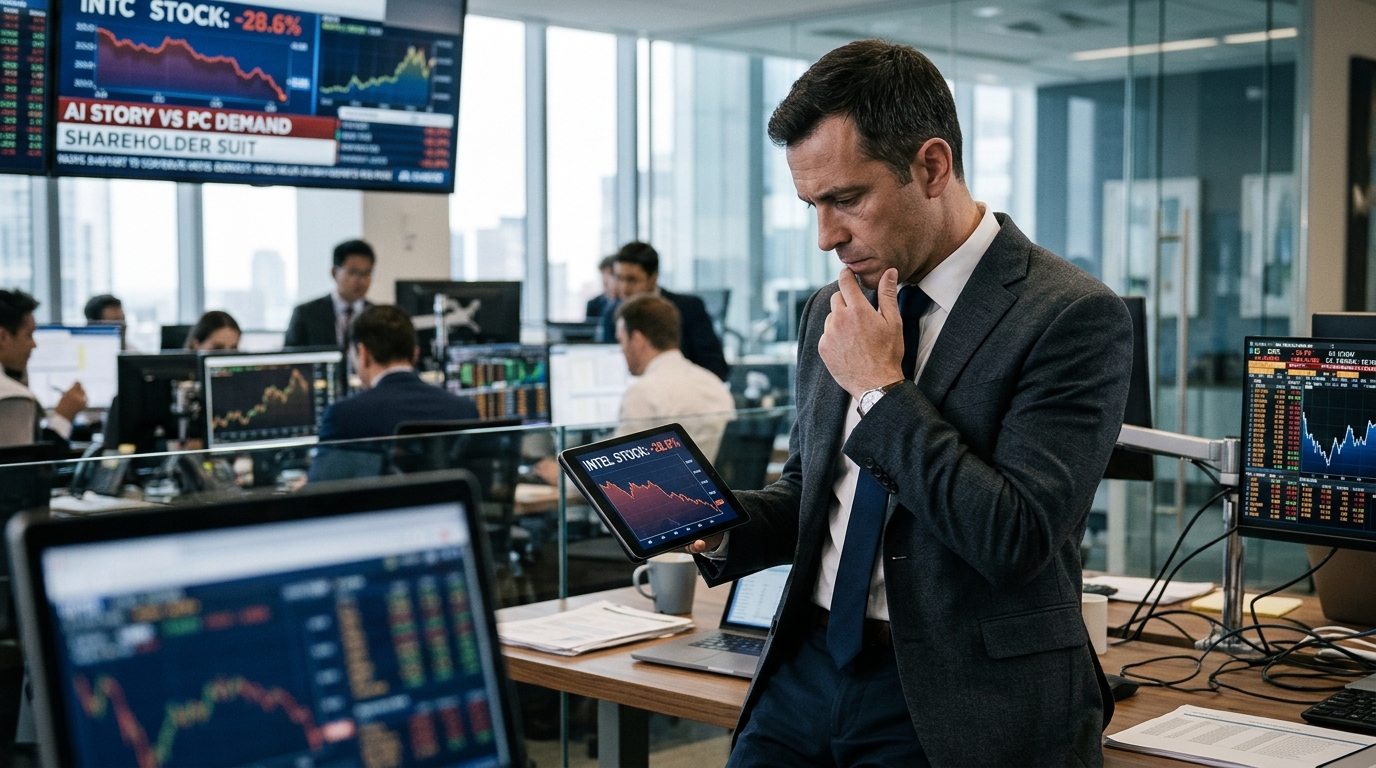
The lawsuit filed on November 13 against Intel is not really about what CEO Lip-Bu Tan said on an earnings call. It is about where traders were looking when the PC cycle quietly broke down.
Intel CEO Lip-Bu Tan and CFO David Zinsner are now facing a shareholder lawsuit alleging the chipmaker withheld information about weakening PC demand and excess inventory before its stock suffered a nearly 29% single-day plunge. The suit, led by the City of Southfield Fire and Police Retirement System, seeks unspecified damages for Intel shareholders between July 23, 2026, and October 29, 2026. INTC slipped roughly 3.8% in overnight trading after the filing surfaced.
What Happened
Shares of Intel fell 28.6% on October 30, wiping out about $140 billion of market value, one day after the company projected lower-than-expected fourth-quarter revenue and profit and forecast a prolonged slowdown in PC sales. Intel shares had already fallen from about $142 to around $60, erasing roughly $430 billion in value across the prior months as weak guidance, analyst downgrades, and demand concerns compounded.
The suit’s core allegation sharpens the picture. Shareholders said Intel had the motive and opportunity to defraud by raising capital in mid-August, halfway through its “disastrous” third quarter, when it sold stock at $95 per share, raising about $22.6 billion in net proceeds. That sale came as Intel looked to build out its chip contract manufacturing business, a key part of Lip-Bu Tan’s strategy. Selling at $95 while the PC business was quietly deteriorating is the specific sequence plaintiffs will need to prove was more than coincidence.
Why It Happened
The real trading lesson runs deeper than Intel’s legal calendar. Shareholders said Intel’s problems with PC sales and excess inventory outweighed data center construction and other benefits related to the artificial intelligence boom. That framing matters. The entire semiconductor sector has been priced around AI infrastructure spending for the better part of two years, and that focus created a blind spot. The conventional PC cycle, the kind Intel depends on far more than Nvidia or AMD’s data center divisions, rolled over without getting much attention from traders who were busy tracking GPU allocation.
Persistent increases in memory prices raised the retail cost of PCs, further dampening market demand even as chip executives pointed investors toward data center capacity expansions as the dominant story. When October’s guidance arrived, there was no cushion.
How Professionals Might View It
Disciplined traders ask which risks are being priced and which are being ignored. For most of 2026, the market priced Intel as a turnaround story anchored to foundry ambitions and AI-adjacent demand. The PC-exposed portion of the business received far less scrutiny. That asymmetry is exactly where large, sudden dislocations tend to originate. A 29% one-day move is rarely a surprise to everyone; it is usually a surprise to whoever held a thesis that explained away the warning signs.
The lawsuit itself is now a secondary overhang. The freshly filed securities class action, combined with an ongoing investigation by at least one other law firm, piled new legal risk onto a stock already pressured by a Bank of America price target cut. Legal overhangs rarely resolve quickly, and they tend to suppress institutional accumulation until the liability picture clarifies.
What Comes Next
Watch how AMD trades relative to Intel over the next few sessions. AMD tumbled about 8.8% in Friday’s broad semiconductor selloff, but its exposure to the PC cycle runs through the client computing segment rather than foundry commitments. If AMD shows relative strength on days when Intel continues to slide, it signals that the market is distinguishing between PC exposure and foundry risk rather than selling chips as a monolith. That divergence, if it develops, tells you something about where institutional money thinks the cycle bottom actually sits.
The Trader’s Lesson
Sector enthusiasm is not a hedge. When a dominant theme like AI infrastructure captures almost all of the attention, the parts of a business that do not fit that theme tend to get ignored until they cannot be. Intel’s PC division did not suddenly weaken in October. The inventory problem and demand softness built over quarters while the market focused elsewhere. Before sizing into any position in a company with multiple business segments, ask which segment the market is valuing and which one it is not. The one it is not watching is where the risk usually lives.