Qualcomm is not a smartphone company anymore, or at least it is working very hard to stop being one. The Amazon deal announced September 8, 2026 is the clearest proof yet that the pivot has real commercial weight behind it.
Qualcomm issued a warrant to an Amazon affiliate to acquire up to 25 million shares at $161.26 apiece, or about $4.03 billion at full exercise. That number gets the headlines. What matters more to traders is the mechanism underneath it.
The warrant vests in tranches tied to purchase milestones and expires September 3, 2036. In other words, Amazon does not simply receive equity. A tranche covering 3.75 million warrant shares vested at issuance because of initial purchase commitments, with more tranches vesting as Amazon places binding orders and makes actual purchases. Amazon’s incentive to buy is baked directly into the share structure. That is unusual, and it is meaningful.
The product scope is broader than a single chip. Beyond silicon, the companies are collaborating on optical connectivity solutions extending up to 1.6T, with Qualcomm’s SerDes and optical DSP technologies supporting high-bandwidth interconnects inside Amazon’s data center networks. Compute and connectivity together. That is the full infrastructure layer, not a one-product arrangement.
The focus is AI inference specifically. Inference is the phase where trained AI models actually respond to user requests, and it is quickly becoming the most compute-hungry part of the AI stack as generative AI applications scale. Qualcomm’s power-efficiency credentials from mobile give it a legitimate angle on inference workloads, where energy cost per query matters as much as raw throughput.
Qualcomm says it expects revenue from the relationship to begin in the December 2026 quarter, and its CFO said the company is already in production with Amazon. That timeline is the detail most coverage glossed over. This is not a framework agreement for chips that arrive in 2029. Revenue starts in three months.
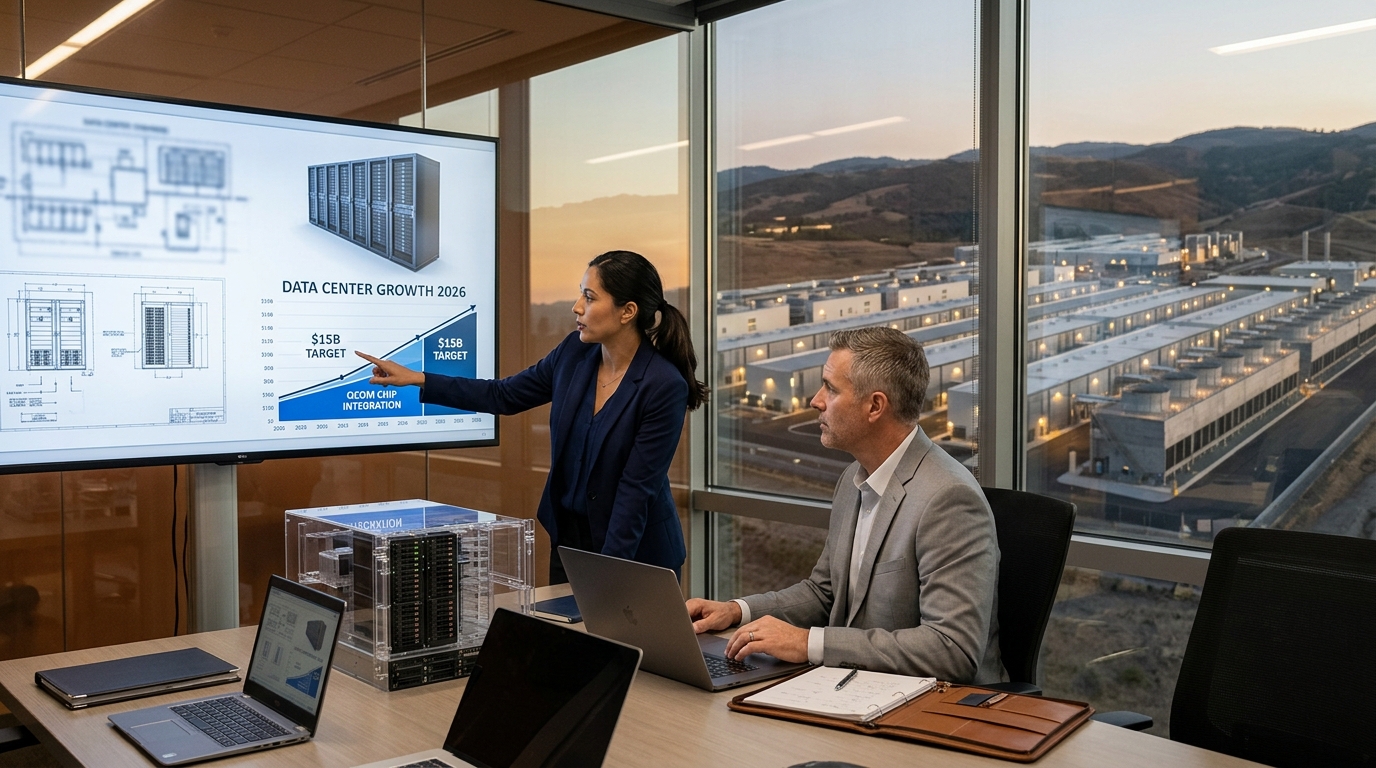
Following the June 24, 2026 Investor Day, Qualcomm raised its fiscal 2029 non-handset revenue target to $40 billion, with data center revenue alone targeted at more than $15 billion. The Amazon deal is the first anchor customer publicly attached to that target at scale. Under terms disclosed in Qualcomm’s September 8, 2026 Form 8-K, the warrant vests against Amazon payments for Qualcomm server chip products, technology, systems and manufacturing services, up to a $60 billion maximum during the term.
The risk is not the deal. It is everything else. Qualcomm faces significant challenges as it loses Apple’s modem business, which would be a meaningful hit to Qualcomm’s chip revenue from Apple as volumes shift to Apple’s in-house modem. Handset weakness and the Apple overhang are real drags that the Amazon announcement does not erase. A sell-side downgrade after the announcement is possible, but this note could not verify the specific claim that Barclays kept a sell rating after the deal.
The trade here is not about whether Qualcomm beats Nvidia. It is about whether a company generating little reported data center revenue today can credibly reach $5 billion by fiscal year 2027. Qualcomm has said it is targeting $5 billion in data center revenue by fiscal 2027. December’s first Amazon revenue print will be the earliest hard data point. Watch that number closely.