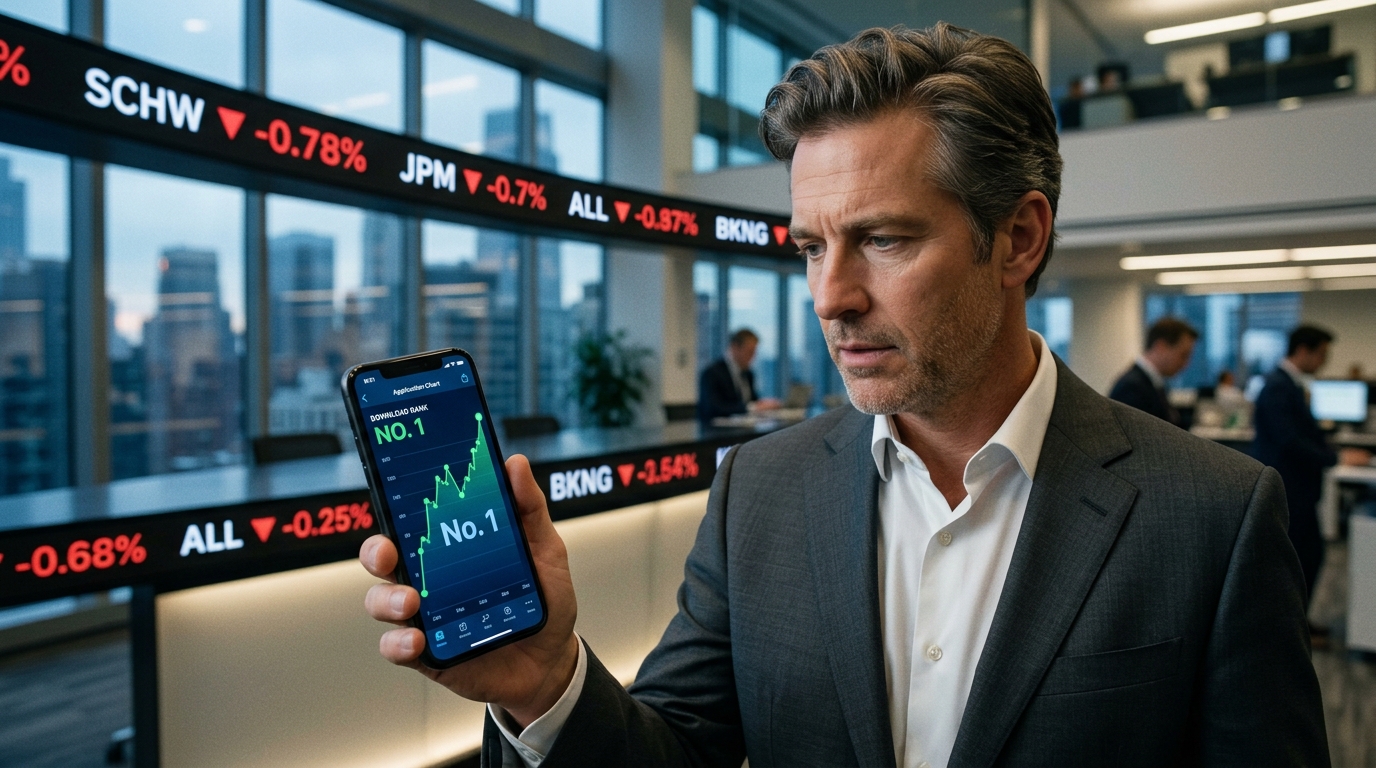
On Tuesday, a single app chart reshuffled $100 billion in implied market value before the closing bell. The S&P 500 Financials sector slid sharply, while the rest of the market sat roughly flat. Allstate fell 5.5% and Charles Schwab finished more than 6% lower. Expedia shed 3.7% and Booking Holdings dropped 3.9%. The proximate cause was a download chart: Meta’s Muse reached the No. 1 position on Apple’s US free iPhone chart on September 18, ten days after launch.
The investment committee question this morning is not whether Muse is impressive. It clearly is. The question is whether Tuesday’s move was a correct reset of durable earnings power, or whether professional investors just sold the headline.
The Bull Case for the Selloff
Much of the financial sector’s profitability, and travel booking’s margins, depends on consumer inertia. Most people don’t shop aggressively for better mortgage rates, cheaper car insurance, or lower airfares. Switching is annoying, comparison is tedious, and so people stay put and pay more than they need to. Muse is explicitly designed to remove that friction.
The application can complete digital tasks on behalf of users, enabling cross-platform operation by integrating with third-party services such as Gmail and OpenTable, and has already established partnerships with PayPal and fintech company Plaid. Investors are pricing in a future where AI agents continuously optimize personal finances: moving cash into higher-yielding accounts, canceling neglected memberships, renegotiating telecom plans, and automatically switching policies when cheaper rates appear.
Goldman Sachs’ “consumer inertia” risk equity basket fell 2.6% on Tuesday, its worst performance in nearly six months, with cumulative losses over the past six trading days exceeding 7%. That basket is not a sentiment gauge. It is Goldman’s explicit attempt to quantify businesses that live off switching costs.
Where the Thesis Gets Complicated
Three friction points deserve serious weight before an investment committee writes off Schwab or Booking as structurally impaired.
First, trust. An Oppenheimer survey of 1,500 US consumers found that only 8% would trust Meta with passwords for an AI agent, while 58% said they would not trust any AI agent with credentials at all. Less than two weeks before Muse launched, Meta agreed to an as much as $18 billion multistate settlement in a lawsuit over social media’s consumer harms. Asking those same consumers to hand Muse their bank login is a different proposition entirely.
Second, platform access. Axios reported that Amazon has blocked Meta’s Muse from perusing and buying products on its platform, demonstrating that big platforms can act as gatekeepers, deciding which agents get access to inventory and checkout. Booking and Expedia are not passive pipes. They control inventory relationships that an agent cannot simply route around.
Third, adoption speed versus market reality. Wayve Asset Management’s Chief Strategy Officer Rhys Williams put it plainly: Muse is undoubtedly a negative factor for these companies, but for now it still feels more like a novelty, and widespread proxy use is more likely a two-year story than a this-quarter one. While the immediate earnings impact on banking institutions remains ambiguous, Tuesday’s market movements reflect investors beginning to incorporate the possibility that AI agents could emerge as a competitive challenge, not a confirmed disruption.
Stocks to Watch
Charles Schwab (SCHW) took the sharpest hit among brokerages because its retail model relies on account inertia more than JPMorgan’s diversified revenue mix does. If agents begin automatically moving uninvested cash to higher-yield accounts, Schwab’s net interest margin is the first to feel it.
Allstate (ALL) is the clearest insurance target. With AI agents capable of silently scanning policy rates in real time and re-shopping coverage at renewal, insurers face the erosion of long-term policyholder retention and pricing power. The question is whether regulators accelerate or slow that process.
Booking Holdings (BKNG) and Expedia (EXPE) sit in a structurally awkward position: they are themselves aggregators built on the idea that comparison shopping is hard. An agent that does the comparison for free removes the reason most travelers visit them first.
Meta (META) is the obvious beneficiary, having jumped 11.43% to close at $741.25. Whether Muse converts download momentum into durable transaction revenue is the next earnings question worth watching.
The market’s one-day verdict may ultimately prove correct. But conviction that Muse dismantles Schwab’s or Booking’s business model within any investable time horizon requires a consumer trust shift that the data, so far, does not support.