September 25, 2026
Bonus Content: Russell 2000 Lost 3x More Than Mid-Caps Wednesday. Why It Matters.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear reader,
Michael Burry is the famous hedge fund manager who predicted the 2008 meltdown…
And made $100 million during that crash.
He’s now putting his own money on the line…
Betting that this AI company I just exposed in this shocking new interview will collapse.
He said:
“This bubble looks an awful lot like the dot-com bubble.” [This company] is doomed and hemorrhaging cash.”
After correctly predicting the last two major stock market meltdowns…
I have to say… I agree 100%.
I believe this company is about to go bust…
In a meltdown that will be 10 times bigger than Lehman Brothers.
So please click here to get the details because…
While most people are in the dark…
Some of the best investors on the planet…
Are already preparing for this coming AI meltdown.
For example, tech billionaire Peter Thiel recently sold his entire stake in Nvidia, worth about $100 million.
The giant investment firm SoftBank also sold all of its Nvidia holdings for $5.8 billion.
Ray Dalio’s hedge fund has also been dumping shares of some of the biggest AI players.
He recently cut his Nvidia position by 65%, Google by 52% and Meta by 48%.
And over the past few months Warren Buffett sold $177 billion worth of stocks…
And he’s now holding a record position in cash.
I highly recommend you avoid these hyped-up AI stocks…
Regards,
Jim Rickards
Russell 2000 Lost 3x More Than Mid-Caps Wednesday. Why It Matters.
Wednesday’s yield spike was blunt. On September 23, 2026, the 10-year Treasury yield jumped about 14 basis points to a 5.11% close, its highest close since 2007. TLT, the long-duration bond ETF, hit a record closing low of $80.46. And somewhere inside that bond wreckage, a more instructive story was playing out between two equity indexes that most traders treat as interchangeable.
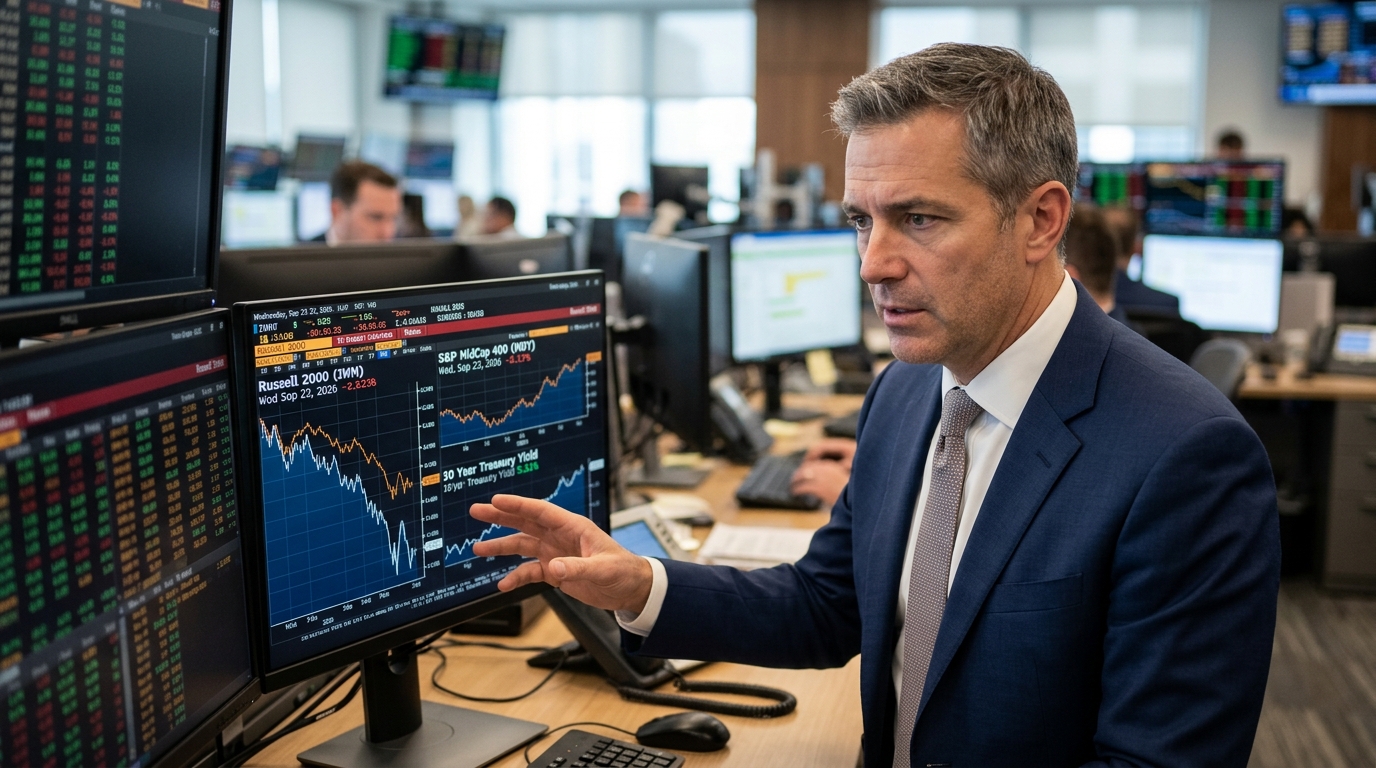
The Russell 2000 dropped about 1.8% on Wednesday. The S&P MidCap 400 fell about 0.6%. Same rate shock, three times the damage.
That divergence is not noise. It is structure.
Why the Russell Gets Hit Harder
The 10-year Treasury yield surged to a 5.11% close on Wednesday, a sharp one-day jump that followed hawkish Fed messaging and a hot read on U.S. business activity. Markets quickly adjusted rate expectations. Bank of America has remained among the more hawkish major banks, arguing the Fed may still deliver additional quarter-point hikes before year-end.
Small-cap companies absorb that adjustment faster than anyone else in the equity market. By widely cited estimates from sell-side and market-data work, roughly a third of Russell 2000 debt is tied to floating rates, versus only the mid-single digits for the S&P 500. When yields move, their interest expense can move with it, often within months. The S&P MidCap 400 sits in a different debt profile: companies in that index tend to be larger, more established, and more reliant on fixed-rate financing than the smallest names in the Russell.
At the start of September, the Russell 2000 was up around 20% year to date, beating both the S&P 500’s gain and the Nasdaq-100’s advance. But September has meant pain for small caps, with the Russell 2000 giving back a meaningful chunk of that lead. IWM recorded $3.3 billion in outflows last week, widely circulated market-flow data that was described as its second-largest weekly withdrawal of 2026 and third-largest in roughly nine years.
IWM vs. MDY as a Daily Rate Thermometer
The correlation data highlighted by CNBC on Thursday makes this concrete. IWM’s correlation to long-duration Treasuries has risen to 0.51, against 0.29 for SPY and about 0.1 for QQQ. In plain English, small caps have been trading far more like a rates instrument than large-cap tech has.
For traders, this creates a practical tool. On any session where yields are moving meaningfully, the IWM/MDY spread tells you how much of the equity market is genuinely trading off rate expectations versus how much is insulated by other factors. Wednesday’s roughly 1.2-point gap between the two indexes was not coincidence. It was the rate sensitivity premium being priced in real time.
The Russell 2000 has been more exposed than large-cap benchmarks to the latest rise in Treasury yields because small-cap companies tend to fund themselves with shorter-dated debt and bank credit. When the front end of the curve jumps, that funding gets more expensive in a hurry.
Where Professionals Are Focusing Next
Bank of America published a Russell 2000 screen on Wednesday identifying companies that rank well on factors that have historically held up better during hiking cycles. During Fed hiking cycles, BofA argued that quality stocks with strong balance sheets and consistent cash flow, and value stocks trading at lower valuations, have been the better performing groups in the Russell 2000.
The bank’s screen included Madison Square Garden Entertainment and Puerto Rico’s First BanCorp, companies it said have shown an ability to generate strong revenue, earnings, and cash flow despite the pressure of higher interest rates. BofA said Madison Square Garden should hold up better in a higher rate environment given that the entertainment company ranks highly on cash flow returns. First BanCorp benefits from the other side of the rate equation: as a bank, wider net interest margins from higher rates can expand earnings.
Market analyst Ed Yardeni has made the case that the latest yield jump is, in part, a function of an economy that is still running hot. One data point traders keyed on Wednesday was the S&P Global U.S. flash Composite PMI, which came in at 58.4. That matters for the Russell 2000 picture: growth-driven yield increases are categorically different from inflation-driven ones. Banks and cash-flow-positive industrials can handle the former. Leveraged, unprofitable small caps cannot.
The Trader’s Lesson
The default habit is to treat the Russell 2000 as a single risk-on or risk-off indicator. Wednesday showed that is too coarse. The IWM/MDY spread on a high-yield-volatility day is a sharper instrument, one that separates genuine rate sensitivity from broad equity sentiment. Before sizing any small-cap position in this environment, ask which side of that split the company sits on. The answer matters more than the index level does.