Market Snapshot
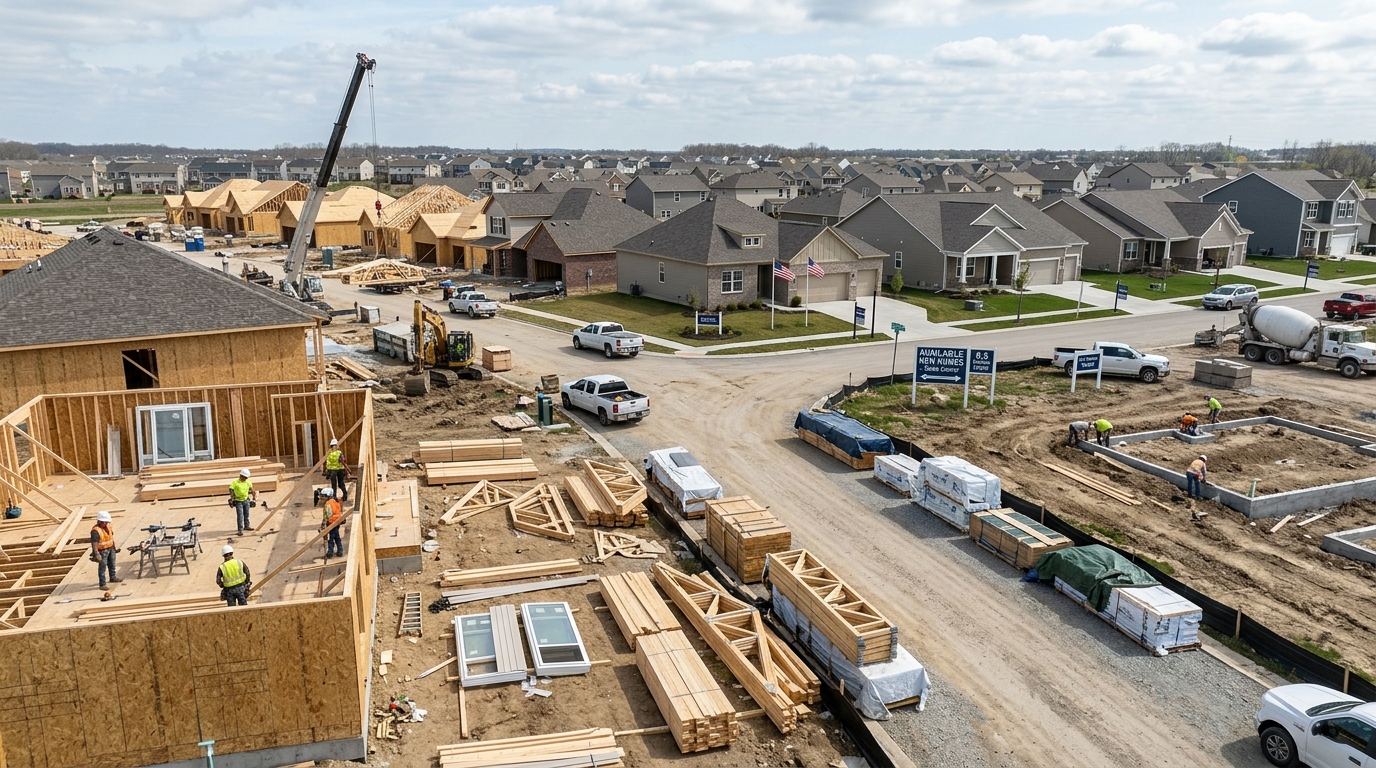
Housing is this morning’s dominant data point. The Census Bureau and HUD reported Thursday that new single-family home sales rose 6.4% in August to a seasonally adjusted annual rate of 684,000, the highest reading since December 2025 and well above the Reuters consensus of 615,000. The headline beat is real. The conditions behind it are not clean.
Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed at 7.03% as of September 24, up from 6.95% the prior week. The MBA’s contract rate hit 7.12% in the week ended September 18, its highest since May 2024, after the Federal Reserve delivered a 25-basis-point hike and Chair Kevin Warsh signaled further increases remain possible. Builders sold into a market where the cost of borrowing rose during the month they were closing contracts.
Stocks in Focus
LEN, KBH, DHI, PHM, TOL, NVR, XHB
- Lennar (LEN) reported Q3 results September 16: revenue fell 8.7% to $8.0 billion, GAAP EPS dropped to $1.19 from $2.29 a year earlier, and new orders declined 9% to 20,879 homes. Average selling price compressed to $372,000. Gross margin held at 15.8% sequentially, but the year-over-year story is deterioration. Lennar is maintaining volume by leaning on affordability-driven pricing.
- KB Home (KBH) reported Q3 on September 22: revenues of $1.30 billion, EPS of $1.05, deliveries down 19% year over year to 2,732 homes. Management described conditions as having weakened since the June call. Executive Chairman Jeff Mezger cited persistent inflation, higher fuel costs, the Fed’s rate hike, and geopolitical uncertainty. KBH’s build-to-order model accounted for nearly three-quarters of deliveries, a relative insulator against spec inventory risk.
- DHI, PHM, TOL, NVR have not yet reported fall quarters but inherit the same environment. D.R. Horton carries the broadest volume exposure; Toll Brothers’ luxury focus gives it more pricing insulation at the high end.
The August census data confirmed what both earnings calls described: 38% of builders cut prices in September, and 66% offered incentives, the highest incentive share since last December. The median new-home price fell 5.8% year over year to $393,700. The average sale price was $478,700. Volume is up. Revenue per door is down.
Sector Watch
The South accounted for roughly 66% of August new-home sales and rose 6.9% month over month. The Midwest surged 84.9% to 98,000 units, though that reading carries a wide statistical margin. The Northeast fell 36.1% and the West dropped 15.2%. Regional bifurcation matters for which builders are winning: those concentrated in the South and affordable Midwest are doing more of the work.
Supply remains the structural anchor. Inventory sat at 483,000 homes, unchanged from July, with 8.5 months of supply at the current sales pace. Anything above six months historically favors buyers over sellers. Builders are not yet in a position to ease incentives.
Catalyst Calendar
- Fed speakers this week: Watch for any rhetoric reinforcing or softening the September hike signal. Hawkish follow-through keeps mortgage rates elevated and limits builder pricing power.
- PHM and TOL earnings: Both report in coming weeks. The August census beat sets a marginally positive backdrop, but investors will focus on forward order trends and gross margin guidance, not the headline sales number.
- October housing starts and permits: The August permits reading came in at 1.394 million annualized, down 2.7% from July, signaling builders are not racing to break ground.
Technical Radar
XHB has been under pressure since Lennar’s double-miss on September 16. Watch the post-census reaction: if the 684,000 headline lifts the ETF but volume declines hold it below prior resistance, that divergence is informative. DHI and LEN are the heaviest weights; KBH’s build-to-order mix and smaller footprint make it the cleaner read on affordability-driven demand.
Risk Radar
- Rates stay above 7%: The MBA reported new-home mortgage applications fell to their 2026 low in August even as sales beat. Applications lead closings. A sustained rate environment above 7% narrows the buyer pool faster than price cuts can offset it.
- Supply overhang: 8.5 months of supply is still well above the four-to-six-month range associated with a balanced market. Builders cutting prices to move that inventory are compressing margins heading into Q4 and fiscal 2027.
- Builder confidence at a one-year low: NAHB sentiment dropped to its weakest point since September 2025. The forward-looking sales outlook component weakened, which tends to precede order softness by one to two quarters.
The Cheat Sheet
- Top Market Theme: Builders bought an eight-month sales high with an 5.8% price cut and record incentive use; the volume number is real, the margin math is not favorable.
- Stock to Watch: KBH. Its Q3 already reset expectations low, its build-to-order model reduces spec risk, and the August census beat gives the stock a near-term catalyst while peers face similar headwinds.
- Sector to Watch: Homebuilders (XHB). The census beat is a positive signal for the group, but the durability question, specifically whether buyers stay active with rates above 7%, is what the market will price today.
- Biggest Risk: Mortgage rates hold above 7% through October, MBA applications confirm August’s weakness was not a one-month blip, and Q4 order guidance from DHI and PHM disappoints.
- Biggest Opportunity: If Thursday’s 684,000 release triggers a sentiment shift in XHB and homebuilder names that have already discounted significant margin deterioration, the entry window before fall earnings could be narrow.
- One Thing to Remember: Sales at an eight-month high with a five-year-high incentive rate is not recovery; it is the cost of maintaining volume in a rate-constrained market. Watch margins, not headlines.