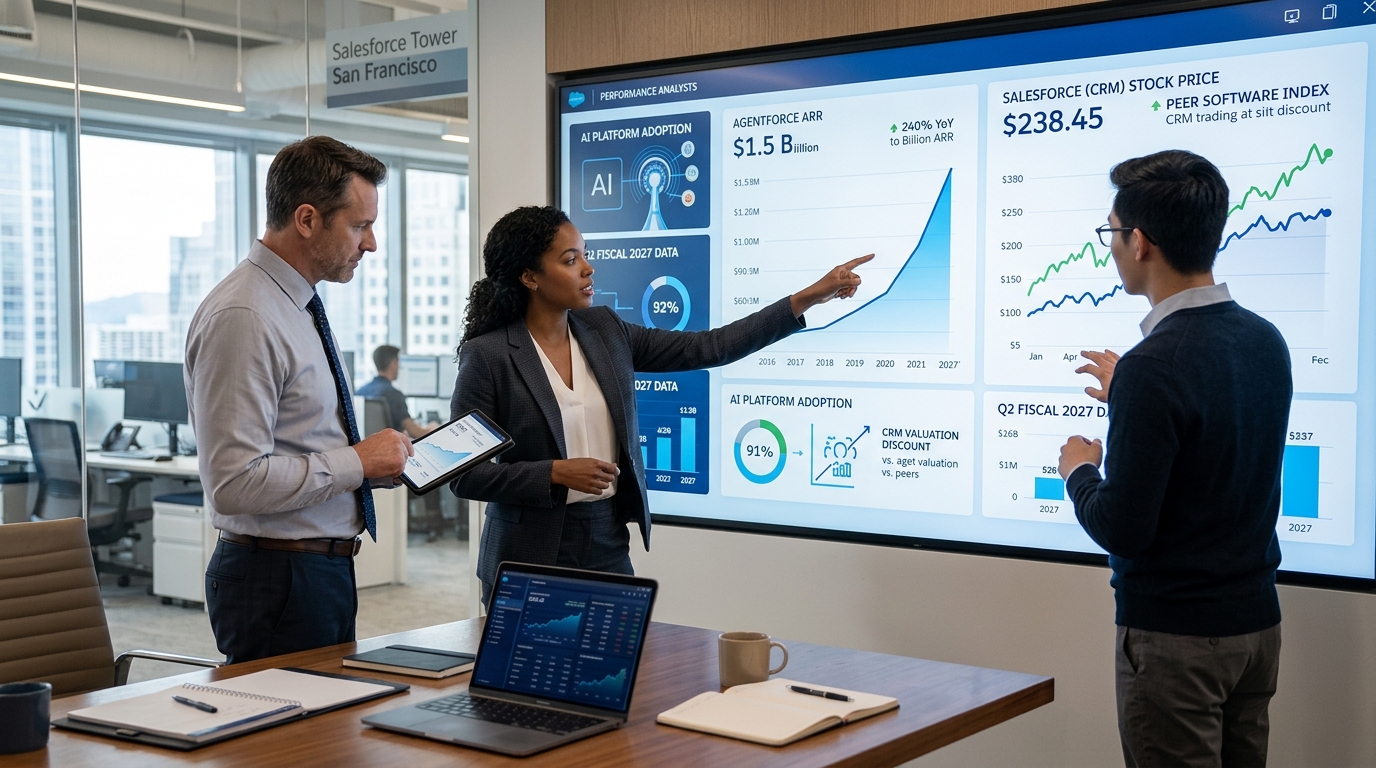
For most of 2026, Salesforce carried a label that made institutional investors nervous: a legacy CRM player vulnerable to AI disruption. That label is now harder to defend. The company’s Agentforce platform accelerated to more than $1.5 billion in annual recurring revenue by Q2 of its fiscal 2027, with triple-digit year-over-year growth. The stock, still trading around $238, has not caught up.
The Business
Salesforce is the world’s largest customer relationship management software company, with fiscal 2026 revenue of $41.5 billion. The business runs on long-term subscription contracts: total remaining performance obligation as of January 31, 2026 was approximately $72.4 billion, up 14% year-over-year, while current RPO hit $35.1 billion, up 16%. That is a large pool of contracted revenue already in the system.
Agentforce, the autonomous AI platform handling customer service, sales workflows, and enterprise tasks, is the growth engine. Q2 revenue rose 11% year-over-year to $11.35 billion; non-GAAP diluted EPS of $5.90 beat consensus by roughly 80%; free cash flow surged 81% year-over-year to $1.1 billion; and Salesforce raised its FY2027 revenue guidance to $46.1 billion to $46.4 billion while maintaining a non-GAAP operating margin target of 34.3%.
Why Wall Street Is Paying Attention
Q2 revenue grew 11% year-over-year to $11.35 billion, Agentforce ARR exceeded $1.5 billion and was up more than 240% year-over-year, and total RPO growth remained in the mid-teens, signaling strengthening enterprise demand. Those are not pilot numbers. The crossing of the $1.5 billion ARR level matters to institutional investors not as a ceiling but as a floor: it signals customers are paying for results, not merely piloting.
At Dreamforce last week, Salesforce unveiled AIforce and Koa, two new products designed to extend the agentic platform deeper into enterprise workflows. Those launches reinforce Salesforce’s AI push and support management’s long-term revenue ambitions. CEO Marc Benioff also highlighted the Claudeforce partnership with Anthropic, positioning AI as complementary to CRM rather than a replacement threat.
What’s Driving the Opportunity
The valuation gap is the most immediate argument. CRM trades at a discount to many large-cap enterprise software peers, even as the company is showing signs of organic re-acceleration. The Wall Street consensus remains constructive, with a median 12-month price target around $280, which represents roughly 18% upside from current levels. With Q3 earnings expected in early December 2026 and management guiding Q3 revenue to $11.42 billion to $11.50 billion, the next catalyst is close.
The capital return program is also unusually aggressive for a growth software company. In fiscal 2026, Salesforce repurchased approximately 50 million shares for approximately $12.7 billion, up from 30 million shares for $7.8 billion the prior year. In Q1 fiscal 2027, the company entered into a $25 billion accelerated share repurchase, with Salesforce disclosing that it funded the ASR with a $25 billion debt issuance. Benioff has called current prices low enough to justify buying back stock aggressively.
What Could Go Wrong
The biggest risk is that Agentforce adoption and organic growth fail to scale quickly enough to offset pressure on the traditional seat-based software model. If enterprises use AI agents to replace human CRM users rather than expand their Salesforce footprint, the revenue per customer math gets complicated. The Dreamforce conference also coincided with widely discussed service disruptions, a reminder that execution at scale is not guaranteed. And the Informatica integration, completed in November 2025 for approximately $9.6 billion, is still being absorbed.
The Bottom Line
Salesforce is a strong example in enterprise software of AI moving from existential threat to active revenue driver. Agentforce appears to be supporting Salesforce’s broader AI monetization push. The Q2 results showed a company accelerating, not defending: faster RPO growth, surging free cash flow, and Agentforce ARR up more than 240% year-over-year. With $280 as the median analyst target, CRM today remains a concrete disconnect between a company’s trajectory and its stock price. The early-December earnings report will either confirm the acceleration or test investors’ patience further. Either way, the AI transformation at Salesforce is no longer a promise, it is showing up in the numbers.