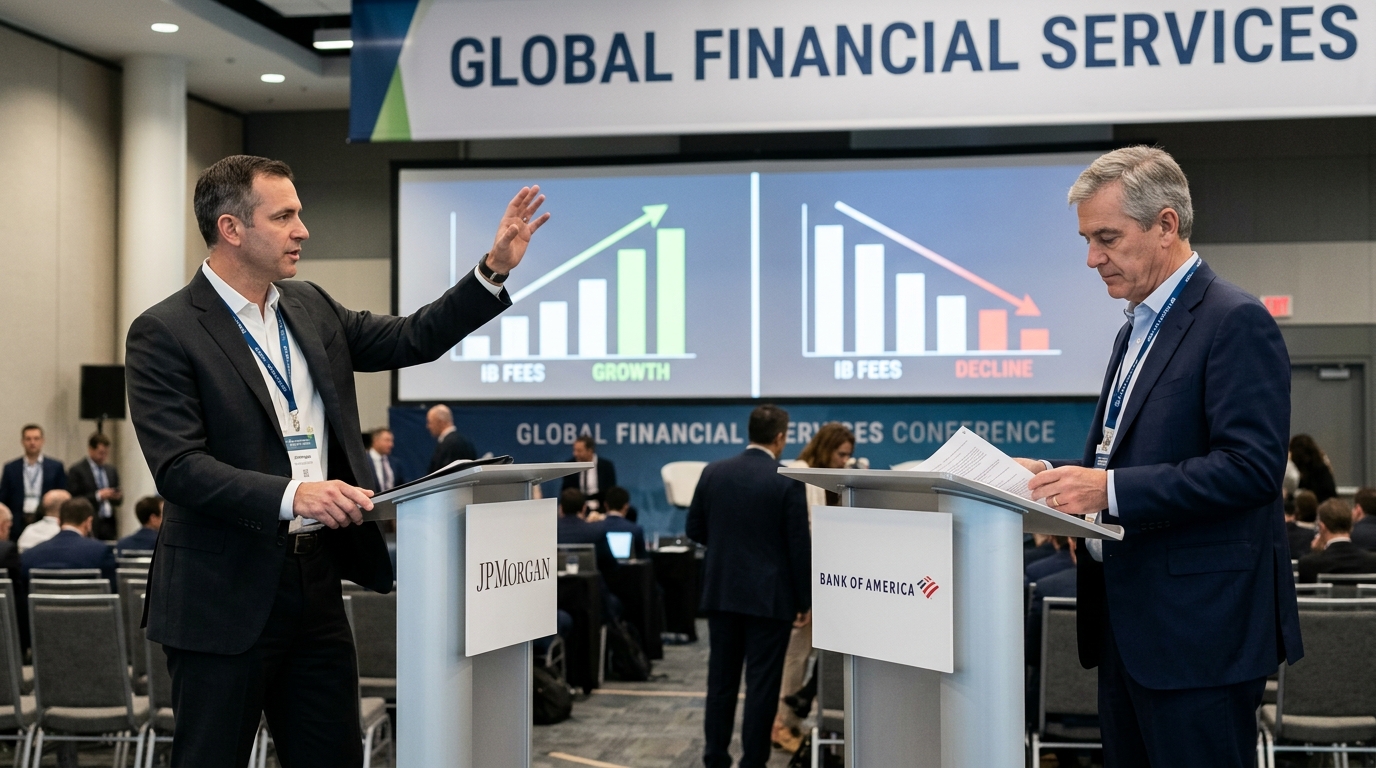
When Bank of America’s CEO stood at the Barclays Global Financial Services Conference in mid-September and warned that investment banking fees were tracking toward a 10% or more decline in Q3, bank stocks sold off immediately. Then JPMorgan’s co-President Doug Petno walked to the same podium and said the opposite.
Speaking at the same conference, Petno said investment banking fees and markets revenue were expected to be up a mid-to-high-teens percentage in the third quarter. The stock recovered. That divergence is not a small detail; it is the entire investment case right now.
Why This Stock Now
The investment banking leader is expected to announce its third-quarter 2026 earnings before the market opens on Tuesday, Oct. 13, with results scheduled around 7:00 a.m. ET and the conference call at 8:30 a.m. ET. Ahead of the event, consensus calls for JPMorgan to earn $5.84 per share. The bank has beaten consensus EPS in each of its last four quarterly reports, which sets a high bar but also a useful pattern.
The Business
JPMorgan is not competing to be the largest bank; it already is. The firm held about $5.015 trillion in assets and about $374.6 billion in stockholders’ equity as of June 30, 2026. That scale matters because it lets JPMorgan absorb technology investment that smaller rivals cannot match without sacrificing returns. Its deposit base, trading desks, and investment bank spread those costs across a revenue pool that is simply larger than any competitor’s.
Why Wall Street Is Paying Attention
The Q2 report was hard to ignore. JPMorgan posted net income of $21.2 billion with diluted earnings per share of $7.70. The quarter included a large gain related to Visa shares, and on a basis excluding significant items the firm reported net income of $16.9 billion and EPS of $6.14. Firmwide managed revenue was about $58.0 billion.
Trading was the standout. In second-quarter 2026 results, Equity Markets revenue rose 86% to about $6.03 billion and Fixed Income Markets revenue rose 6% to about $6.05 billion. Investment banking fees were up 30% year over year in the quarter, while total investment banking revenue rose more sharply because of net gains on equity investments.
That performance was not a one-quarter anomaly, according to management’s own guidance. Global M&A activity remained substantial in the first half of 2026, with several data providers putting the value of announced transactions at roughly $2.8 trillion to $3.2 trillion.
What’s Driving the Opportunity
JPMorgan expects investment banking fees and markets revenue to rise by a mid-to-high-teens percentage in the third quarter, assuming no major market disruption. Petno said JPMorgan entered the quarter with a strong pipeline and is seeing broad-based strength, particularly in M&A, as management and boards show greater confidence in pursuing transactions.
The quarterly dividend also rose. In late June, the company said its board intends to increase the quarterly common stock dividend to $1.65 a share from $1.50 for the third quarter of 2026, subject to the usual quarterly declaration. That is not a headline catalyst, but it signals a management team that believes the earnings base is durable enough to keep expanding capital returns while still investing heavily in technology.
JPMorgan trades at about 14.3x trailing earnings. That premium is not small. It demands that the growth story keeps delivering, which is precisely what Oct. 13 will test.
What Could Go Wrong
The principal risk is that the strength JPMorgan is forecasting is highly dependent on market activity remaining elevated. Even a strong quarter can look less impressive if volatility cools, underwriting windows shut, or large deals slip to the right.
Rising 10-year Treasury yields at the highest levels in roughly 24 years add another complication. Higher rates can help net interest income but also slow dealmaking as borrowing costs rise and acquirers hesitate. If corporate confidence fades between now and the Oct. 13 report, the Q3 numbers may still look strong while the guidance for Q4 does not.
The Bottom Line
JPMorgan enters Q3 earnings as the clearest counterargument to the broader concern that Wall Street’s deal boom is fading. Its own co-President said so publicly, in contrast to a direct competitor, in mid-September. The valuation is not cheap, but the earnings machine has earned its premium. October 13 tells us whether that momentum is still accelerating or beginning to flatten.