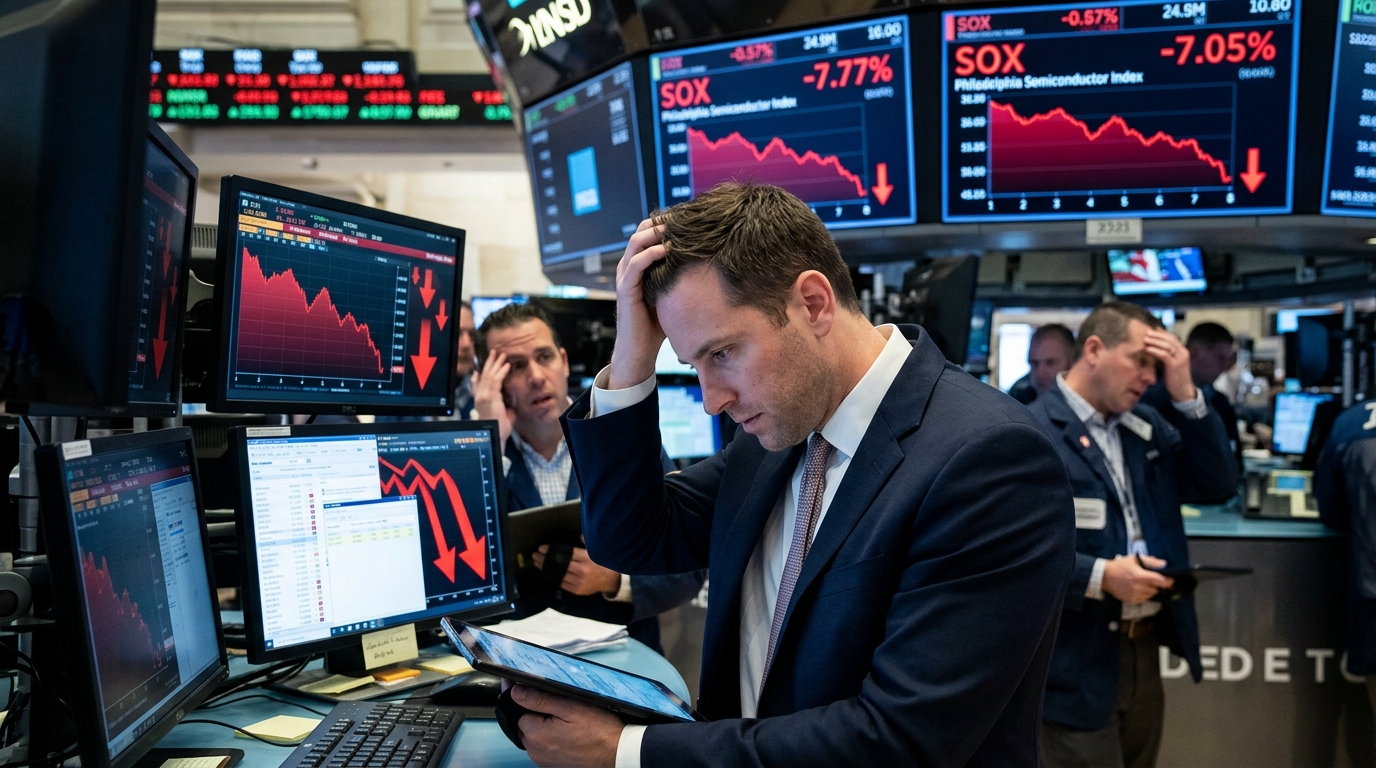
Eight straight down sessions. A 15.7% decline from the October 6 close. Contrarian traders amassed an estimated $32 billion in gross paper gains over seven days, according to S3 Partners data compiled by Bloomberg, as the Philadelphia Semiconductor Index sank more than 12%. That is eight straight lower closes, the longest run for the index since October 2008. The number that matters most is not the index level. It is the $32 billion sitting in short sellers’ accounts.
What Happened
The Philadelphia Semiconductor Index fell 3.83% on Friday, October 16, closing at 11,137.29. Micron Technology fell 5.6%, Advanced Micro Devices dropped 6%, Broadcom lost 4.5%, and Intel gave up 5.8%.
For the week, the Nasdaq fell 4.5%, snapping a four-week winning streak with its worst week since late June. Selling pressure spread beyond chipmakers into software and cybersecurity stocks that had recently shown relative strength. Wednesday’s hotter-than-expected inflation report raised fears of additional Federal Reserve rate hikes, compressing already-stretched valuations on the highest-multiple names in the sector.
Why It Happened
The surface explanation is AI spending anxiety. The real explanation is positioning under pressure from the cost of capital. The reversal follows a steep climb. That kind of run concentrates ownership. Funds with leveraged long exposure in semiconductors face margin pressure when rates move higher, and they sell regardless of whether demand for chips has changed by a single unit.
Coherent shares lost nearly 30% despite quarterly revenue growth of 34% to $2.05 billion, as AI financing fears weighed on chip stocks. Demand did not break. Financing costs did. That distinction is the entire lesson of this week.
How Professionals Might View It
Experienced traders distinguish between a fundamental pricing reset and a positioning unwind. This week looked far more like the latter. On the prior trading day, the three major U.S. indices had all closed higher, yet the Philadelphia Semiconductor Index still fell 0.88% that session, signaling that investor sentiment toward chip stocks remains cautious independent of broader market tone. When a sector falls on green days in the market, that is forced selling, not fresh conviction from bears.
The forced-selling dynamic is not confined to U.S. exchanges. Samsung and SK Hynix holders faced the same crowded-unwind pressure as U.S. semiconductor longs when bond yields spiked.
Disciplined traders note one more thing: investors are now questioning whether AI companies can continue spending enough money to justify those valuations. That is a legitimate question. But legitimate questions can coexist with oversold conditions, and conflating the two leads to chasing moves that have already happened.
What Comes Next
Lam Research is expected to report earnings on October 21, 2026, after the market close. Analysts expect Lam Research to announce earnings of about $2.18 per share and revenue of about $8.13 billion for the quarter. That consensus implies roughly 72% year-over-year EPS growth. If Lam beats and guides in line with those expectations, it would be the clearest available evidence that equipment demand remains intact even as investor sentiment has collapsed.
The reaction to that report will reveal far more than the numbers themselves. A muted bounce on a clean beat would signal that positioning is still unwinding. A sharp recovery would suggest the flush is nearing completion. Watch volume and breadth across SOX components on Wednesday evening, not just LRCX’s price alone.
Equipment demand is the cleanest leading indicator for whether the AI build is intact or stalling. ASML’s guidance raise showed the capital spending cycle accelerating even as semiconductor stocks were selling off.
The Trader’s Lesson
Short sellers did not win $32 billion this week because semiconductor demand fell apart. They won because a crowded long trade collided with rising borrowing costs and forced sellers into an illiquid exit. The practical takeaway: before sizing into any high-momentum sector trade, ask what happens to that position if rates move 50 basis points against you. If the answer is “I get stopped out with everyone else,” the position is too large. The chip index did not need a demand collapse to lose 15.7% in eight sessions. It only needed enough leveraged holders who could not afford to wait.