October 23, 2026
Bonus Content: The 10-Year Yield’s Drop Below 5% Is Built on Fear, Not Facts
Every American Should Unlock Their IRA/401k In 2026
Most Americans have no idea their Retirement Plan is locked down.
Let’s say you’re at a restaurant – you can order anything you want, as long as it’s on the menu.
But what if you found out you have a fish allergy, and you’re at a seafood restaurant?
Because if you’ve had an employer 401(k), then you remember seeing the options:
You can invest in anything you want, as long as it’s on the menu. Same thing with many IRA plans.
But what happens if everything on the menu can make you sick?
That’s what many Americans are facing right now. Because whether you order the S&P Index Fund, the 60/40 Stocks and Bonds mix, or any other combination on the menu…
All the ingredients come from the same kitchen – the stock market.
And you already know the stock market has made people sick.
The ups and downs can be nauseating.
Now that’s not a problem if you’re a few decades away from retirement, because you can ride out the storm, and things could likely turn in your favor.
But when you’re already retired, or about to retire, then the game changes.
Because it’s not about growing your assets anymore, it’s about preserving your assets, right?
That means if you have $1 million saved for retirement…
Then you expect that million to pay for your travel, gifts, visits to family and grandkids…
For the rest of your life. Literally! And that’s a great plan.
So how do you tackle the problem?
You could hope the stock market rockets up again, and grows your retirement…
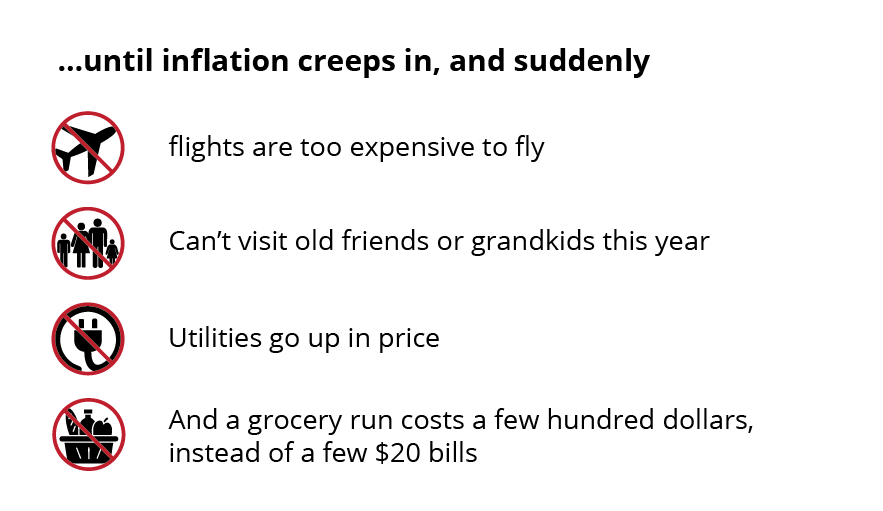
Or you could look at assets that help defend against inflation.
Except the problem is, many IRAs and 401(k)s can be locked out of inflation-defending assets.
But it doesn’t have to be that way.
Because right now, thousands of Americans have figured out how to UNLOCK their IRA/401(k) so they can diversify a portion of their retirement savings into assets that help defend against inflation.
That’s why we put together this free guide.
It’s a brief, to-the-point handbook that shows you:
- The IRS Rule That Lets You Access Locked Retirement Funds
- Who Really Controls Your Retirement Savings
- How To Transition To An Unlocked IRA
And it’s completely free to get a copy.
So what you do with your retirement savings is your business, but at the very least, you should be educated about your options.
But of course, the choice is yours.
The 10-Year Yield’s Drop Below 5% Is Built on Fear, Not Facts
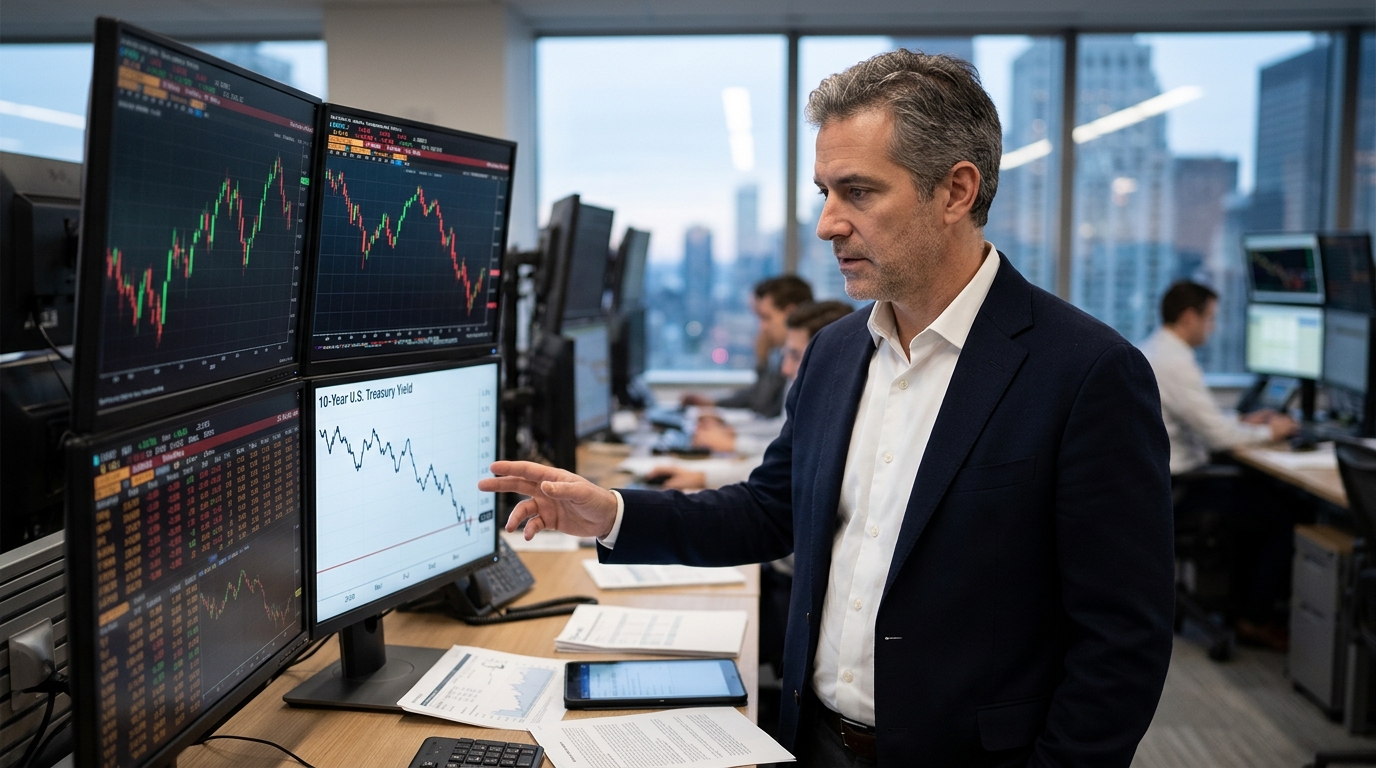
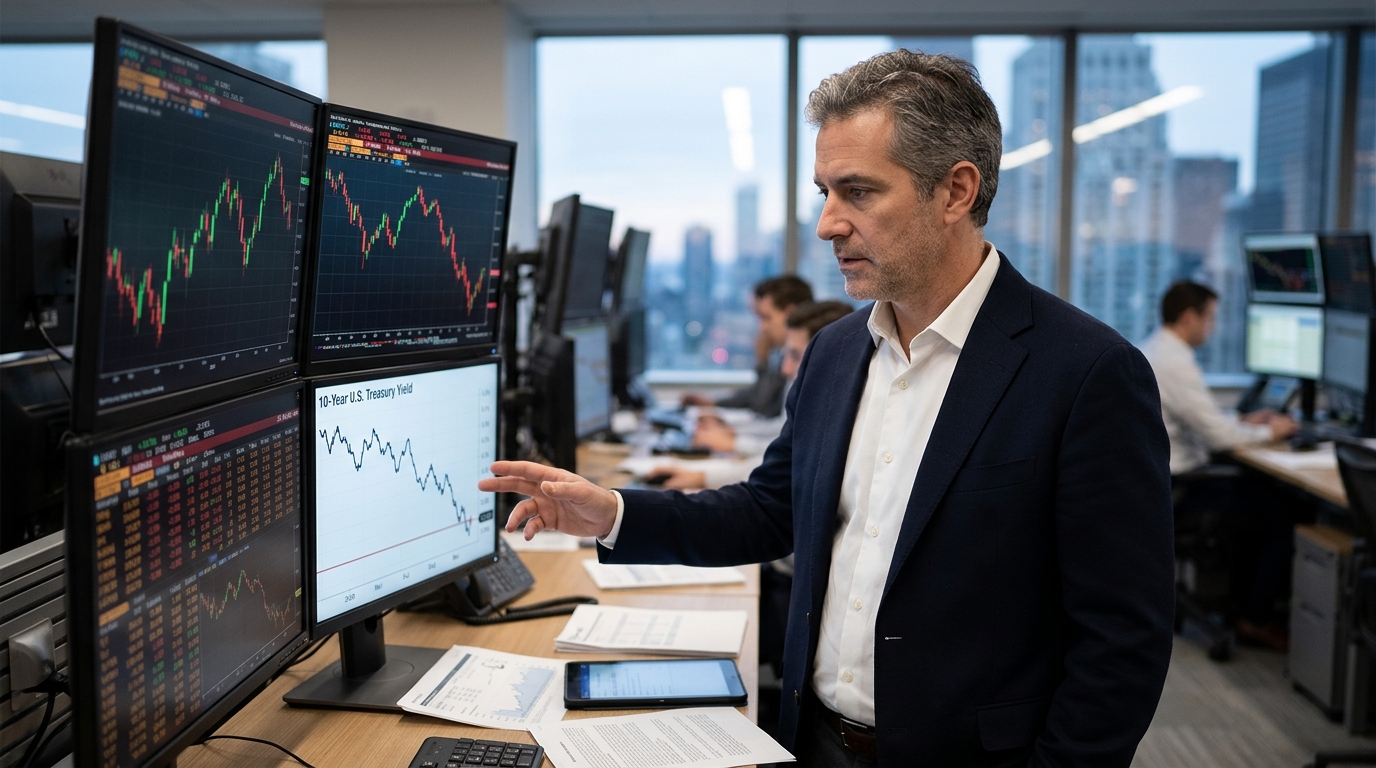
Wednesday’s session handed Treasury bulls exactly the kind of headline they wanted. The benchmark 10-year U.S. Treasury yield fell to about 4.97% from roughly 5.13% the prior day, slipping back below 5% for the first time since Sept. 23. TLT surged. Financial media cheered the reversal.
Don’t confuse the move with a signal.
The drop was driven by a wave of tech stock sell-offs tied to renewed skepticism about AI-era profitability, alongside escalating Middle East risk that pushed money into safe-haven U.S. Treasuries. That is the textbook definition of a fear-driven bond rally, and fear-driven rallies are the least durable kind. They depend entirely on sustained panic in equities. The moment stocks stabilize, the flight-to-safety bid unwinds just as fast as it appeared.
What Actually Moved Yields
“For the first time in a while, Treasuries are enjoying haven status,” said Larry Holzenthaler, senior portfolio manager for fixed income at Catalyst Funds. “You have weakness in tech, an escalation of risk in the Middle East and higher oil. On a relative basis Treasuries start to look like the safe place to hide again in the short term.”
Short term. That qualifier matters. The drop reflects weakening risk assets rather than a policy shift. No economic data surprised to the downside. No Federal Reserve official walked back a hawkish position. The fundamentals that pushed the 10-year above 5% earlier this month have not changed. Core PCE inflation is still running around 3% year over year, keeping pressure on the Fed. And the commodity market is telling a very different story: Brent is around $114 per barrel on October 23. Oil at those levels is an inflation input, not a bond-friendly signal.
Five Days Before the Fed
The timing makes this rally especially fragile. The Federal Reserve meets on October 27-28, 2026, and announces its decision on Wednesday, October 28.
That consensus rests on shaky assumptions about a chair who has systematically refused to confirm it. Fed Chair Kevin Warsh has rejected traditional forward guidance and distanced himself from other officials’ rate forecasts, and elevated inflation and relatively loose financial conditions could still inform the case for another increase. Warsh distanced himself from the September projections at the press conference, saying “These are not my projections.” He delivered a 25-basis-point hike in September that caught many traders off guard. Futures still largely expect a hold on October 28, yet Warsh’s September surprise showed he won’t be bound by what traders expect.
If equities find a floor before Wednesday and risk appetite returns, the flight-to-safety bid in Treasuries dissolves. Yields would press back toward 5% and likely above it, because the fundamental case for higher rates, persistent inflation, higher oil, a Fed chair allergic to forward guidance, remains fully intact. One session does not undo two months of rising borrowing costs.
The Trader’s Lesson
Experienced traders distinguish between two kinds of bond rallies. The first is driven by deteriorating economic data: softer payrolls, cooling inflation, slowing growth. That kind of rally is durable because it changes the policy calculus. The second is driven by equity fear: money fleeing risk assets and parking in Treasuries as a short-term refuge. That kind is borrowed time.
The structural pressure behind both kinds of rallies is the same: a Treasury market absorbing record supply at the worst possible time. A $1.8 trillion deficit in the first ten months of fiscal 2026 means the bond market must clear that supply regardless of where equities trade.
Wednesday was the second kind. Before treating a sub-5% 10-year as a new regime, ask what drove it. If the answer is stock-market fear rather than changed fundamentals, the trade depends on stocks staying scared. That is not a thesis. That is a hope.