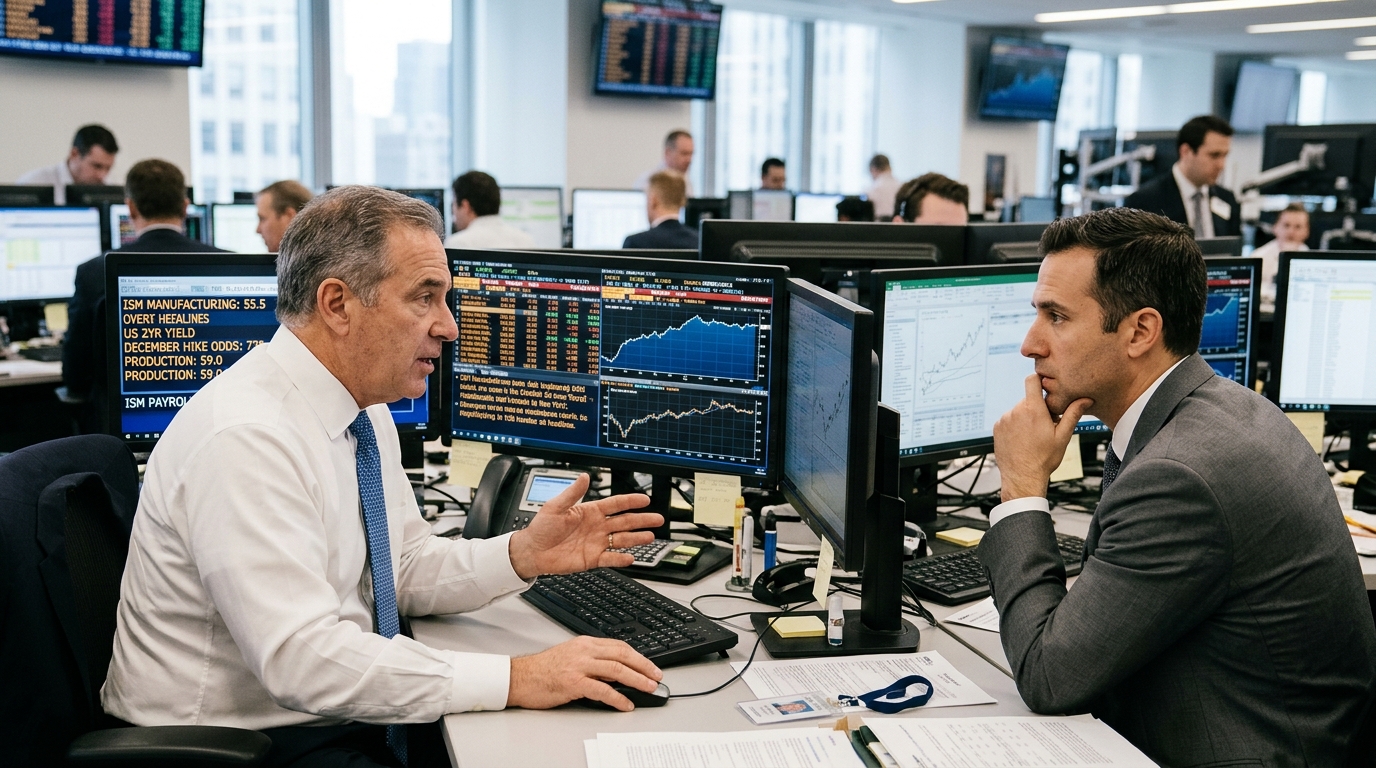
Monday’s ISM report landed with enough force to make the December hike debate feel settled. It isn’t.
The ISM manufacturing index rose 1.0 point to 55.5 in October, the fastest pace since July, beating expectations of 54.7 and marking the tenth consecutive month of expansion, the longest stretch since 2022. Production jumped to 59.0, the highest since November 2021, new orders edged up, and inventories returned to growth, while employment slipped slightly but has now expanded for four months in a row. The prices paid component slipped to 75.2, down 2.7 points. That last piece matters for the Fed’s calculus far more than the headline number.
What the 2-Year Said
Here is where the session gets instructive. As of November 2, OIS pricing implied a 73% chance of a 25-basis-point hike at the December 8-9 meeting. Firm, but not unambiguous. The 2-year Treasury yield closed at about 4.59% on November 2. A manufacturing report that strong, with production at a five-year high, and the policy-sensitive part of the curve barely flinched. The bond market was not ignoring the ISM. It was telling you which half it believed: the production strength, yes, but also the easing price pressures. Hotter growth with softer inflation is not the same policy problem as hotter growth with accelerating inflation. Traders who read the ISM headline and assumed an automatic jolt higher in short rates were wrong about the mechanism.
The Federal Reserve held its benchmark interest rate steady at 3.75%-4% on October 28, with the vote 10-2, as Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack favored a quarter-point hike. Those two dissents matter. They signal that the bar for December is lower than it looks on the surface, and that a second strong data week, particularly Friday’s payrolls report, could tip a hold-leaning committee majority toward action.
The Treasury Wrinkle
Layered on top of the manufacturing data, the U.S. Treasury disclosed its quarterly borrowing plans. Treasury said on Monday it expects to borrow $618 billion in the fourth quarter, $10 billion less than it projected in August, due to a higher-than-assumed starting cash balance that is partially offset by lower projected net cash flows. The near-term supply relief is real. But Treasury projected borrowing of $800 billion for the first quarter of 2027, based on an end-of-March cash balance of $1 trillion. Rates traders who bought the Q4 supply reduction as a durable tailwind for longer-dated Treasuries have a January problem waiting for them. Treasury will release additional quarterly refunding details on Wednesday, November 4, and traders will be watching closely for any sign that it plans to change auction sizes in coming quarters.
The Q1 supply surge is not just a volume problem — it is a demand problem. Foreign official accounts have already shown signs of stepping back from Treasury auctions at precisely the moment supply is set to expand.
What Comes Next
The 2-year is the position to watch between now and Friday. It closed Monday at about 4.59%, sitting comfortably above where it started September. If payrolls land above 200,000 with any upward wage revision, the argument for holding off in December becomes very thin. The FOMC signaled that “the accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2 percent goal.” That language essentially pre-commits the committee to a data-dependent response to whatever the next 72 hours produce.
Rate-sensitive lenders are not passive bystanders in this calculus. Consumer credit data from Ally, Synchrony, KeyCorp and Equifax showed borrowers holding up better than feared, but that resilience was priced before a potential December hike entered the picture.
Sectors with direct exposure to borrowing costs, regional banks and rate-sensitive industrials, are worth monitoring for how they absorb Wednesday’s refunding detail. Any sign that Treasury plans to shift issuance toward the 2- to 7-year part of the curve would compound the pressure on short yields at precisely the moment the Fed is contemplating adding to it.
The Trader’s Lesson
Strong data does not automatically mean higher rates across all maturities. Today’s ISM beat was met by a 2-year yield that barely moved, because the market read two signals simultaneously: production strength argues for a hike, softer prices paid argues against urgency. When a report contains competing signals, the market will often split the difference rather than react to the loudest number. The lesson is to read the full report before sizing a position around the headline. The component that moved least today, prices paid, may prove to be the one that matters most when the Fed votes in five weeks.