Dear Reader,
Democrats have won both the House and the Senate.
That could make things a lot harder for President Trump.
Obviously, now comes the debate over what he can get done in the remainder of his term, and what it means for your money.
But before you make any changes to your investments, there’s something else worth thinking about.
What if the next big financial problem starts OUTSIDE Washington?
As you probably already know, companies are spending huge sums on AI data centers… counting on future revenue to justify the current expenditure.
But what happens if that revenue falls short?
The losses could hit not just AI stocks but also banks and retirement funds. And Washington could face pressure for another bailout.
Our new briefing explains all our concerns and also the steps you can take to prepare.
You’ll also find out how to get our reports on buying gold and silver in a crisis.
As Washington adjusts to the election results, take a moment to check how prepared your money is for what comes next.
Eliza Lasky
Weiss Advocate
Birkenstock Sells 90%+ at Full Price. That Is the Story.
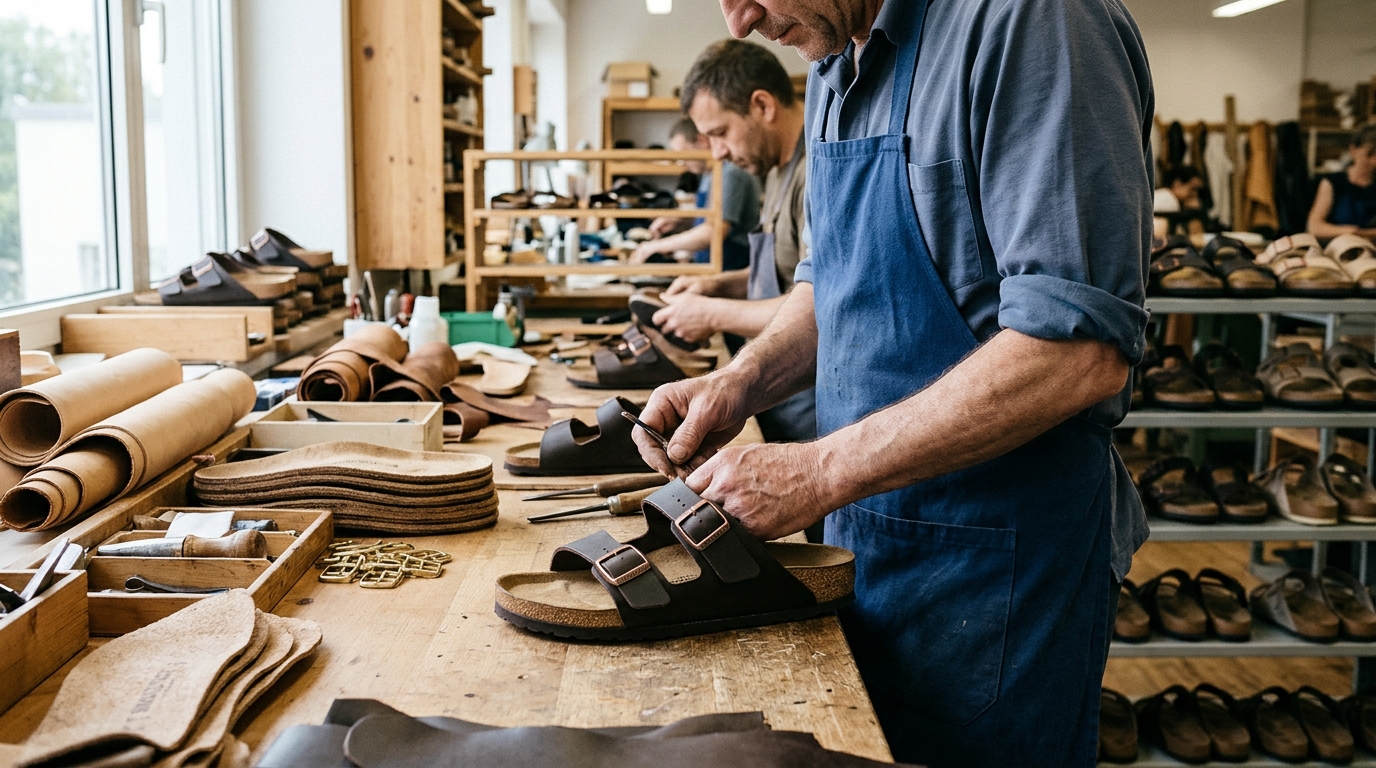
Most footwear brands manage inventory the same way: overproduce, then discount. Birkenstock has spent years doing something structurally different, and the fiscal Q2 earnings call spelled it out plainly. When asked directly about industry-wide markdown pressure, management said that broader retail is leaning harder into promotions as shoppers stay stretched. Then it pointed to Birkenstock’s own full-price selling remaining over 90%.
That figure deserves more attention than it typically gets. Against a backdrop of higher markdown activity across retail, Birkenstock continues to deliver full-price realization above 90%. For context, Birkenstock’s gross margin has generally sat around the high-50s to low-60s in recent years, while many volume shoe brands and DTC challengers typically run sub-50% gross margins, a gap that is one of the clearest signals of pricing power.
The mechanism behind that gap is deliberate supply constraint. Management has said it fulfills roughly 70–80% of wholesale demand, leaving 20–30% unfulfilled, which reinforces brand scarcity and helps sustain full-price selling above 90% across channels. That is not a natural outcome of strong demand. It is an engineered one, and it protects the margin profile regardless of what the broader consumer environment is doing.
There is a newer wrinkle worth watching. Birkenstock has been more active with targeted promotions on select sale inventory, including extra percentage-off offers on Sale styles in its owned channels. The most immediate risk is that a premium model built on full-price selling over 90% starts to drift toward the broader footwear market, where promotions are routine.
That tension is what traders should watch heading into the fiscal fourth quarter report. The fiscal Q3 report was strong. Revenue grew 13% reported and 15% in constant currency to EUR 720 million, with DTC outpacing B2B for the first time in two years, up 16% in constant currency, and DTC penetration rising to 39%. Management raised full-year guidance to 15% constant currency growth and set the adjusted EBITDA target at at least EUR 710 million.
The lesson here is not about Birkenstock specifically. It is about what full-price sell-through actually measures. It is the leading indicator of whether a brand still has permission to charge what it charges. When that number holds above 90% while the rest of the category runs promotions, the brand is demonstrating genuine pricing power. When it starts to slip, no amount of revenue growth covers what is lost underneath.
Full-price sell-through tells you whether the brand still has permission to charge what it charges. Traders in consumer discretionary names should keep that metric visible. It tends to move before the income statement does.