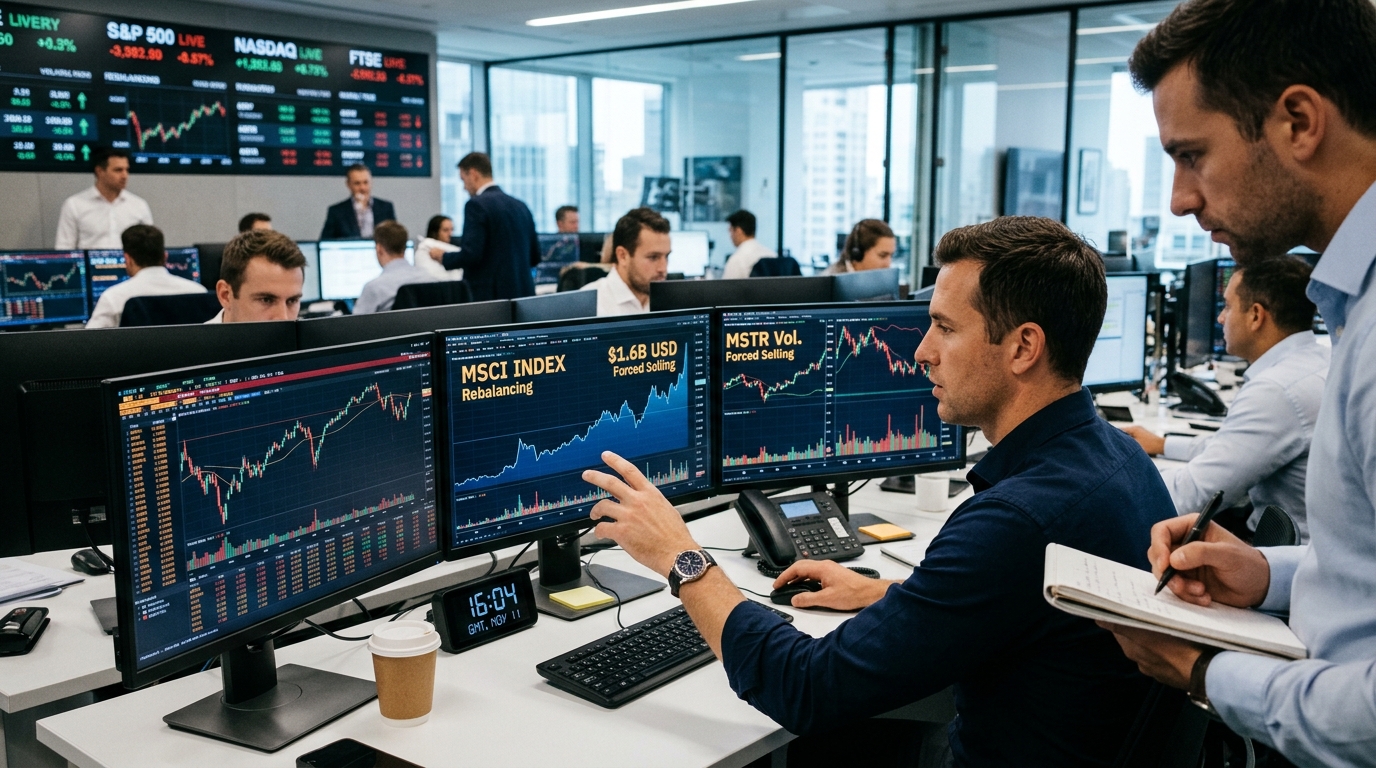
The calendar event traders have been circling for weeks is here. MSCI finalized new rules on Oct. 15 that make non-operating companies ineligible for its global investable market indexes, and today is the day the final list of affected companies drops, with changes taking effect on Nov. 30. Strategy has been on every simulation since May. The question was never really if it would appear on the final list. The question is what happens between now and the end of the month.
Strategy’s own estimate is that passive funds tracking MSCI’s indexes hold approximately 13 million MSTR shares, representing 3.1% of its total outstanding shares, with a current market value of about $1.57 billion. JPMorgan analysts had previously estimated that Strategy’s removal could trigger about $2.8 billion in selling by MSCI-tracking funds, though that figure was tied to MSCI’s earlier digital-asset-focused consultation rather than the final non-operating methodology. The range between those two numbers is wide, but either figure is large enough to matter.
Nineteen days separate the list on November 11 from that cut-off, and in them index funds adjust their holdings. That compression is what experienced traders focus on. Passive funds rarely dump everything on November 30 at the bell. They manage the execution across the window, minimizing market impact. But the direction of that pressure is known, the size is roughly known, and the deadline is fixed. That is a rare configuration: forced selling with a published expiration date.
The stock has already paid some of this forward. MSTR closed at $121.07 on November 10, down 3.60% for the day and about 6.4% from its closing price of $129.30 on November 5. Some of that move reflects pre-announcement positioning. Some of it reflects bitcoin’s own deterioration. Bitcoin closed at about $73,685 on November 11, below Strategy’s reported average acquisition cost of roughly $75,451 per coin.
That bitcoin softness matters for MSTR in a second-order way. MSCI removal would not force a Bitcoin sale, but could reduce the capital available for Strategy’s future Bitcoin purchases. The decision could make it harder for Strategy to raise money to buy more Bitcoin at a time when the stock has already drifted below net asset value support levels that equity issuance requires.
The demand side of the trade is under pressure from a different angle. IBIT’s seven consecutive withdrawal sessions, beginning October 30, have produced $1.66 billion in outflows, while Bitcoin ETFs broadly shed $201 million on Monday. That contrasts sharply with 2024 and 2025, when roughly $25 billion flowed in on a net basis through early November each year. Institutional bitcoin appetite, measured by the clearest daily gauge available, is running in reverse.
The reversal in ETF flows does not affect Strategy alone. Coinbase’s revenue mix shows how deeply institutional Bitcoin appetite shapes the economics of every major crypto-linked equity.
Disciplined traders watch this kind of situation with an interest in process, not prediction. The key distinction is between selling that is fundamental and selling that is mechanical. MSCI-linked fund managers are not making a judgment about Strategy’s business or bitcoin’s value: they are rebalancing to track an index. Some investors may have already traded ahead of the list; the actual price for rebalancing still depends on whether other buyers are willing to absorb the shares. Who steps in on the other side, and at what level, is the real unknown.
The lesson here is durable. When forced, deadline-driven selling becomes visible and quantifiable, it changes the nature of the trade. It is no longer simply about where MSTR should trade. It becomes about liquidity, timing, and who can wait the other side out. Knowing that roughly $1.6 billion of mechanical selling must clear by Nov. 30 is very different from knowing that investors are bearish. One has an end date. The other does not.