The missiles that struck near Riyadh were the kind of headline that has historically sent gold sharply higher. Today, they barely slowed the selloff. That disconnect is the clearest market lesson of the session, and every gold trader should sit with it for a moment.
What Happened
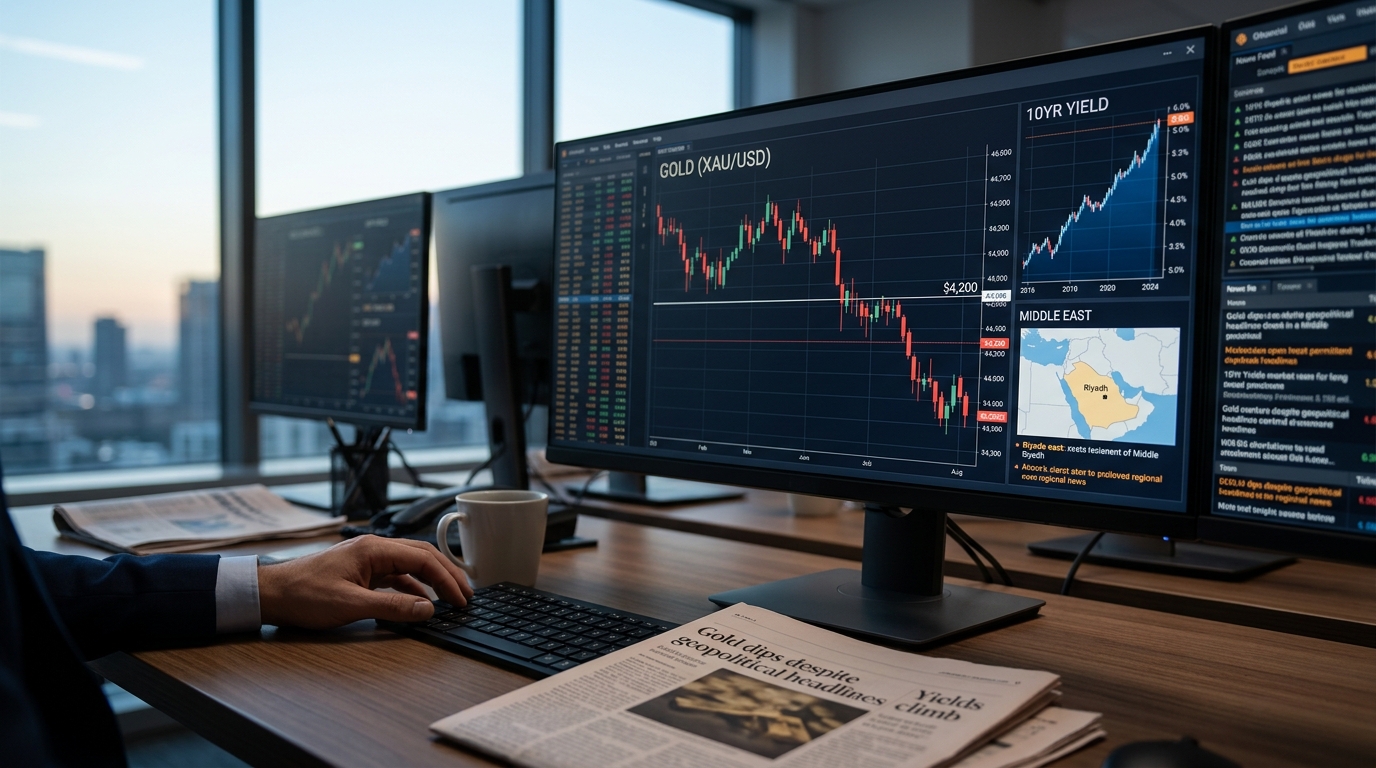
Gold dropped below the $4,200 mark to its lowest level since August 5 during the Asian session, coming under heavy selling pressure at the start of a new week. Spot gold fell to an intraday low of $4,179.42, marking an intraday decline of over $100. The level had held for roughly eight weeks. It did not hold today.
The geopolitical backdrop could not have been more combustible. Iran’s state-linked media and regional reporting over the past week pointed to renewed threats around Gulf shipping, and Saudi Arabia confirmed that Yemen’s Houthi rebels attempted to attack Riyadh with a ballistic missile on September 19, with some residents reporting an explosion and smoke near the airport. Over the weekend, President Trump said he rejected Iran’s proposal to end the fighting and reopen the Strait of Hormuz. None of it was enough to lift gold.
Why It Happened
The answer is rates. The yield on the 10-year Treasury traded around 5.21% on September 28, up modestly from the prior session. Strong U.S. economic data, worsening fiscal conditions, and rising government debt have all weighed on the Treasury market.
The hawkish Fed overlay made things worse. Expectations of higher-for-longer interest rates were reinforced after the Fed’s September quarter-point hike, and recent Fed commentary has kept the door open to additional tightening if inflation does not cool. Cleveland Fed President Beth Hammack has warned in recent remarks that inflation pressures remain elevated and that, if recent trends continue, it may become appropriate to act.
Here is the mechanism that traders need to understand: gold would normally benefit from an oil-driven inflation scare. This time, investors are treating higher energy costs as a reason for the Fed to remain hawkish. The inflation hedge argument backfired. Rising oil fed the rate-hike case, which crushed the haven bid.
How Professionals Might View It
Escalation headlines are textbook haven fuel, yet gold slid anyway. Rates grabbed the wheel. Experienced traders recognize this dynamic immediately: when real rates are sufficiently high, the opportunity cost of holding a non-yielding asset like gold becomes prohibitive, regardless of what is happening in the Middle East.
Disciplined traders would not have been caught flat-footed here. The technical warning came well before today. Gold’s support at $4,200 was structurally important, and the Fed and yield action were always likely to make the largest near-term price impact. The geopolitical overlay was a distraction from the dominant variable, and confusing the two cost bulls dearly.
What Comes Next
With $4,200 now the near-term line in the sand and $4,000 the next meaningful support, momentum favors another leg down if yields stay elevated. Investors now await the Fed’s preferred inflation gauge and key U.S. jobs data due this week, which could provide further clues on the path of monetary policy. Those prints matter more to gold right now than any Strait of Hormuz headline.
GDX and individual miners such as NEM and AEM face compounding pressure: lower gold prices meeting higher operating costs in an energy-shock environment. Watch them for confirmation of whether institutional selling is accelerating or stabilizing.
The key risk to the bearish case is a sharp drop in U.S. yields, or a Fed pivot, that flips gold back into an inflation hedge and forces a fast rebound above $4,300 to $4,350. That scenario requires an economic surprise, not a missile launch.
The Trader’s Lesson
The haven trade is conditional, not automatic. When real rates are positive and rising, gold competes against assets that actually pay you to hold them. Geopolitical fear can still generate short-term spikes, but disciplined traders know to identify the dominant regime before assuming the traditional playbook applies. Today, the regime is 5%-plus yields and a Fed leaning toward more tightening. In that environment, the burden of proof falls on gold bulls, not bears. Position accordingly until the rate picture changes.