October 9, 2026
Bonus Content: The Fed Is Pointing to December. The Dollar Priced It In.
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The Simple Path To Success With Options”
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
2026 TradeWins.com. All Rights Reserved. Privacy Policy | Disclaimer | Terms and Conditions | Contact Us
NOTICE: Auto-trading, or any broker or advisor-directed type of trading, is not supported or endorsed by Ian Cooper. The information provided by Ian Cooper in its various materials, including trading recommendations, newsletters and educational publications is not customized or personalized for any particular person or risk profile. Past results are not necessarily indicative of future results. Results presented can vary and may not be typical for all subscribers. There are substantial risks involved with investing in the stock and options market, including the risk of total loss. You should only trade or invest “risk capital” – funds you can afford to lose.
The Fed Is Pointing to December. The Dollar Priced It In.
Governor Christopher Waller stood at the Istanbul Economic Forum on Thursday and said what the bond market has been pricing for weeks: more rate hikes are coming. He expects the Fed will need to enact more interest rate hikes to bring down inflation faster if economic data comes in as he expects. The reaction in the dollar was almost a shrug. That non-reaction deserves more attention than the speech itself.
The Fed raised its target range to 3.75%-4.00% on September 16 in a 12-0 vote, and minutes released on Wednesday showed most policymakers expect another increase by year-end, with many seeing the risks to inflation tilted higher. Waller’s Istanbul remarks didn’t move the needle on that consensus. What they did was clarify the calendar.
“There is some flexibility about when those hikes will occur,” Waller said. “The hikes do not need to come at consecutive meetings, but they should be in place within an acceptable period of time.” Translation: October is not the target. December is.
Markets put October at about a 15%-17% probability for a hike and December around 75%. The committee alignment, paired with Waller’s explicit comfort with skipping October, is the clearest signal the Fed has given since September.
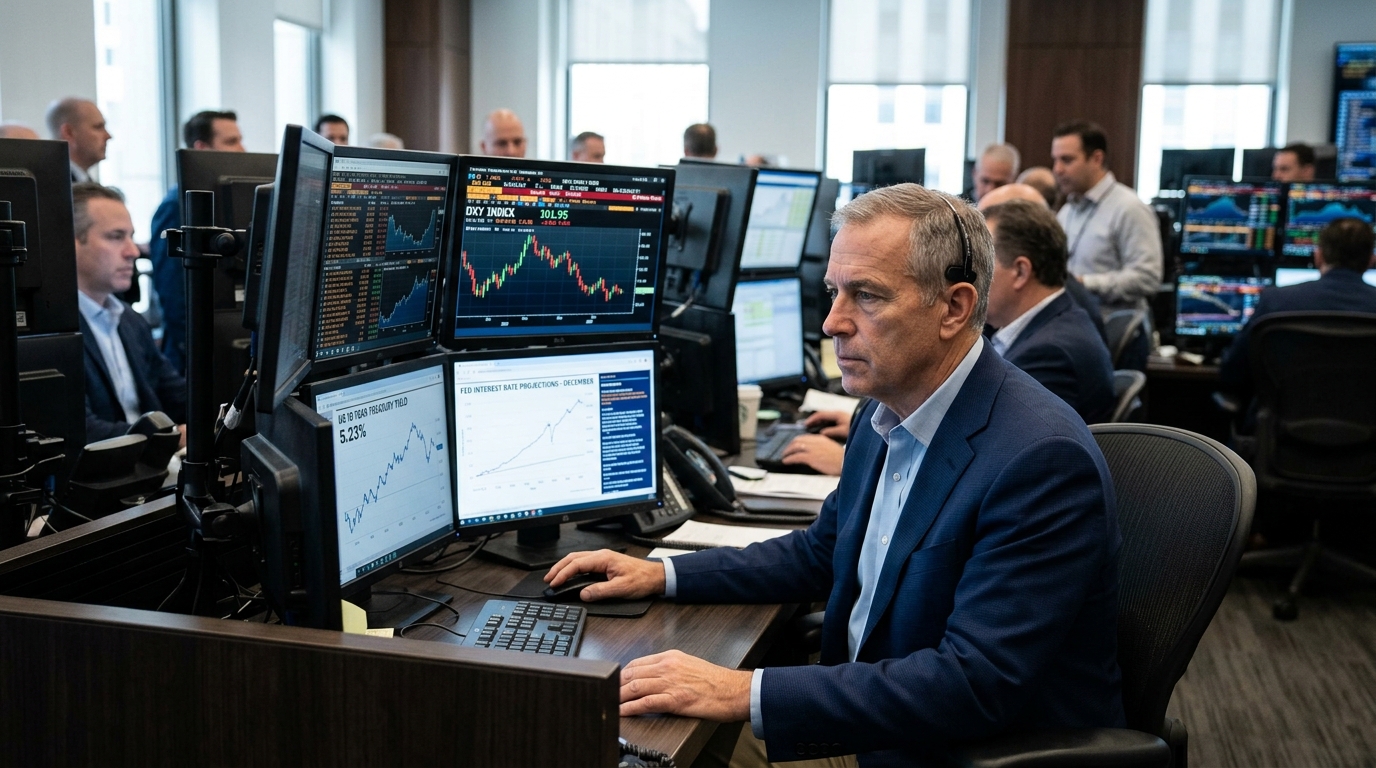
The harder question for traders is what this environment means for the assets sitting on top of this macro foundation. The dollar index traded around 102 this week, near its highest levels since early 2025, as volatility in oil markets continued to fuel inflation concerns and reinforce expectations that the Fed may need to keep policy tighter for longer. Over the past month, the dollar has strengthened by roughly 3.5%.
The yield on the 10-year Treasury eased to 5.23% on October 9, marking a 0.01 percentage point decrease from the previous session, after touching about 5.36% earlier this week, its highest since 2002. The 10-year is not a side story here. It is the rate against which equity valuations, corporate borrowing costs, and currency differentials are all being measured.
EUR/USD illustrates the pressure clearly. The pair rose to around 1.12 on Friday but has weakened roughly 3.3% over the past month. USD/JPY tells a similar story: the yen weakened to around 158.5 per dollar during the week as the wide yield gap between the U.S. and Japan continued to favor the dollar.
Waller also flagged forces that could keep inflation elevated longer than the baseline assumes, including energy-price volatility tied to the Middle East conflict, price pressures linked to the AI buildout, and the risk that trade frictions and potential new tariffs could add to inflation. None of those are short-cycle risks.
Here is today’s lesson. When a central bank official delivers a speech and the market barely moves, the usual interpretation is that he said nothing new. That is partly true. But it also means the existing pricing already reflects a meaningful amount of tightening, and the dollar and yields have already done work that traders in equities, credit, and currencies may not have fully internalized. The macro backdrop is not a risk event on the horizon. It is the current condition. Every sector rotation, every earnings-season positioning call, every carry trade in the FX market is running on top of a 5.23% ten-year and a Fed with a December hike at roughly 75% odds. Build accordingly.