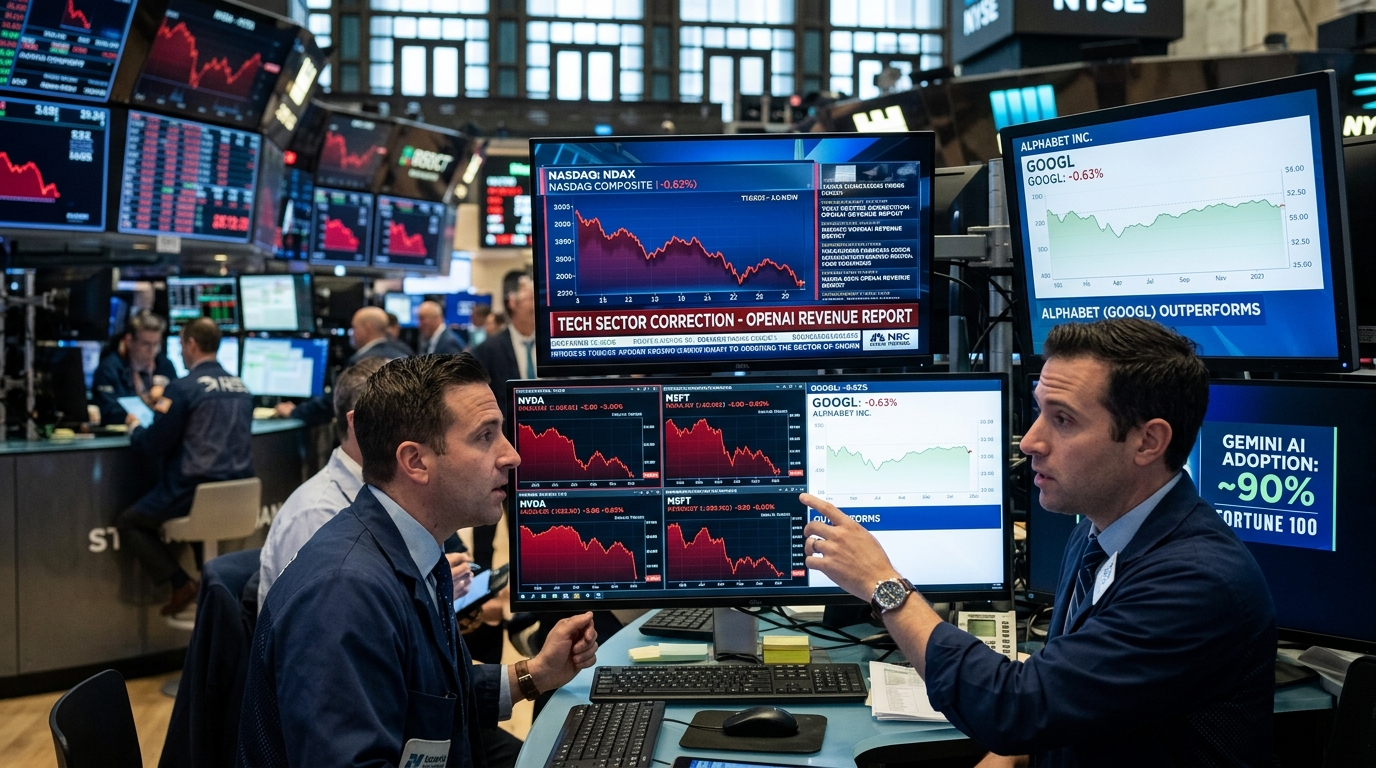
Thursday was the kind of day that separates durable AI businesses from speculative ones. Technology stocks fell after a report revealed that OpenAI’s annualized revenue was approaching $50 billion, roughly $20 billion below the $68 billion figure that had been widely circulating. The Nasdaq dropped more than 1%. Nvidia slid nearly 3%, Microsoft fell 1.35%, and Alphabet closed down just 0.63%. That relative strength was not accidental.
Alphabet shares rose about 1% during Thursday’s session before trimming gains into the close, outperforming a broader tech selloff after Google Cloud unveiled a universal Gemini agent. The market was essentially voting in real time. If AI revenue is harder to monetize than the bulls believed, which company is best positioned to prove otherwise? The answer it landed on was GOOGL.
What Google Actually Launched
Google Cloud announced a universal AI agent for work called Gemini agent, to be joined by industry-specific agents for financial services, legal, government, healthcare and retail. The agent works across Google Workspace apps, can be accessed from different devices and channels, and is designed to carry the same memory, skills and controls everywhere it operates. More practically: instead of staying locked inside Google Workspace, the Gemini agent is designed to connect out to other business tools.
Agents for financial services and legal are now in preview, with government, healthcare and retail versions to follow. These are not consumer experiments. These are deeply vertical deployments aimed at the highest-value enterprise buyers on earth.
Why the Installed Base Changes Everything
The OpenAI revenue story raised a fair question: who is actually converting AI enthusiasm into recurring enterprise contracts? Google Cloud CEO Thomas Kurian said nearly 80% of Google Cloud customers now use the company’s AI products, and that nearly 90% of the Fortune 100 use Gemini Enterprise. That footprint did not materialize from Thursday’s announcement, but the “Gemini Enterprise” portion of that claim is not something Alphabet’s July 2026 Q2 earnings materials clearly documented.
Google Cloud’s AI business is already scaling rapidly. Revenue for the division reached $24.8 billion in the second quarter, up 82% year over year. Google also reported $519.5 billion of remaining performance obligations as of June 30, 2026, with $513.9 billion related to Google Cloud. The universal Gemini agent is now the upgrade path for customers who are already paying. That is a fundamentally different commercial motion than what OpenAI or Anthropic are running.
What Could Go Wrong
Alphabet is not risk-free here. The company is spending heavily on AI infrastructure, and investors will demand evidence that enterprise AI contracts justify it. Thursday’s broader retreat came against climbing bond yields, renewed trade concerns, and a crude oil surge that steered capital toward energy and away from richly priced growth names. Any sustained rotation out of mega-cap technology would pull GOOGL lower regardless of product momentum.
Competition is also genuine. Microsoft’s Copilot is deeply embedded in Microsoft 365 accounts that Google does not touch. OpenAI’s enterprise push, even if revenue was overstated, is real. The universal agent is still in preview, and deployment at scale inside regulated industries takes time.
The Bottom Line
Alphabet’s next earnings report is expected on October 28, 2026, though the date is not always confirmed far in advance. Sixty-two analysts rate the stock a Strong Buy, with a consensus 12-month price target of $429.47, representing about 23% upside from recent levels. At a trailing price-to-earnings ratio of roughly 17.5, Alphabet is not priced like a speculative AI bet. It is priced like a search company that Wall Street has not yet fully re-rated as the enterprise AI leader it appears to be becoming.
Thursday offered a clean look at which AI company the market trusts when the mood sours. Google says Gemini Enterprise is used across nearly 90% of the Fortune 100. Thursday it launched the product designed to deepen that relationship across five of the highest-value verticals in the economy. That combination of proven revenue, expanding footprint, and a clear upgrade catalyst makes GOOGL the most compelling single AI stock available today.