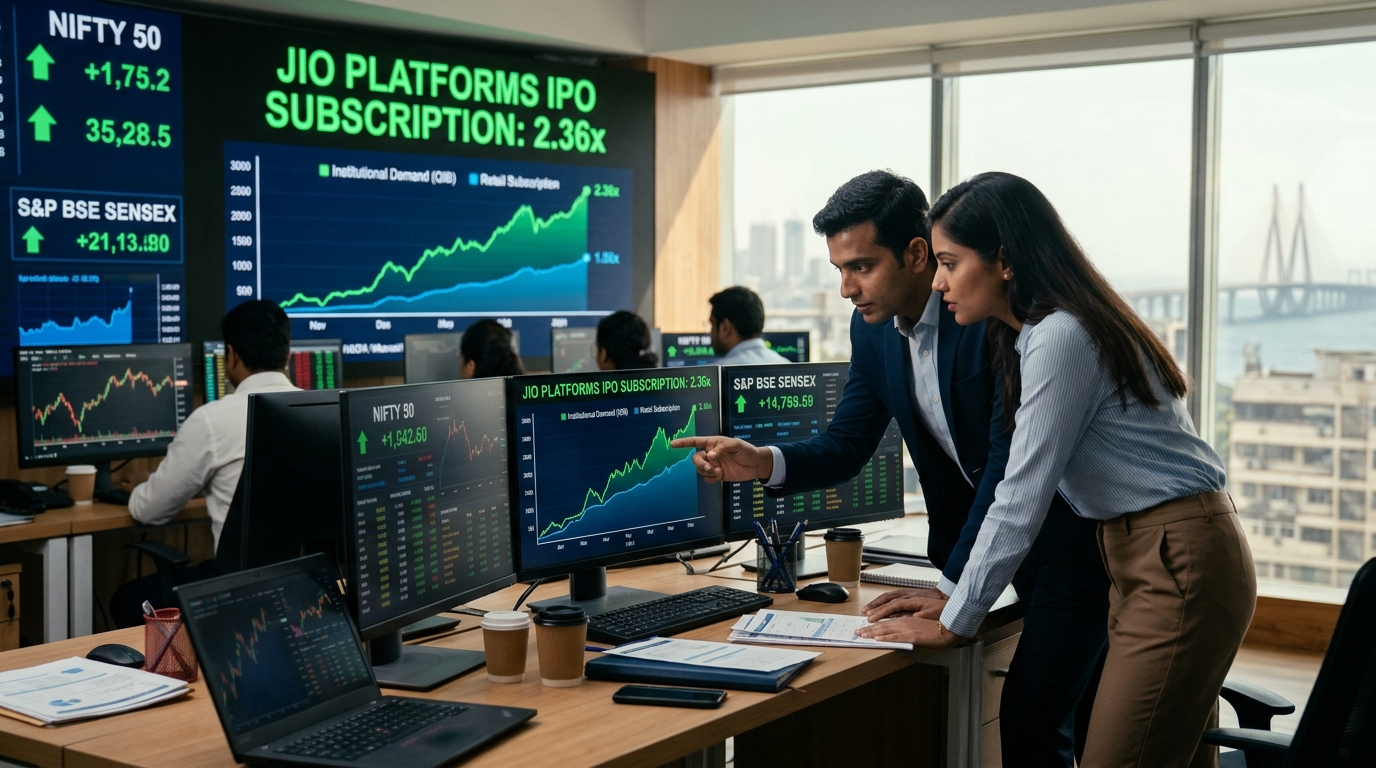
India’s largest-ever IPO cleared its first serious test this morning. Jio Platforms opened for subscription on October 21, and by about 2:48 PM local time the issue had been subscribed 2.36 times overall. That is a stronger reading than the early-day updates, when headlines declared the book covered.
The institutional category (QIB), excluding anchor investors, drove the bulk of the demand, reaching 7.09 times subscribed, while the non-institutional category (NII) was about 1.04 times and retail investors came in at about 0.58 times their allotted portion. The retail shortfall matters: it suggests ordinary investors are more cautious than the headline number implies, even as professional money piles in.
The anchor round set the tone. Ahead of the opening, institutions bid more than ₹2.5 lakh crore for a ₹8,109.85 crore anchor allotment, over 30 times the amount on offer, as reported by outlets including The Economic Times, Moneycontrol, and Fortune India. Global names in that book include BlackRock, Capital Group, Fidelity, T. Rowe Price, Schroders, JPMorgan Asset Management, Franklin Templeton, Janus Henderson, the Abu Dhabi Investment Authority, and the Monetary Authority of Singapore. That list answers the question of whether global funds are skeptical: they showed up in size.
The price band is ₹1,065 to ₹1,119 per share, with the upper end implying a valuation of roughly ₹10.3 lakh crore. Using FY2026 net profit of about ₹30,049 crore as cited in pre-IPO coverage, that translates to a historical price-to-earnings multiple of approximately 34 times at the upper band. For context, the implied valuation sits below Bharti Airtel’s roughly $123 billion market capitalisation, which gives bulls a relative-value argument and skeptics a reason to probe Jio’s margin gap.
The grey market is not waiting for allotment day to decide. Several widely followed trackers put the grey-market premium at about ₹253 to ₹265 during the day on October 21, after touching as high as ₹273 on October 20 and trading around ₹148 in early October. At ₹265 above the upper band, the implied listing price is around ₹1,384, a nearly 24% premium before a single share trades on the NSE or BSE.
Here is the practical problem for most readers outside India: Reliance Industries-backed Jio Platforms is raising about ₹30,213 crore through this IPO, and direct participation typically requires a local demat account. The better question is what the IPO means for exposure investors already hold.
The iShares MSCI India ETF (INDA) seeks to track an index of Indian equities and offers targeted single-country exposure; in its published fund materials this year, Reliance Industries is listed at roughly 6.7% of the fund. The iShares India 50 ETF (INDY) tracks the 50 largest Indian stocks and offers large-cap concentration; public holdings snapshots around this period show Reliance at roughly 8% of the portfolio. Once Jio Platforms lists on October 28, index inclusion in future rebalancing cycles could lift Reliance’s subsidiary value further, creating an indirect tailwind for both funds.
Reliance Industries itself trades around ₹1,220 today, sitting roughly 24% below its 52-week high of ₹1,611.80 (January 5, 2026). The company reported FY2026 revenue of about $124 billion and net profit of about $10.1 billion, up 17.8% year over year, which means the parent is not richly priced relative to the subsidiary’s IPO multiple.
The enduring lesson here: the most consequential opportunities rarely arrive in a form you can access directly. What matters is recognising the structural shift, India’s digital economy reaching public-market scale, and ensuring your portfolio has a sensible path to it. For most long-term investors, that path runs through funds and parent companies, not IPO bidding queues. Discipline about the vehicle matters as much as conviction about the idea.