October 22, 2026
Bonus Content: UK Inflation Came in at 3.5%. One Tenth of a Point Just Changed Everything.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader,
The AI stock bubble is about to pop!
And the collapse of one major AI company could be the catalyst.
According to financial expert Jim Rickards – the man who has accurately predicted the last two market crashes three weeks in advance…
This company could trigger a catastrophe 10X worse than Lehman Bros. in 2008…
Resulting in an 80% market crash…
And wiping out trillions of dollars in wealth.
And no… This is NOT Nvidia.
Click here to discover this company now.
Inside, you’ll also learn the 5 simple steps Jim says you should take right now to protect and even grow your wealth – even in the face of a total market collapse.
Click here for Jim’s assessment.
Regards,
Matt Insley
Publisher, Paradigm Press
P.S. This could all start as soon as October 29th, so there’s no time to waste. Make sure you get in position now, before it’s too late.
UK Inflation Came in at 3.5%. One Tenth of a Point Just Changed Everything.
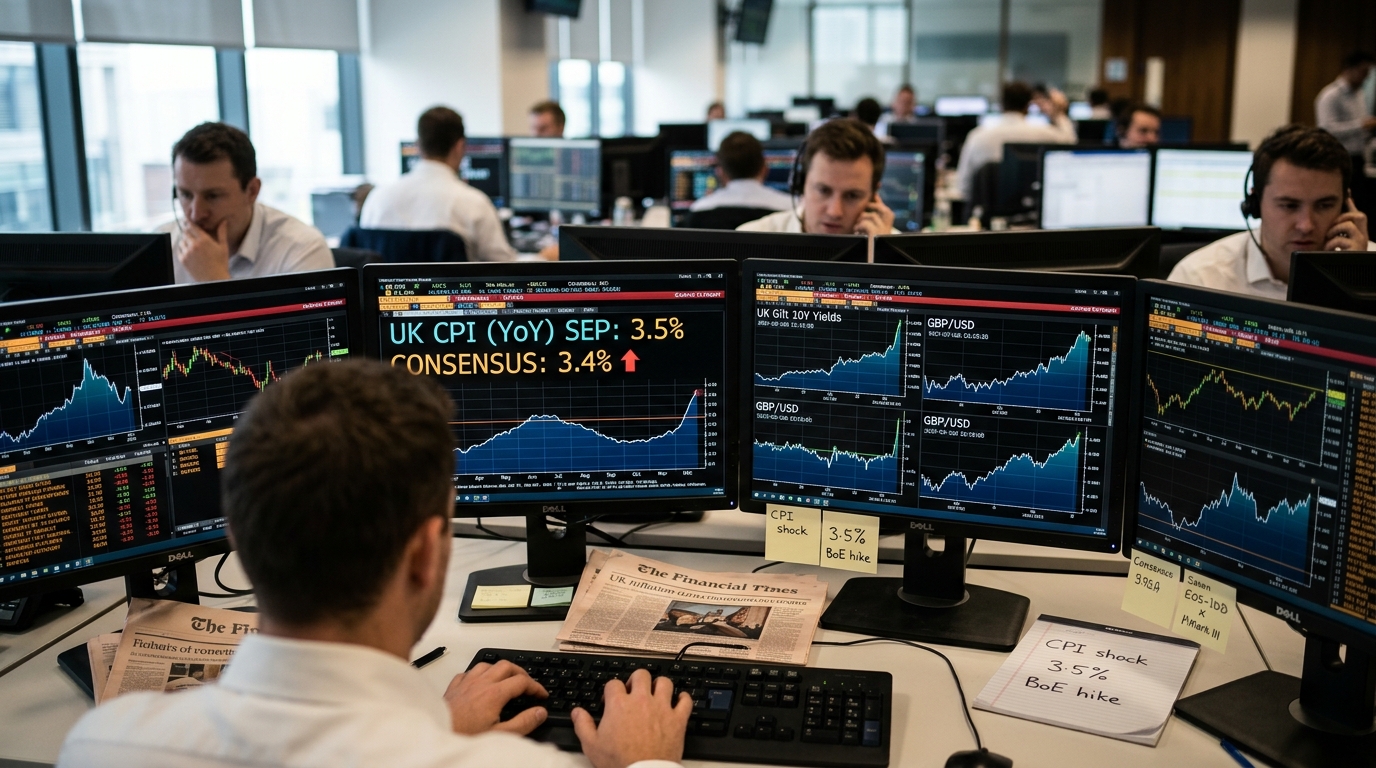
One tenth of a percentage point. That is the margin between what the market expected from this morning’s UK inflation report and what it got. The Consumer Price Index rose 3.5% year-on-year in September, above the 3.1% reading in August and above the market consensus of 3.4%. Traders who dismissed the gap as rounding noise paid for it in gilts.
Core CPI climbed to 2.8% from 2.6%, while services inflation accelerated to 3.7% from 3.4%. Those figures matter because they speak to domestic price pressure, not just energy. When headline and core move together, it becomes harder to argue the number is a statistical artifact.
Why the Market Moved
Core and services inflation moving higher together makes it harder for the Bank to dismiss the latest increase as temporary. That was the read that rippled through fixed income. In late September, Reuters reported that 10-year gilt yields hit about 5.44% in secondary trading, their highest since July 2007. The pound, meanwhile, found support from the same logic: tighter monetary policy is good for the currency, at least in the near term.
The energy story underneath this number is real. UK pump prices jumped late in the summer, and the Ofgem energy price cap is set to rise by 4% for the 1 October to 31 December 2026 quarter. That helped drive the headline surprise. But experienced traders did not stop there. They checked whether energy was pulling the rest of the index with it, and the core and services measures moved higher too.
Take a look at this post from Elon Musk.
According to the man who called Tesla before it soared 1,216%…
“Mission X” is about to change everything.
And right now, you have a chance to get in at practically the ground floor.
How Professionals Read It
The Bank of England held Bank Rate at 3.75% in September by a 6-3 vote, with three members preferring a 0.25 percentage point rise to 4.00%. Before this morning’s figures, Reuters reported that a large majority of economists in its poll expected a November rise to 4%. Today’s data does not add doubt, it removes it.
The discipline in reading a release like this is sequence: headline first, core second, services third. If all three move the same direction on the same release, the signal is worth trading. Today they did. The trader who waited for confirmation across all three had a cleaner entry than the one who reacted to the headline alone.
What Comes Next
The timing makes this data release unusually consequential. The Budget arrives Wednesday 28 October 2026, and it comes as higher energy prices fuel inflation and government borrowing costs rise. With benchmark 10-year yields having moved sharply higher since the recent escalation of the Iran war, the fiscal arithmetic for Chancellor Healey has tightened considerably before he even stands at the dispatch box.
For UK bank shares, Barclays, Lloyds, and NatWest, the calculus is mixed. Higher rates expand net interest margins but raise credit risk as borrowers refinance into a more expensive environment. Separately, the risk around fiscal policy has not gone away: Reuters has reported that bank executives have been lobbying against the prospect of further sector tax rises. Rate tailwinds and fiscal headwinds are pulling in opposite directions, which argues for watching those stocks closely against the Budget news next week rather than positioning ahead of it.
The rate-versus-credit-risk tension in UK bank shares mirrors a divide already visible among US lenders. JPMorgan’s own guidance on investment banking fees and trading revenue contradicted the cautious signals coming from Bank of America at the same conference.
The Trader’s Lesson
Today’s session was a reminder that the size of a surprise matters less than its composition. A 0.1 percentage point miss on headline CPI would normally be noise. This one moved markets because core and services confirmed it. Before reacting to any data release, ask what the rest of the report says. A headline in isolation is information. A headline backed by its components is a signal.