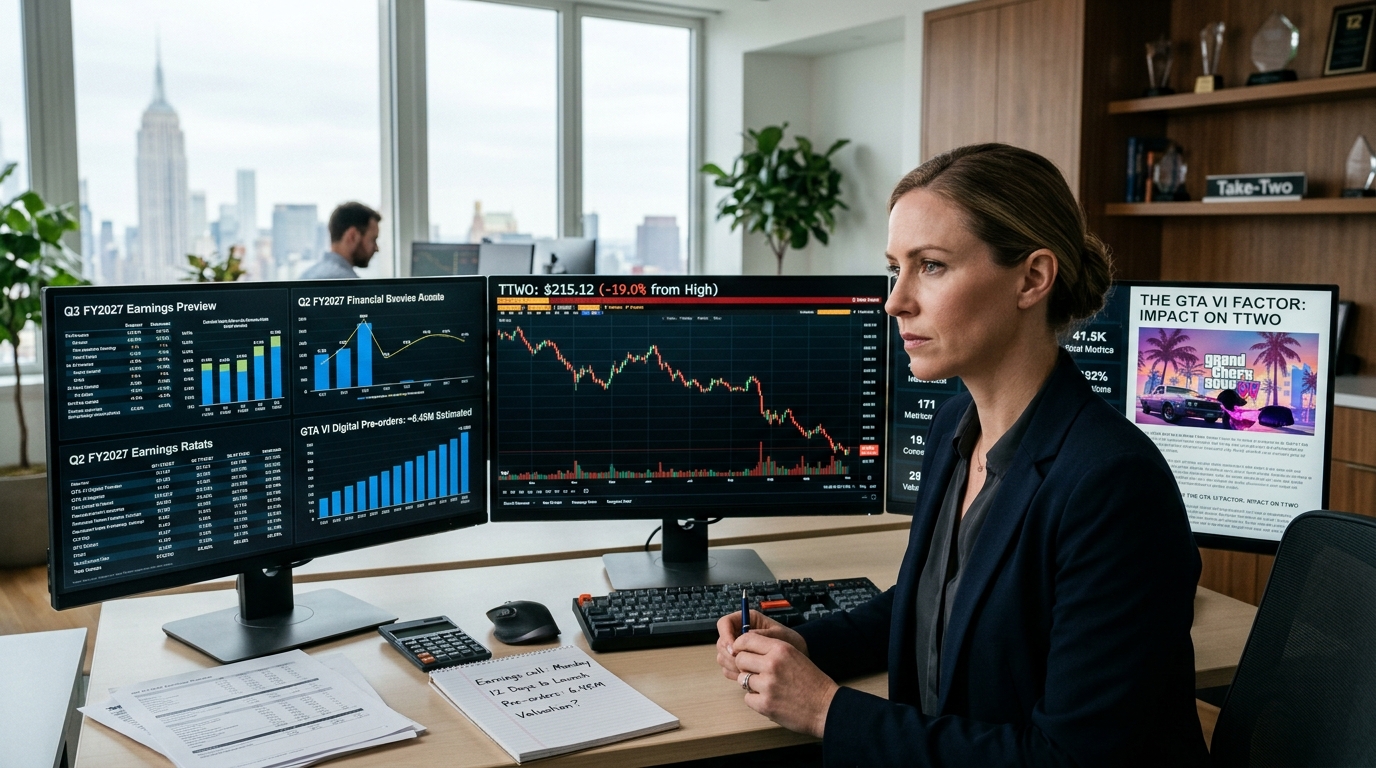
TTWO sits at roughly $215, about 19% below the $265.94 it touched in July. The game ships November 19. Monday’s earnings call is the last investor conversation before Rockstar’s biggest release in history lands. So the question isn’t whether Grand Theft Auto VI will sell. It’s whether buying the stock today still pays.
Why Wall Street Is Paying Attention
Take-Two will hold its Q2 FY2027 earnings call on November 9, its last public update before Grand Theft Auto VI launches November 19. The quarter being reported ended September 30 and contains zero GTA VI revenue. That means the entire call comes down to three things: whether management reaffirms the launch date, whether the full-year bookings guide holds, and what Strauss Zelnick says about demand signals heading into launch week.
Average revenue per pre-order comes to roughly $98, based on Sensor Tower’s October estimate of 6.45 million digital pre-orders, and the tracker implies about $630 million in pre-order revenue so far. That is real money before a single copy has shipped. Management’s own guidance for the quarter calls for net bookings of $1.62 billion to $1.67 billion, alongside a GAAP net revenue range of $1.42 billion to $1.47 billion.
What’s Driving the Opportunity
Take-Two’s FY2027 is expecting net bookings in the range of $8.0 billion to $8.2 billion, which includes the release of Grand Theft Auto VI in November 2026. For context, FY2027 net bookings guidance of $8.0 to $8.2 billion is roughly 19% up on last year’s $6.72 billion. The underlying business was already compounding before this launch. A company generating $6.72 billion in net bookings, with recurrent consumer spending accounting for the large majority of GAAP net revenue, does not look like a single-title bet.
Piper Sandler reiterated its Overweight rating and a $290 price target, modeling more than 45 million sales at GTA VI’s launch. Wedbush projects 31 million units in the launch quarter and quarterly net bookings of $3.437 billion. Wall Street is broadly clustered around the high-$200s on its 12-month targets, implying meaningful upside from the last close.
What Could Go Wrong
The single biggest structural risk is one the company confirmed itself. At the annual shareholder meeting, CEO Strauss Zelnick confirmed there is no recurrent consumer spending anticipated with regard to this launch, since the game is shipping as a single-player experience. Take-Two’s online business is the business. GTA VI online, the engine that would sustain multi-year revenue, has no announced launch date.
There is a precedent-based case that online follows quickly, as it did with GTA V and Red Dead Redemption 2. But there is no timeline given for any future online mode, no roadmap teased, and no formal announcement of timing for a next-generation GTA Online experience. GTA 5 launched in September 2013 with GTA Online arriving a few weeks later, and that gap was already planned and communicated in advance. There is no confirmed date, no confirmed format, and no clear signal that the online component is coming soon after launch rather than much later.
Then there is the valuation math. The company forecast net bookings between $8 billion and $8.2 billion for fiscal 2027, and at least some sell-side models sit above that range. Several analysts have characterized Take-Two’s guidance as conservative ahead of major launches, consistent with its historical approach. That is worth remembering, but conservative guidance still sets a ceiling on how surprised the market can be on Monday.
The Bottom Line
TTWO is down nearly 20% from its summer peak. The stock was pricing in a perfect outcome in July. Today it is pricing in something closer to a good one, which is arguably the more rational entry. The launch-day revenue is a known quantity by most measures. What is not known is how quickly GTA VI online arrives, and that delay determines whether this stock rerates in November or becomes a 2027 story. Monday’s call won’t answer the online question. What it can do is confirm the date holds, reaffirm the full-year guide, and give Zelnick a final platform to frame the opportunity before the game proves itself. For investors, the more compelling trade is probably not the earnings catalyst itself but the period after launch, when actual sales data replaces projection. The uncertainty here is real, but so is the gap between $215 and where most of Wall Street thinks this stock belongs.