Dear Reader,
My name is Jeff Brown, founder and CEO of Brownstone Research.
And I want you to circle one date on your calendar…
That’s the day a tiny company could announce a huge supply deal with Elon Musk.
It’s a stock trading at under $1…
In an overlooked sector you’d never associate with tech.
But Musk’s robots, microchips and AI satellites all rely on it.
And on page 37 of the SpaceX IPO filing, Musk names this sector directly.
Why does that matter?
Because Musk raised $85.7 billion from the SpaceX IPO…
And a further $25 billion by selling bonds.
That money is about to flow downstream.
And when a Musk supplier in this sector announced a deal before…
The stock soared 395% in a single day.
That’s almost five times your money…
Before the sun goes down.
I recently sat down with an insider in this sector to talk about what could happen on November 11.
A man who once turned $13,140 of his own money…
Into around $1.85 million in under a year.
In our urgent strategy session, we reveal the name and ticker of a crucial Musk supplier…
Entirely for free.
But once November 11 arrives, this opportunity could be gone.
Click here to watch the strategy session before November 11.
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
Strategy’s MSCI Decision Lands Nov. 11. Passive Selling Risk
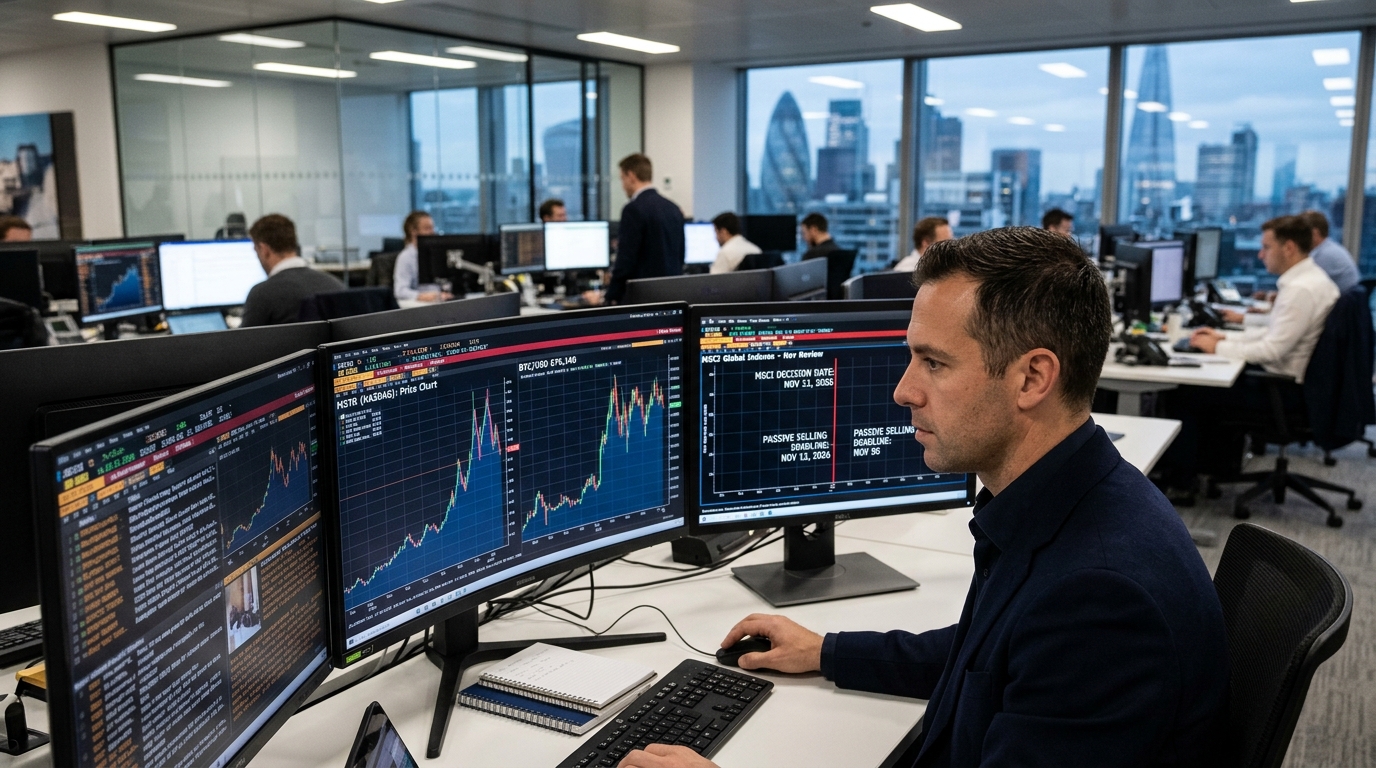
Wednesday is not a catalyst. It is a deadline. When MSCI publishes its final November index review results on November 11, traders will learn whether Strategy (MSTR) is removed from MSCI’s Global Investable Market Indexes effective November 30. The question is not whether the rules are fair. The question is what happens to the shares.
What Happened
On October 15, 2026, MSCI announced the results of its consultation on the eligibility of non-operating companies and said such companies will be ineligible for its Global Investable Market Indexes starting with the close of the November 30, 2026 index review. The change replaces the earlier digital-asset-focused interim measures with a broader, quantitative framework. Under MSCI’s published description of the framework, companies are first assessed against a core operating-asset screen, and issuers that fail it are then evaluated using five non-industry-specific financial ratios. MSCI has also said that existing index members are generally removed only after failing the relevant tests across two consecutive annual reporting periods.
MSCI has said it will post the additions and deletions for the November 2026 Index Review shortly after 11:00 p.m. on November 11, with all changes implemented as of the close on November 30.
Why It Matters to Traders
This is a flow event with a known schedule. If Strategy appears on the November 11 deletions list, index-tracking funds tied to MSCI benchmarks would need to adjust holdings by the close on November 30. Index funds do not negotiate. Their mandate is to track the index as implemented.
Analysts, including JPMorgan in prior research cited by market outlets, have estimated that an MSCI exclusion could drive roughly $2.8 billion in passive stock outflows. That estimate refers to selling pressure in Strategy’s equity, not forced sales of the company’s bitcoin. Some commentary has also floated much larger numbers if other major index providers adopt similar eligibility screens. Treat those as tail risk rather than a base case, because they depend on decisions by other providers that are not part of MSCI’s November implementation.
Bitcoin itself adds complexity. In recent sessions bitcoin has traded around the mid-$70,000s, and public flow trackers and market reporting have shown net outflows from U.S. spot bitcoin ETFs on multiple days early in November. Strategy’s equity premium or discount versus the value of its bitcoin and operating business can compress quickly when BTC is under pressure, and that matters because its capital-raising model is sensitive to how the market values that wrapper.
Bitcoin’s price pressure ripples unevenly across companies with crypto exposure. Block’s results show how bitcoin can dominate a company’s revenue line while contributing almost nothing to its gross profit.
How Professionals Might View It
Experienced traders treat mechanical flow events differently from fundamental ones. The selling pressure here is not discretionary. It is rules-based, and the rules have a schedule. That means the trade is about timing and absorption, not about whether MSCI’s classification is right or wrong.
Price action so far has suggested many participants are waiting for the final roster rather than fully pricing a worst-case outcome. That patience is rational. The November 11 list either confirms a deletion or removes the overhang entirely. Positioning heavily before that confirmation means carrying uncertainty you do not need to carry.
The prospect also matters beyond one ticker. If MSCI applies a stricter non-operating screen to bitcoin-treasury-style companies, the read-across is straightforward: index membership can be a source of steady, non-discretionary demand, and losing it can raise the financing bar for companies that rely on equity issuance to expand crypto holdings. Other crypto-treasury names have been discussed by market observers in the context of the same rule change, though each company’s path depends on MSCI’s final determinations and on the company’s own financial profile.
What Comes Next
From November 11 to the close on November 30 is 19 calendar days, but only about 13 U.S. trading sessions. If Strategy is on the final list, the actionable question becomes how much selling the market can absorb and at what price. The practical detail is not the headline dollar estimate. It is the day-by-day ability of the market to clear incremental supply, especially as passive flows often concentrate into the final sessions before an effective date.
Watch the spread between MSTR and bitcoin’s spot price. If the equity discount widens materially before November 30, that tells you absorption is struggling. If the discount holds, it tells you the market found buyers before index trackers finished adjusting.
The Trader’s Lesson
Mechanical flow events have one property that most catalysts lack: the size and timing are at least partially knowable in advance. That does not make the trade easy, but it does make the analysis more tractable. When you can bracket how many shares must move and by when, the edge comes from understanding who the natural buyers are and whether they will show up at current prices. November 11 confirms the roster. November 30 is when you find out if the buyers were there.