Dear Reader,
Billionaire Sam Altman recently made an extraordinary admission.
“I basically just took all my liquid net worth and put it into these two companies.”
This was not a casual investment.
Altman, CEO of OpenAI – creator of ChatGPT – placed nearly everything he could readily access behind a new, emerging field…
A new fusion with AI and another branch of science…
One Elon Musk himself said is capable of “Jesus level miracles.”
See, Elon was not finished with Space X. He has been quietly building yet another company – in this field…
And like all other investments before it…
Tesla, OpenAI, SolarCities, and PayPal…
Elon enters a new space…
Then capital floods in and new investment opportunities appear around him.
Former Fox Business analyst Matt McCall calls this pattern the “Musk Stampede.”
Elon innovates…
Capital floods in…
And dozens of new opportunities are created.
So what is Elon building now?
And how could ordinary investors take advantage of the opportunity developing around it?
Matt recently sat down with former Fox anchor, Corrina Sullivan, to share his findings.
Click here for the full presentation.
To your wealth,
Stephen Prior, Publisher
Monument Traders Alliance
P.S. A fast approaching catalyst beginning November 14th could bring this emerging field much closer to the mainstream.
European Banks Just Broke Their Most Reliable Trade of 2026
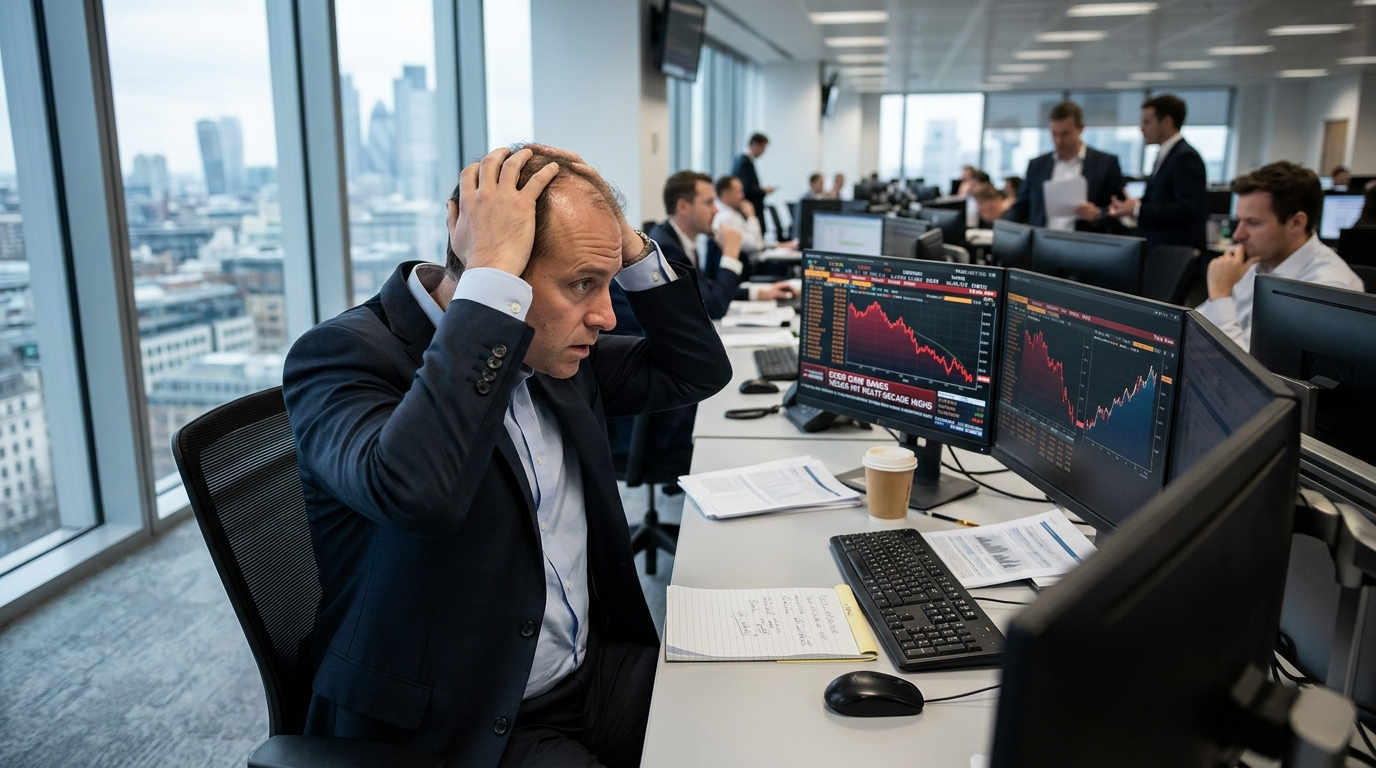
For most of 2026, owning European bank stocks when yields rose was the obvious trade. Higher rates meant wider lending margins, fatter profits, and a sector that seemed to have the macro tailwind permanently at its back. Then this week happened, and that relationship snapped.
European shares started the final quarter of the year on a downbeat note Thursday, with heavyweight banks marking sharp declines as global government bond yields hit multi-year highs. The pan-European STOXX 600 closed 1.3% lower on October 1, marking its biggest one-day drop in three weeks, and touched its lowest level in more than three months. By the time Friday’s partial rebound closed the books, European banking stocks registered their biggest weekly fall since April, hurt by concerns about higher interest rates denting the economy.
Banks registered their sharpest daily fall since March 3, down 3.7%. The names hit hardest were the sector’s former darlings. In the U.K., HSBC and Barclays were each down about 4% on the day, and Lloyds fell about 4.5% as jitters mounted about Britain’s finances ahead of this month’s budget. Across the continent, the same pattern repeated. Germany’s 10-year government bond yield, the euro area’s benchmark, touched 3.6526% earlier this week, its highest level since June 2009. Milan’s FTSE MIB led the regional decline with about a 2.2% drop, while the Italy-Germany sovereign bond spread widened to about 118.5 basis points amid mounting fiscal anxieties across the eurozone.
What Changed
The rate-sensitive thesis for banks rested on one assumption: higher yields expand net interest margins faster than they create credit risk. That held through most of the hiking cycle. What markets are pricing now is the other side of the equation. Rising government bond yields reduce the value of the sovereign debt that banks hold and raise fears about loan quality, outweighing the benefit of higher lending margins. Add Brent crude trading back above $100 and the US 10-year Treasury hitting 5.34% intraday on October 1, and institutional investors concluded the risk calculus had flipped.
This is not a subtle signal. When a sector that has spent the year benefiting from the very factor now punishing it reverses sharply over five sessions, the market is telling you the old logic no longer holds. BNP Paribas, Santander, Deutsche Bank, and UniCredit all ended the week well below where they began it, despite yields doing exactly what bulls would have predicted.
Meanwhile, One Stock Did the Opposite
While banks sold off, Infineon told a completely different story. Infineon Technologies stock surged to about €62.7 on Friday, topping the DAX as the session’s best performer. By the close, Infineon finished around €64.6, up about 8.8% on the day. The catalyst was specific and earnings-linked: Micron Technology’s stronger-than-expected quarterly results, released late on September 30, highlighted surging AI-driven memory demand and lifted chip stocks across Europe. At an investor conference on October 1, Infineon said AI-related revenue reached about $1.6 billion in the current fiscal year, more than double the prior year.
Infineon’s move mattered not just for its magnitude but for its source. It was driven by a real earnings catalyst in a sector with genuine demand growth, not by macro rotation or short covering.
The Trader’s Lesson
The most dangerous assumption in trading is that a sector will keep responding to a driver the way it always has. Correlations are not laws. European banks spent 2026 being rewarded every time yields rose. This week, they were punished by the same move. The market’s interpretation of the data changed, even though the data itself did not.
The discipline here is straightforward: when a sector stops trading the way its thesis predicts, that is new information. It is not a reason to immediately reverse, but it is a reason to reduce conviction, tighten risk, and wait for confirmation that the old relationship is either restoring itself or genuinely broken. Chasing the trade that worked last quarter, after the market has clearly stopped agreeing with it, is where most of the damage gets done. Persistently high rates raise borrowing costs for companies and mortgage holders, while increasing the interest burden for governments. The bank trade was built on one half of that sentence. The market just started pricing the other.