October 5, 2026
Bonus Content: France Now Borrows More Expensively Than Italy. Your S&P Futures Felt It This Morning.
Patriots’ Most Trusted Gold Company
Since 2000, Gold Is Up 1,395%. The S&P Is Up 425%.
For U.S. savers age 55+ with $50,000 or more in an IRA, 401(k) or savings. Free of charge, no obligation to buy anything.
Same twenty-six years. Same two dot-com and 2008 collapses. Two very different lines on the chart.1,2 Most Americans have never seen them put side by side – and almost nobody was told they are allowed to hold the better-performing one inside a retirement account.
Two lines on the same chart
In December 1999 gold traded near $290 an ounce and the S&P 500 closed the year at 1,469. Since then gold has multiplied roughly fifteen times over. The S&P has multiplied about five.1,2
Be fair about the comparison: that S&P figure is the price index and does not include reinvested dividends, which would lift it meaningfully.2 Even allowing for that, the gap over a quarter century is not a rounding error.
The reason has less to do with gold than with the dollar. Over those same twenty-six years the money supply expanded, two crises were met with emergency printing, and the national debt crossed $40 trillion. Gold did not get more valuable so much as dollars got less so – and gold is the one asset that cannot be issued by anybody.
Right now gold sits below its January 2026 peak while the world’s central banks keep adding more than a thousand tons a year, and published bank targets still run from roughly $4,900 to $6,300.3,4 Those are opinions, not promises. But a quiet stretch is a better time to read up than a panic. Get the free 2026 Gold IRA Guide.
The free 2026 Gold IRA Guide walks through exactly how a rollover from an IRA, 401(k) or TSP works, which metals the IRS allows, how insured depository storage works, and the mistakes that cost retirees the most. It is free and it takes about thirty seconds to request.
Claim Your Free 2026 Gold IRA Guide →
Rock legend Ted Nugent and former White House Press Secretary Sean Spicer are official endorsers and clients of Bishop Gold Group. 10 years in business ⢠5-star rated on Trustpilot and Google ⢠Mint Authorized Dealer
Prefer to speak to someone? U.S.–based specialists, no pressure, no jargon.
Mon-Fri ⢠7am-5pm PT
Sources
1 LBMA gold price, 31 December 1999 ($290.25/oz) to September 2026. Past performance is not a guarantee of future results.
2 S&P 500 price index, 1,469.25 close on 31 December 1999 to 7,707 in September 2026 – a price-only comparison that excludes reinvested dividends, which would raise the S&P figure materially.
3 Published year-end gold price forecasts as reported 2026: Goldman Sachs, J.P. Morgan, UBS and Bank of America, spanning roughly $4,900–$6,300/oz. Analyst forecasts are opinions, not guarantees.
4 World Gold Council, Gold Demand Trends, annual central bank net purchases 2022-2024.
Past performance is not a guarantee of future results. Precious metals are volatile and can decline in value. This comparison is historical and is not a prediction or a recommendation to buy or sell any asset.
France Now Borrows More Expensively Than Italy. Your S&P Futures Felt It This Morning.
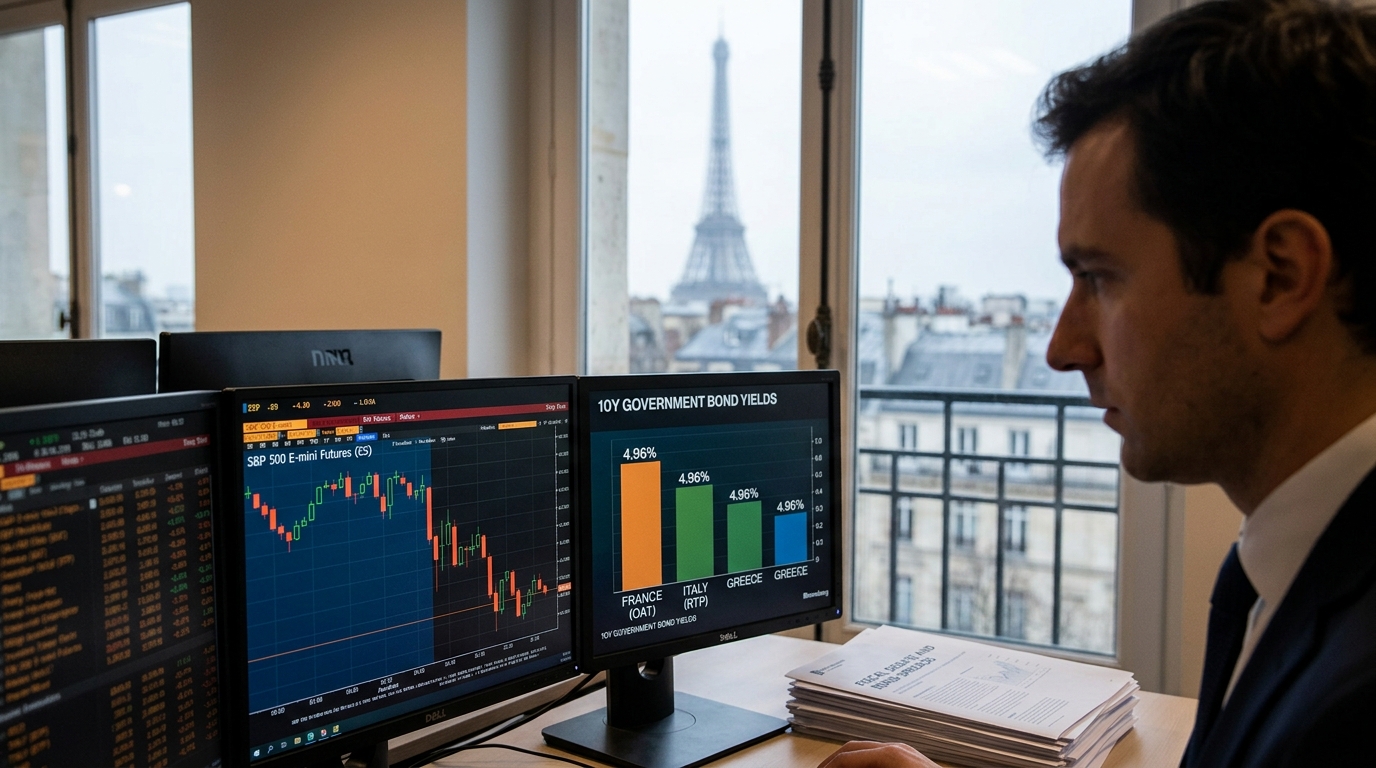
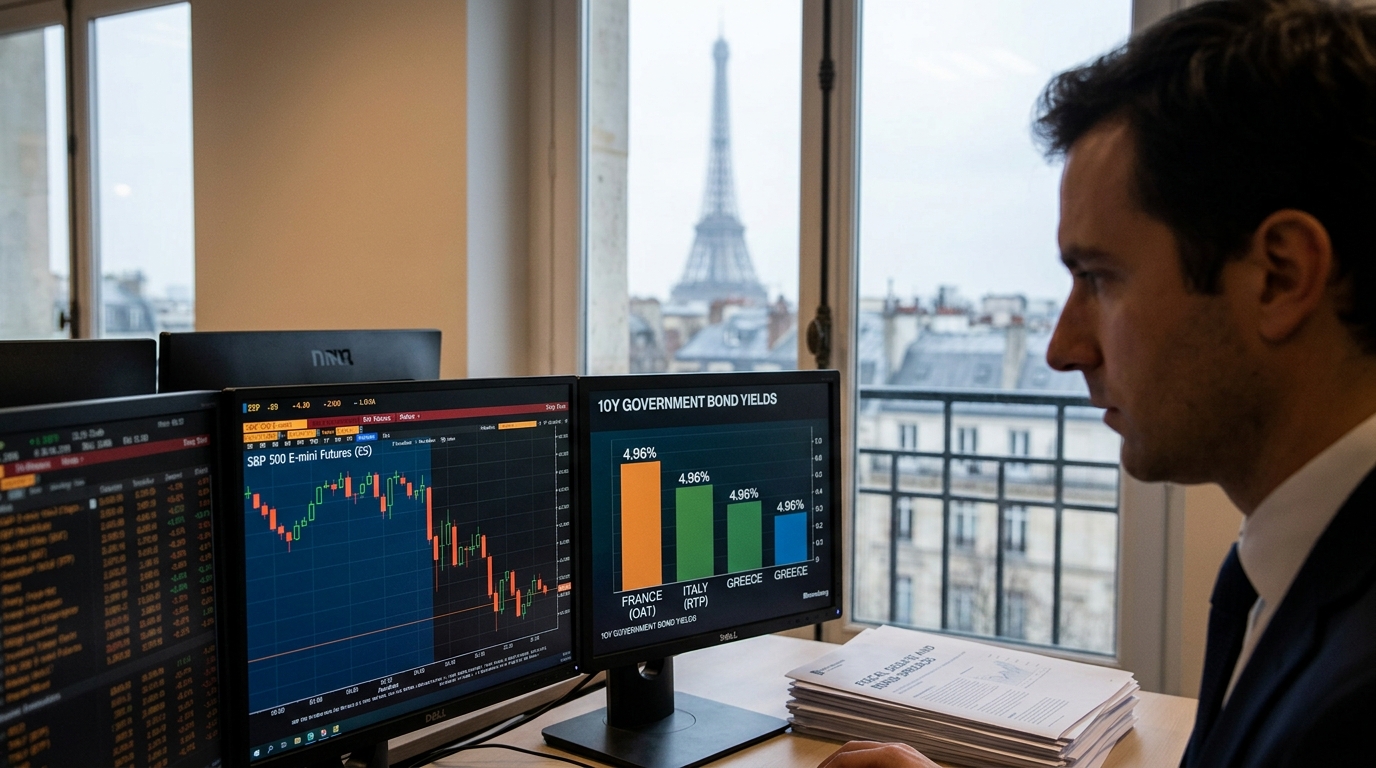
This morning’s equity futures decline had nothing to do with earnings, Fed policy, or last Friday’s jobs report. The proximate cause was a French bond market that is now pricing Paris as a bigger credit risk than Rome or Athens.
France’s OAT-Bund spread widened sharply after the October 1 budget unveiling. France’s 10-year borrowing costs rose to about 4.96%, the highest level since July 2002. Italy carries debt-to-GDP of roughly 140% and Greece higher still, yet both are now viewed as more creditworthy on a relative basis. The bond market is not making a statement about solvency. It is making one about political credibility.
The euro slid to a 17-month low on Monday as fiscal worries in France stoked contagion fears across the region, helping the dollar shrug off soft US jobs data that had dented near-term rate hike expectations. Futures traders who went home Friday feeling good about payrolls walked in this morning to find the rally gone.
What the Budget Actually Says
Prime Minister Sébastien Lecornu presented a belt-tightening budget for 2027, with savings coming from freezing wages in the public sector and limiting pension increases, alongside targeted tax measures. France’s independent fiscal watchdog said the deficit-reduction effort was still “limited” given the size of the task.
The government is targeting a €54 billion fiscal consolidation effort to reduce the budget deficit to 5% of GDP in 2027 from an expected 5.4% this year. Of that total, €43 billion is new measures for 2027, with the remainder coming from measures already in the pipeline. The draft will be debated through October ahead of a November 17 vote.
The market is skeptical those numbers survive parliament. Brown Brothers Harriman’s Elias Haddad doubts the proposal will clear parliament without significant concessions, notes that France’s own fiscal watchdog called the growth assumptions “optimistic,” and says a rollover of the 2026 budget is the most likely outcome, which could push the deficit from 5.4% toward 6.0% in 2027.
Why Professionals Are Watching French Banks
Banks like BNP Paribas, Crédit Agricole, and Société Générale hold large quantities of OATs on their balance sheets, and their share prices typically fall when the spread widens sharply.
ING strategists forecast the OAT-Bund spread will sit between 100 and 125 basis points in the coming months, and note the European Central Bank may be reluctant to step in with bond purchases while it remains focused on inflation risks. No ECB backstop, a fragmented parliament, and a presidential election looming in April 2027 combine to make the November 17 vote the most important near-term catalyst for European financial stocks.
The Chain From Paris to Your Position
Most traders running S&P exposure are not thinking about French fiscal arithmetic. They should be, because the transmission mechanism is direct. Whenever risk rises, investors still tend to favour the United States and move away from Europe, and that is what is happening now, reflected in the performance gap between the Stoxx Europe 600 and the S&P 500. Rising sovereign stress in France pressures the euro, lifts safe-haven dollar demand, and pushes investors into US equities as a relative trade, not because US fundamentals improved overnight.
A debt burden expected to reach about 122% of GDP next year and political uncertainty ahead of the April 2027 election are driving up interest costs, with officials projecting a €91 billion interest bill in 2027. That is money unavailable for anything else, and markets know it.
The Trader’s Lesson
Sovereign stress rarely stays in its lane. The lesson from this morning is that a bond market moving in Paris can erase an equity rally built on a Washington data release before most US traders have poured their first coffee. Experienced traders do not treat macro as background noise. They ask, every session, where the pressure point is and how it travels. Right now the pressure point is the OAT market, the November 17 vote is the event risk, and French bank equities are the most direct equity expression of that risk. Watch those three in sequence.