Friday’s September payrolls number was supposed to settle things. It didn’t. It just changed which questions matter most heading into the week.
Employers added just 29,000 jobs in September, against economist forecasts around 90,000. Markets had been pricing roughly a 65% probability of a hike at the October 27–28 meeting just days earlier. After Friday’s report, that number dropped to around 23%. Treasury yields initially fell on the release before reversing later in the session. TLT caught a bid; SPY rallied on the rate-relief trade. Clean moves, clean logic. And almost certainly incomplete.
Why the Manufacturing Number Wasn’t the Last Word
The ISM prices paid index jumped 6.8 points to 77.9 in September, rising from 71.1 in August and close to its level at the beginning of the Iran war. No industries reported paying decreased prices for raw materials in September. That reading landed October 1, two days before the payrolls miss. Markets largely moved on, treating the soft labor data as the dominant signal.
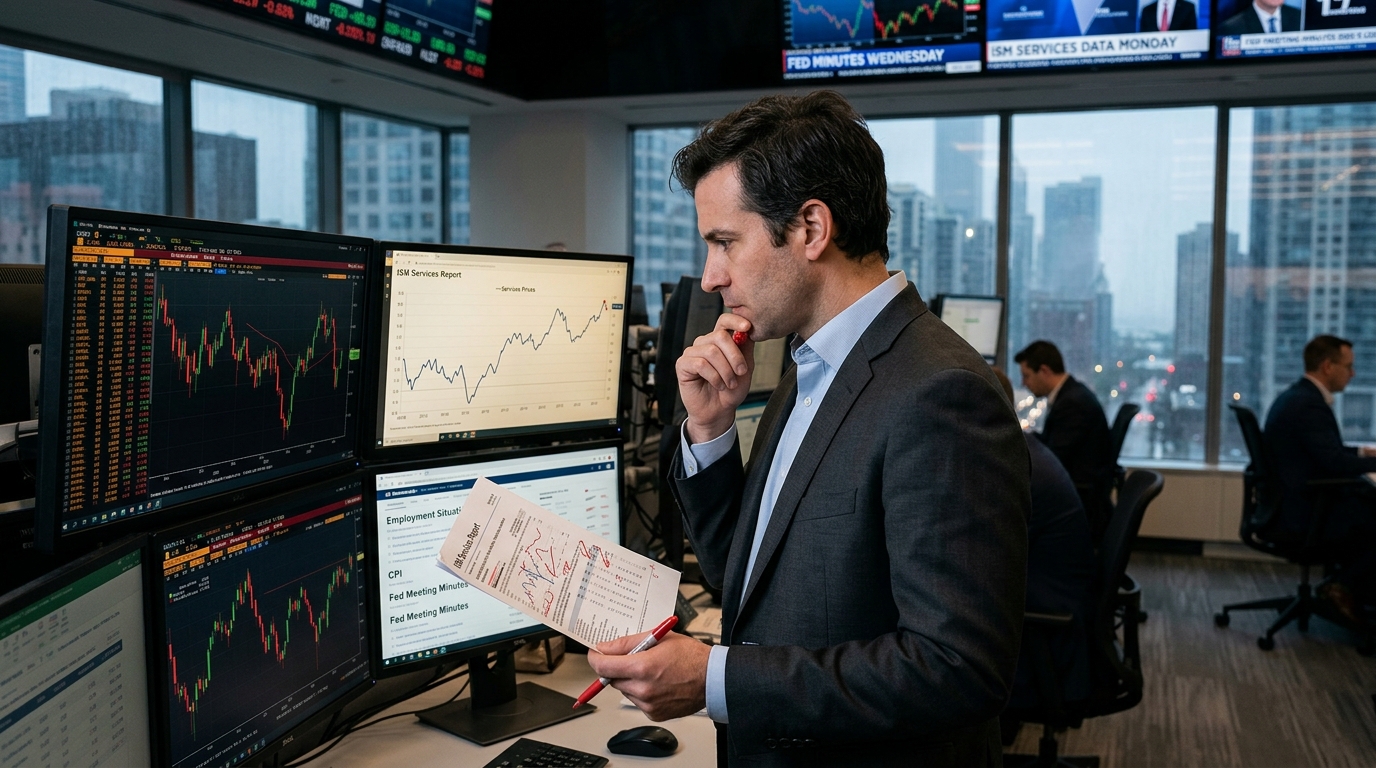
That framing has a problem. Manufacturing represents roughly 10% of U.S. employment and about 11% of GDP. The services sector, which covers everything from restaurants and hospitals to finance and professional services, is where wage pressure propagates and where consumer-driven inflation lives longest. The ISM services prices-paid sub-index, previously at 72.6, is where tariff and wage pressure show up last and leave slowest. That sub-index is what traders should be watching when ISM services prints Monday at 10 a.m.
Monday’s Report: The Number Inside the Number
The ISM services index is forecast to come in at 55.7, up from August’s 55.4, and analysts will watch its prices paid component closely after the manufacturing survey’s prices paid index came in at 77.9, well above expectations of 72.3. In August, the services prices paid sub-index reached 72.6, the highest since August 2022, with ISM noting fuel as the lone commodity reported down in price.
If Monday’s services prices paid comes in at or above 73, the payrolls story gets complicated fast. A reading like that, combined with the 77.9 on the manufacturing side, tells the Fed that cost pressure is broad rather than confined to one corner of the economy. It also tells the bond market that the 10-year near 5.2% may not be pricing enough risk. A hot services prices sub-index accelerates that concern into this week rather than next.
Wednesday’s Minutes: A Document Written Before the Payrolls Shock
The FOMC minutes from the September 15–16 meeting publish Wednesday at 2 p.m. Eastern. The challenge with reading them is a timing one. The Federal Reserve raised rates 25 basis points to 3.75%–4.00% following its September 15–16 meeting, its first rate increase since 2023.
The committee voted with August’s payroll print in front of it. Friday’s 29,000 was weeks away. After the soft payrolls number, the minutes tell traders how much of the September decision was inflation-fighting conviction versus insurance. That distinction is what should anchor how you read every line. If the minutes reveal that multiple participants were already uncomfortable with the pace of tightening, the weak payrolls report is confirmation they’ll press for October patience. If the language is uniformly hawkish, inflation-centric, and unbothered by labor-market risk, then the payrolls miss may have bought less breathing room than the market-implied hold probability suggests.
The dot plot already signaled this is a campaign, not a correction: sixteen of eighteen participants penciled in at least one further increase. The minutes will reveal whether that consensus was fragile or firm.
The Trader’s Lesson
Markets priced Friday’s payrolls as a verdict. Two data points arriving this week could reopen the argument. The practical discipline here is sequencing: resist repositioning around Wednesday’s minutes until you’ve seen Monday’s services prices paid figure. One soft labor report doesn’t neutralize a 77.9 manufacturing prices index if the services economy is running the same cost pressure. December already carries elevated odds of a hike in Fed funds futures, with CME’s FedWatch showing it as the market’s favored timing for another move. Whether October is truly off the table, or just deferred, is a question this week’s data answers, not last week’s.