October 19, 2026
Bonus Content: AT&T Reports Wednesday. One Number Will Decide the Reaction.
Dear Reader,
What I’ve uncovered hidden in the market is making me more worried than I’ve ever been in five decades …
It keeps me up at night …
You need to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
What is coming could be devastating to anyone with any money in the stock market. It could also be devastating to anyone with a bank account, annuity or money in “safe assets.”
I’m Dr. Martin D. Weiss. I’m a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes before they happened.
What I’m seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it’s a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
AT&T Reports Wednesday. One Number Will Decide the Reaction.
AT&T reports third-quarter results before the market opens Wednesday, October 21, and the stock’s reaction will hinge on a single operating question: can the company add customers in its newly acquired Lumen fiber territory without surrendering the pricing that makes those customers worth having?
What Happened
AT&T is scheduled to report third-quarter 2026 earnings on October 21, before the opening bell. The Zacks consensus estimate sits at $31.68 billion in revenue and 61 cents per share. That number reflects a market broadly comfortable with AT&T’s execution, but the number that matters more on Wednesday is not EPS.
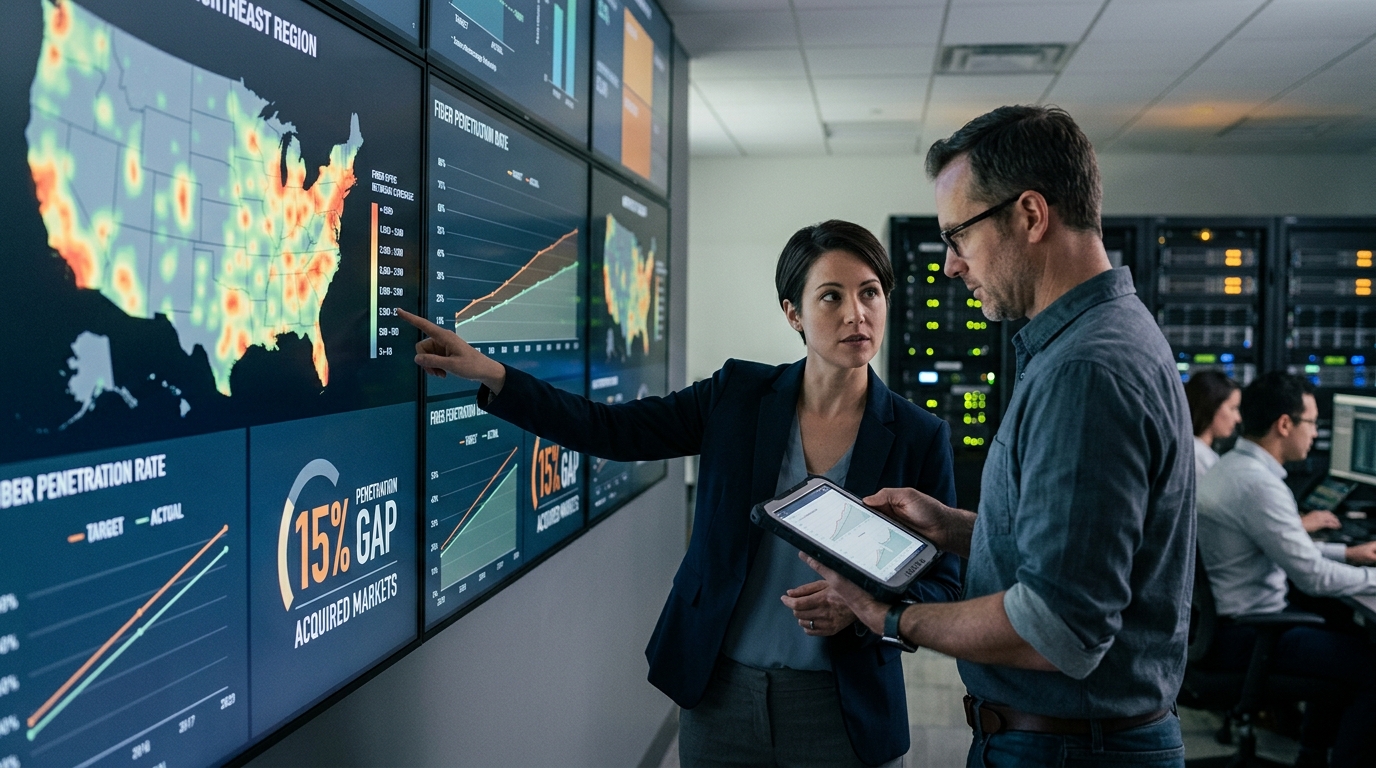
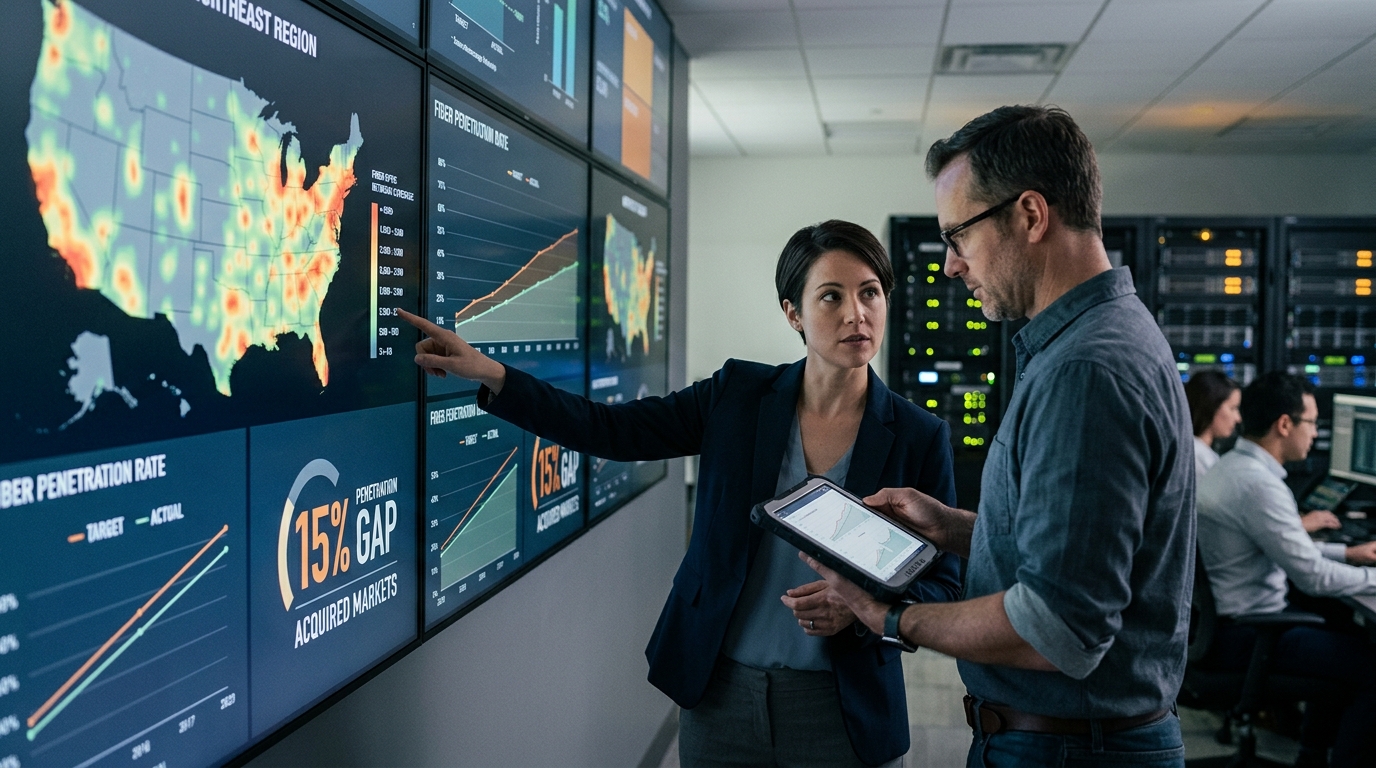
AT&T acquired about 4.5 million consumer fiber locations from Lumen Technologies, and they arrived far less penetrated than its own markets. CFO Pascal Desroches updated those figures at the Bank of America Media, Communications and Entertainment Conference in September: “We acquired about 4.5 million locations, consumer locations from Lumen. They were about 25% penetrated as compared to 40% in our owned and operated.” Wednesday is the first quarterly report since his September update, and the test is whether the gap is narrowing without too much fiber pricing given up.
Why It Happened and Why the Price Question Is Central
Closing a 15-point penetration gap sounds like a straightforward growth opportunity, but the Q2 results showed how quickly the math turns complicated. Fiber ARPU declined 1.3% year over year in the second quarter, primarily reflecting the full-quarter impact of the Lumen transaction, whose subscribers carry lower average revenue. Excluding the Lumen footprint, fiber ARPU was approximately flat year over year. That distinction matters because it tells you the dilution is structural to the acquired base, not a sign of broader pricing pressure.
Consumer chief Jenifer Robertson signaled AT&T would “take a little bit of fiber ARPU dilution over here to grow the total value of the household now and over time,” so Lumen gains could come with lower fiber revenue per user. Traders should watch whether that trade-off held in Q3 or whether it widened. Dilution that grows faster than the customer count is the scenario the market will punish.
The Lumen ramp also clouds AT&T’s convergence target. The ramp clouds AT&T’s 50% convergence target for internet customers who also take its wireless, because Desroches noted the denominator of that ratio is increasing significantly, so the rate can stall even as converged households grow. Bank of America analyst Michael Funk put the share of all internet customers also taking AT&T postpaid wireless at 42.5% after Q2, and 45% outside the Lumen footprint. A headline convergence rate that ticks down despite genuine customer additions would be misread as weakness by anyone not watching the Lumen footprint separately.
What Comes Next
The Lumen earnings question does not exist in isolation. AT&T agreed this month to sell its Mexican wireless business to a consortium owned equally by Grupo Televisa and Fintech Holdings for $2 billion in cash at closing, subject to certain adjustments, plus additional contractual and contingent benefits. AT&T said the deal will let it concentrate its focus and resources on the U.S. market, where the company is pressing ahead with investments in 5G and fiber infrastructure. That capital clarity is constructive heading into Wednesday’s call, but investors will want to hear management reaffirm how the $2 billion proceeds interact with the debt reduction path. Separately, AT&T has said proceeds it expects to receive at closing of its fiber joint venture are intended to help it reach its net debt target in the 2.5-times range within approximately three years.
Adding a layer of noise: Bernstein downgraded AT&T to market perform from outperform days before the report, citing competitive pressure from SpaceX’s expansion into broadband and wireless. That downgrade is a longer-term concern, not a Q3 catalyst, but it frames investor sentiment going in. The stock closed at $23.50 on October 15, meaning it heads into Wednesday already carrying the weight of the downgrade.
The Trader’s Lesson
Earnings reactions are rarely driven by the headline number when a structural story is in progress. AT&T’s EPS will almost certainly be within a few cents of consensus in either direction. The real read is in the operating metrics: Lumen penetration progress, fiber ARPU trajectory, and any update on the convergence rate in those markets specifically. Experienced traders know that when a company is mid-integration, the market is essentially pricing the ramp, not the quarter. Miss the ramp, and the dividend yield becomes the whole argument. Confirm it, even modestly, and you have a case that the gap closes faster than the several quarters management has been guiding toward. Watch for that distinction on Wednesday morning, before the broader market opens and the noise takes over.