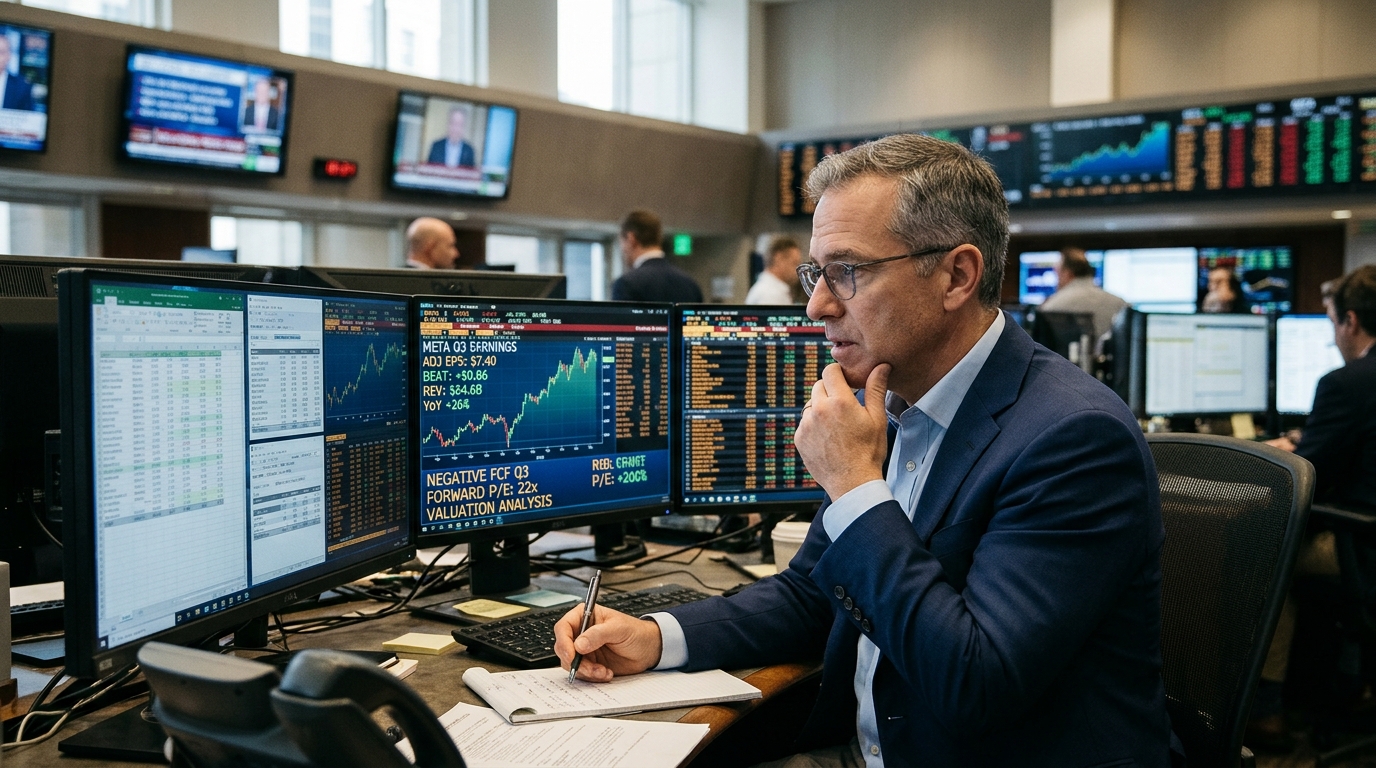
Three days after Meta reported Q3 results, the valuation debate is sharper than it has been all year. On the surface, the quarter was strong. Meta reported adjusted earnings of $7.40 per share, beating the $6.54 consensus by $0.86, while revenue rose 26% year-over-year to $64.60 billion, above the $63.34 billion analysts expected. But that headline number hides a cash flow picture that complicates any simple answer about price.
Meta posted negative free cash flow in Q3 as AI infrastructure spending hit $34.91 billion, outpacing its $32.79 billion in operating cash flow. Management then raised the full-year capital expenditure outlook to $135 billion to $145 billion, narrowing the range from a prior estimate of $130 billion to $145 billion. That upper bound is roughly double the $72 billion capex level the company guided to for 2025.
So: expensive or not?
The conventional answer leans toward no. Although Meta’s stock is approaching $800, in terms of earnings its valuation is not enormous. It trades at about 28 times trailing earnings, but on a forward price-to-earnings basis, the multiple is about 22.
The earnings growth trajectory supports that view. But the harder question is whether those earnings estimates hold up under the weight of the spending cycle. Investors still want clarity on how that spending translates into shareholder returns.
Meta paid out $1.36 billion in dividends during Q3. With free cash flow in negative territory, that payout effectively came from reserves rather than the quarter’s leftover cash.
The bull case rests on Muse. According to Apptopia, Muse reached 10 million downloads in 32 days, capturing a 32.9% share of U.S. generative AI app downloads, while ChatGPT’s share declined to 26.4%. Citi estimates the product could generate more than $27 billion in annual revenue by 2030, a forecast that rests on whether consumers will trust Muse to spend their money.
Meta carries a market cap of about $1.6 trillion. OpenAI has publicly said it valued the company at $852 billion in a March 2026 funding round, and more recently has been reported as seeking a higher valuation. Anthropic has also been reported at valuation levels well below $1.5 trillion. There is plenty of debate on whether those pure-play labs are properly valued, but what is clear is that Meta’s own lab, which is now producing frontier-level models, is not being valued anywhere near those levels. That embedded optionality is real, and the forward multiple does not capture it.
The risk the bulls wave away too quickly: capex at roughly $140 billion per year is an extraordinary number even for a company of Meta’s size. If AI investment does not produce proportional advertising revenue improvement, margin compression could weigh on the stock for 12 to 18 months. Expensive is the wrong word for Meta right now. Contingent is more precise. The multiple is reasonable if Muse converts; it is a problem if the spending cycle extends without a matching revenue inflection.