November 4, 2026
Bonus Content: Two Reports in Two Hours Could Shift December Rate Odds
Silver and gold have delivered strong sector returns, with early-stage small-cap explorers positioned for outsized upside relative to the broader metals market.
The focus here is on early-stage, small-cap discovery stories that are only just beginning to unfold.
The early-stage opportunity is taking shape across a historic North American silver-gold district that produced high-grade metals at surface for generations, yet was never explored as a unified system.
The district’s potential went untested for one structural reason: the land package was highly fragmented and no single operator controlled it end to end.
That has now changed.
For the first time, this small-cap explorer has consolidated the entire district under one ownership structure — enabling modern geology and drilling to test the system properly from surface to depth across kilometers of previously undrilled mineralization.
The technical setup is developing quickly.
Phase-2 drilling is under way, with a near-term pipeline of results expected as the discovery picture sharpens across the drill program.
There is a second component as well.
A second nearby district-scale silver-gold asset extends the exploration runway and adds further optionality to the program.
A complimentary online report covering all the details is now available, including:
✔ A newly consolidated district-scale silver-gold system in North America
✔ What the first drill results are already confirming
✔ Which targets are scheduled for drilling next
✔ How a second district-scale asset expands the discovery upside
✔ Key 2026–27 catalysts as drilling intensifies
The report also includes an in-depth interview with the company’s president & CEO, offering a firsthand account of where the program is headed and the rationale behind the current timeline.
Access the full report here and review why this sub-US$1 silver-gold explorer represents one of the more compelling early-stage setups heading into 2026–27.
Two Reports in Two Hours Could Shift December Rate Odds
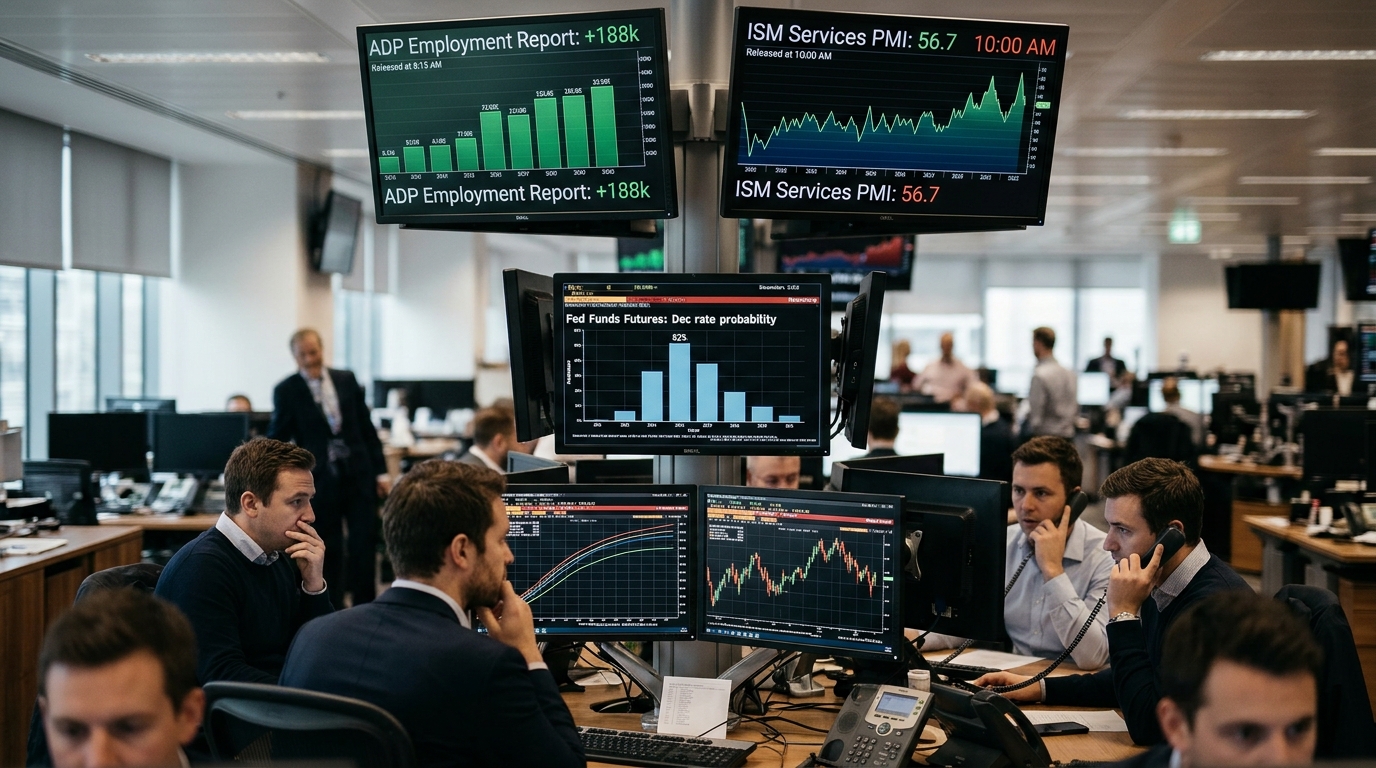
The bond market came into Wednesday with an unusual configuration. Treasuries rallied through the back half of last week, with safe-haven demand pulling the 2-year yield down roughly 6 basis points to about 4.592%, as investors bid up bond prices in their search for safety. By early Wednesday morning, the 2-year was near 4.55% based on Tuesday’s close. Now, within the space of 105 minutes this morning, two labor and inflation readings will either confirm that rally or erase it.
The October ADP National Employment Report hits at 8:15 a.m. ET. Consensus is looking for 69,000 new private-sector jobs in October, down from 90,000 in September, which itself was a sharp rebound from August’s 36,000. Then, at 10:00 a.m. ET, ISM releases its October Services PMI, and that is the number traders should be watching more closely.
Here is why the ISM print carries the most weight. September’s prices-paid index came in at 74, its highest reading since July 2022, rising 1.4 points from August’s already elevated 72.6. In ISM’s write-up, fuel was cited as a notable pressure point among inputs reported higher. Employment within the services sector climbed back to 50.1, ending two straight months of contraction. The result was a Fed input-cost gauge at a four-year high combined with an employment base that has stopped shrinking. That is a difficult combination for anyone arguing the Fed is done.
Fed funds futures imply a December 9, 2026 hike is still the base case, with odds around the low-80% range as of Wednesday’s pricing, depending on the cut of futures data used. That expectation firmed after September JOLTS job openings came in at 7.523 million, up 333,000 on the month. The 2-year yield is exquisitely sensitive to any shift in those odds right now. Q3 GDP came in at 3.4%, and September core PCE ran at 3.1% year-over-year, so the macro case for another quarter-point is not fragile. What is fragile is the market’s short-term positioning after a flight-to-safety bid that pulled yields lower for reasons having nothing to do with inflation.
The vote count at the October meeting sharpened that sensitivity considerably. Cook and Hammack dissenting for a hike while the majority held tells you exactly where the FOMC’s internal pressure is concentrated.
That creates a two-way problem this morning. A soft ADP, say 50,000 or below, would likely extend the bond rally and push the 2-year lower. But if ISM’s prices-paid component comes in at or above 74 again, that number will override the ADP signal within minutes. Services inflation at a four-year high, confirmed in back-to-back months, is exactly what keeps hawks on the FOMC like Governor Cook and Cleveland’s Hammack in a hiking posture. Both Cook and Hammack preferred a quarter-point hike at the October 27-28 meeting itself, and were outvoted.
Experienced traders will not treat the two releases as independent. The sequence matters. A strong ADP combined with a strong ISM would push December hike expectations higher, with the dollar and yields likely recovering while rate-sensitive equities face renewed pressure. The reverse scenario, weak ADP and a prices-paid retreat, hands the bond bulls something to work with. The dangerous scenario for anyone positioned ahead of Friday’s payrolls is a split reading where ADP disappoints but ISM prices surprise to the upside. That combination leaves December fully intact as a live hike meeting while removing the cleaner labor-market rationale for holding short duration.
The lesson worth internalizing today is that two data releases can tell a coherent story or a contradictory one, and the market’s reaction to the contradiction is often more revealing than either number alone. Watch how the 2-year settles between 10:30 and 11:00 a.m., after both prints have been absorbed. That level, more than the initial spike in either direction, will tell you what the bond market actually believes about December 9.