For years, cheap Chinese goods were the quiet disinflationary force that let central banks in the West keep rates lower for longer. That era ended when the US-Iran war drove oil through $100 a barrel earlier this year. Monday’s data will confirm how thoroughly the dynamic has reversed.
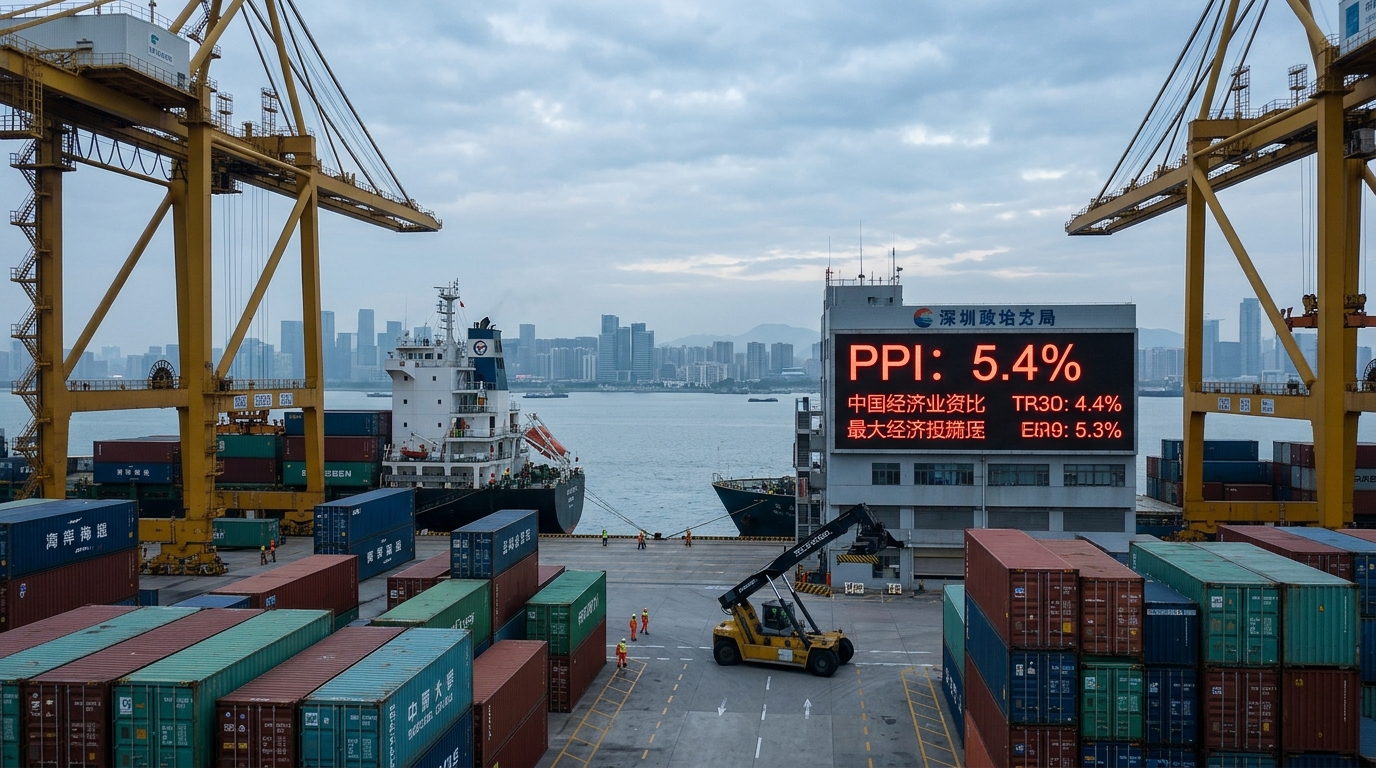
China releases its October consumer price index and producer price index on November 9, with the CPI forecast at +0.8% year-on-year and the PPI expected to come in at +5.4%, up from September’s 5.0%. That would mark a fresh acceleration in factory-gate costs and extend a run that began in earnest after China’s PPI turned positive in March.
September’s PPI already came in at 5.0% year-on-year, the fastest growth since June 2022. The acceleration was driven primarily by rising international crude oil and non-ferrous metals prices, alongside changes in supply and demand in energy and raw material industries. An October print at 5.4% would confirm the trend is not stalling.
The structural story matters as much as the number. Energy prices, driven skyward by supply disruptions linked to the Iran war and tensions around the Strait of Hormuz, have made it dramatically more expensive to manufacture across much of Chinese industry. China endured 41 consecutive months of producer price deflation before the index finally turned positive in March 2026. Those 41 months of falling factory-gate prices were a gift to global goods disinflation. That gift has been revoked.
What makes this week’s sequence especially sharp for traders is the timing. October inflation data is expected to highlight the divergence of subdued consumer prices and firmer industrial prices, with CPI easing to 0.8% year-on-year from 0.9% in September. Consumer spending has remained subdued but stable, with continued declines in pork prices weighing on food costs while higher fuel prices constrained discretionary spending. Beijing’s factories are paying more; Chinese households are not absorbing that cost. That gap is precisely where the global transmission risk lives: manufacturers who cannot push costs downstream may eventually route them into export prices instead.
US October CPI follows on Tuesday, November 10, expected to rise 0.3% month-on-month, with the core index up 0.2%, drawing attention as a potential deciding factor for the December FOMC meeting. The two reports land within roughly 32 hours of each other, which means Monday’s China data will shape how traders position ahead of Tuesday’s number.
The Cleveland Fed model projects headline US CPI at 0.24% month-on-month and core at 0.21%. Following a beat on October nonfarm payrolls, CME FedWatch-based estimates show markets pricing roughly a 75% to 80% probability of a 25 basis point rate hike in December. Monex’s macro research director Nick Rees argues that unless October CPI is significantly lower than expected, or the November employment report shows clear weakness, the market is expected to have almost fully priced in a 25 basis point hike by the time of next month’s meeting.
The Fed raised its target range to 3.75% to 4.00% in September 2026 and held in October. A hot US CPI on Tuesday, arriving one day after a Chinese PPI that signals imported cost pressure is building, makes it harder for any Fed official to argue the December hike is premature.
Traders watching China-exposed positions should also note what follows later in the week. October trade data, due November 10, is the defining data point for the fourth quarter. China’s official manufacturing PMI fell to 49.3 in October, sliding back into contraction territory after September’s rebound, signaling that factory activity softened once the front-loading impulse faded.
The Trader’s Lesson
When two major data releases fall within 32 hours of each other and both touch the same policy variable, the first report resets expectations for the second. Monday’s China PPI is not an isolated overnight event; it is the opening argument in a two-day case that will either cement December hike odds near 80% or introduce doubt that lets risk assets breathe. Watch how Treasury yields and the CNY move in the hours after the 1:30 GMT release. Those two instruments will tell you how professional money is interpreting the number before Tuesday’s US data even hits the screen.