October 18, 2026
Bonus Content: Japan Called 160 a Red Line. The Yen Has Tested It Again.
Gold and silver are in a powerful bull market – and one ultra-low-priced small-cap precious metals company has quietly built a unique way to capitalize on this historic uptrend.
The company is already generating record revenue from producing gold and silver mines.
It has attracted some of the biggest names in the resource arena.
And it just announced the largest transaction in its history.
Yet incredibly… shares remain largely undiscovered below $1.
That creates an intriguing opportunity to get in early and low as this fast-emerging company enters its biggest growth phase yet.
What makes this story especially compelling is the business model.
Unlike the typical mining firm, this company doesn’t have to build or operate a single mine.
Instead, it puts its capital to work in carefully selected mining projects in exchange for a share of the gold and silver produced:
✔ Exposure to multiple producing mines without operating them
✔ Exploration upside and mine-life growth funded by mine operators
✔ Diversification across multiple metals and jurisdictions
✔ Growing cash flow to be deployed into new royalties and streams
✔ Powerful leverage to rising gold and silver prices
In other words… put capital to work once… generate cash flow… reinvest that cash flow into the next opportunity… rinse and repeat.
That’s the power of the royalty and streaming model – and this soon-to-be-known sub – $1 company is reaching a critical inflection point as you read this.
And there’s another piece of this story you absolutely need to know.
Behind the company is a longstanding strategic relationship with a major mining-focused investment firm – giving it direct access to a steady pipeline of deals across the global mining landscape.
And we’re already seeing that secret weapon hard at work.
The company has just inked a new gold streaming deal on an established producing gold mine – by far the largest transaction in its history – signaling just how much bigger this story is becoming.
And the smart money is already paying attention.
One of the sector’s best-known financiers has put his own money behind the firm and believes it has a durable competitive advantage in the royalty and streaming space.
Better still, he joins the company’s CEO in our exclusive interview.
We’ve put together a FREE online report revealing the full story – including:
✔ The royalty and streaming advantage
✔ Producing assets already generating cash flow
✔ Largest transaction in company history
✔ The secret weapon driving the deal flow
✔ Our exclusive in-depth interview with the CEO and special guest
And with shares still below $1, the opportunity to get in early is right now.
Click here for instant access… and discover this fast-emerging gold-silver royalty firm before the rest of the market catches on.
Japan Called 160 a Red Line. The Yen Has Tested It Again.
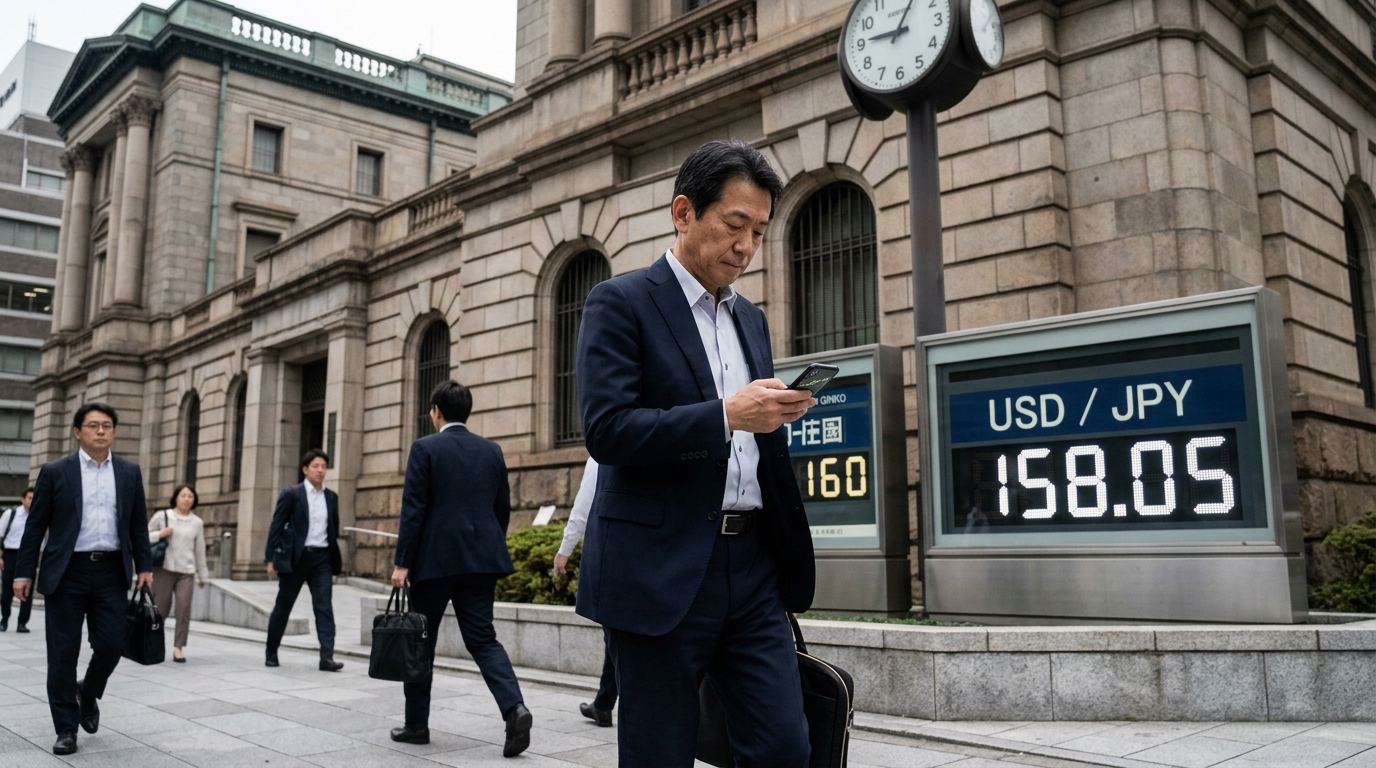
Every trader watching USD/JPY this week is really watching a game of chicken between the carry trade and Japan’s Ministry of Finance. The yen is sitting near 158. Tokyo has treated 160 as an intervention-risk zone more than a formal target. And the Bank of Japan, which raised rates to 1.25% in September, is now widely expected to pause at its October 29-30 meeting.
That combination tells you exactly what kind of market this is: one where a stated official ceiling is holding, but only barely, and only because traders are not yet confident enough to press through it.
What Happened This Week
After the hot U.S. consumer price report on Wednesday, USD/JPY climbed to 159.05, the highest level in a month and the weakest yen of October. On Thursday, Finance Minister Satsuki Katayama warned that Japan was prepared to take action in the currency market again if needed, and the yen strengthened back through 158. That sequence, spike on U.S. data, verbal warning, reversal, is the week’s clearest demonstration of how the pair is trading: not on fundamentals alone, but against a ceiling that officials keep reinforcing with words.
The Bank of Japan has signaled it wants to assess the impact of September’s move, and market pricing still leans toward a pause in October. December remains the next meeting traders focus on for another hike, but the exact odds move day to day and are not a stable fact worth anchoring on here. What matters is that the market has pushed the next genuine catalyst weeks down the road, which leaves the pair in a vacuum where the carry trade has every structural reason to keep pressing higher, and one political reason to hold back.
What the History of Intervention Actually Shows
This is not the first time Japan has drawn a line and had it tested. The record matters here.
In September 2022, Japan intervened to support the yen for the first time since 1998, after USD/JPY broke through the 145 level. Further operations followed in October, with Japan ultimately spending about ¥6.35 trillion on intervention across Oct. 21 and Oct. 24. The yen rallied sharply. Then the rate differential pulled it back.
In July 2024, Japanese authorities spent ¥5.53 trillion intervening, helping the yen jump from as low as 161.76 per dollar to as high as 157.30. Again, a powerful short-term squeeze. Again, temporary relief.
Then came 2026. Between April 28 and May 27, the Ministry of Finance bought about ¥11.73 trillion of yen. Then, in late July, Tokyo and Washington carried out a rare joint intervention after USD/JPY moved above 160, sending the pair from the mid-160s toward the mid-155s. USD/JPY is now back near 158.
The significance of these episodes is not that intervention failed, but that it behaved exactly as the underlying structure would imply. In both the 2022 and 2024 cases, Japan’s operations delivered sharp, tradable reversals. But without a sustained change in the rate gap, the market’s incentive to rebuild short-yen exposure gradually returned.
The blunt lesson across all three episodes: intervention buys weeks, not regimes. Durable reversal requires the rate gap to close, not just the MOF to spend reserves.
The rate gap is not the only variable the BoJ is watching. Japan’s producer price miss gave the cautious wing of the Bank of Japan cover to delay further tightening.
The Political Complication
There is a second force at work that professional traders are watching as closely as the yen level itself: Prime Minister Sanae Takaichi’s relationship with the BoJ. Reuters reported this summer that the careful wording of Japan’s annual fiscal and economic blueprint was revised after earlier drafts unsettled markets, including by adding a footnote that explicitly references a legal provision protecting the BoJ’s independence. Earlier this year, headlines suggesting political pressure on the central bank repeatedly coincided with abrupt yen swings. That is reassurance, not resolution.
What Comes Next
Japan’s nationwide September CPI is due on Friday, Oct. 23. It is the last major inflation reading ahead of the Oct. 29-30 BoJ meeting. Tokyo’s September inflation data already showed an upside pulse, with Tokyo core inflation at 2.7%, as energy-subsidy effects faded and some household costs jumped. A strong nationwide print would reinforce the idea that additional tightening later this year remains live. A softer print would make the BoJ’s next-step timing murkier, and that is exactly the kind of vacuum where carry dynamics usually reassert themselves.
If September CPI comes in hot, the next-hike question stays alive and the pair is more likely to churn rather than trend. If it surprises to the downside, the BoJ’s timetable gets murkier, the carry trade gets cheaper to run, and 159 becomes 160 faster than verbal intervention can keep up.
The yen’s path also depends on what the U.S. side of the rate gap does next. The same September CPI print is the last inflation reading the Federal Reserve will see before its October rate decision.
The Trader’s Lesson
When a government draws an explicit line in a market, the instinct is to test it. The smarter instinct is to ask whether the line is backed by something the market cannot outrun. In the yen’s case, the MOF has firepower but not a policy change. Every intervention in 2022, 2024, and 2026 produced a sharp reversal followed by a drift back toward the pressure point. Watch Oct. 23’s CPI not for the number alone, but for what it tells you about when that differential starts to narrow in earnest.